Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 683

Meg on SMSFs - Division 296 actuarial certificates

Never give an actuary a new certificate to talk about it. She will want to talk to you about it or worse, write an article about it.

But hear me out: Division 296 actuarial certificates will be interesting. They will drive how an SMSF’s Division 296 earnings are divided between the various member accounts. In other words, they will play a significant role in calculating the tax bill.

The allocation is based on each account’s average value during the year (compared to the fund as a whole). The method appears logical, and is actually more or less the same as the method used in actuarial certificates for pension funds. However, it can produce some unexpected results when an SMSF has large transactions, specific investment portfolios for different members or reserves. This article explains how the allocation works and why – sometimes – it won’t feel right.

How will Division 296 actuarial certificates attribute earnings?

SMSFs with members subject to Division 296 tax will need to calculate their 'Division 296 earnings' at a fund level. This starts with the fund’s taxable income but is adjusted for a host of things – adjusted capital gains amounts for funds that opt into some special relief, adding back income that is exempt from tax because the fund has pensions etc.

This income then needs to be notionally divided up between the members – so that the ATO can work out how much Division 296 tax each member should pay. This is where the new actuarial certificates come in.

The legislation provides a formula for actuaries to use here. The % of the SMSF’s overall Division 296 earnings that is allocated to each 'interest' (member account) is broadly as follows:

Average value of the member account
---------------------------------------------------------------------------------------------------
Average value of all member accounts + Average value of pension reserves

The 'pension reserves' part is largely for funds that have (or used to have) defined benefit pensions. While most software systems show an 'account balance' for these pensions, technically they’re not member accounts. Rather, they’re reserves the trustee uses to pay the defined benefit pension.

(Note: SMSFs providing defined benefit pensions won’t use this method to calculate the 'earnings' attributable to the defined benefit pension itself. They’ll only use it for all the other member accounts. There’s an entirely separate formula for earnings when it comes to defined benefit pensions.)

An example – the simplest case

Monica and Chandler both belong to the same SMSF and their super balances over the 2026/27 financial year are as follows:
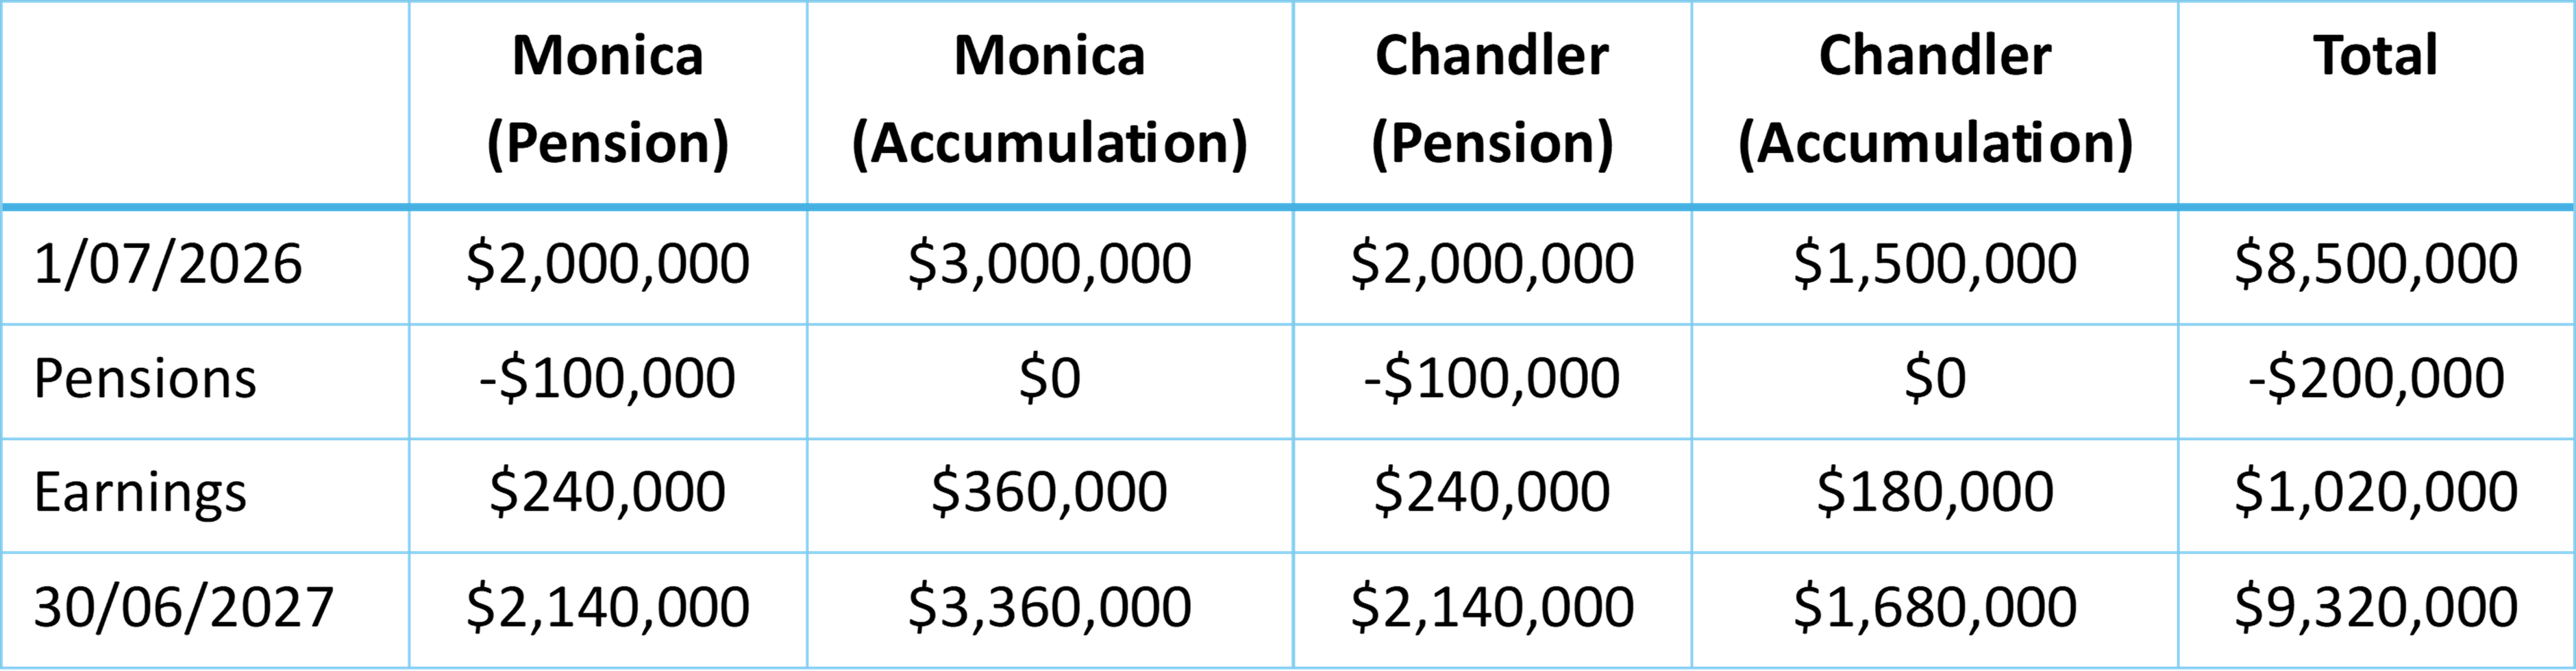

(The pensions are simple account-based pensions, not defined benefits)

The SMSF’s actuary would work out the average value of each member account. In doing the calculations, the actuary would allow for the timing of events like pension payments and contributions. In this case, for example, let’s say the pension payments weren’t taken out until the end of the year. Just before her pension payment on 30 June, Monica’s pension balance was $2,240,000. The average value of Monica’s pension would be something like:

0.5 x ($2,000,000 + $2,240,000) = $2,120,000

Once this calculation has been done for all the various member accounts in the fund, it’s possible to translate it into a proportion or percentage as follows:
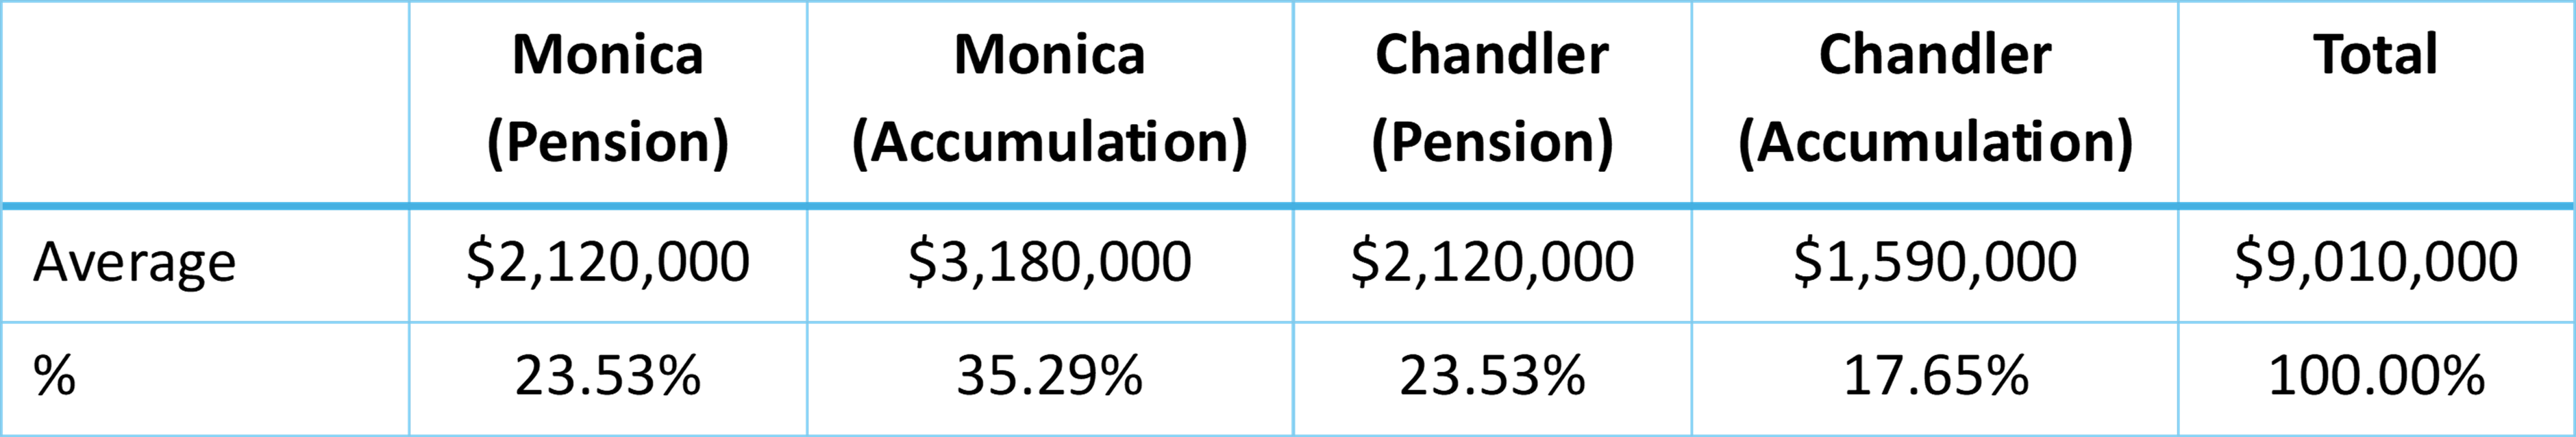
In this example, the amount of earnings taken into account for Monica’s Division 296 tax would be:

58.82% (ie, 23.53% + 35.29%) x the whole fund’s Division 296 earnings

If the fund’s Division 296 earnings overall amounted to (say) $800,000 in 2026/27, the amount used to calculate Monica’s Division 296 tax would be $470,560.

Remember, of course, calculating Monica’s actual tax bill has some more steps. We’d need to work out the proportion of her balance that is over $3 million. In this example, it’s 45.45% (her balance at the end of the year is $5.5 million). Her actual tax bill would therefore be:

15% x 45.45% x $470,560 = $32,080.43

If the fund’s Division 296 earnings was much higher, Monica’s earnings (and tax bill) would also be higher.

When can Division 296 actuarial certificates produce unusual outcomes?

Large transactions for just one member

The example above 'feels' about right. Monica will be allocated around 60% of the fund’s Division 296 earnings and Chandler will get the other 40%. That looks about right given her pension and accumulation balances (when added together) account for about that much of the fund’s balance at the start and end of the year.

They’ve both belonged to the fund all year and so it feels 'fair' that any capital gains or other income should be split in that way.

But what if Chandler actually cashed out his super in full right at the end of the year? If it happened (say) on 30 June 2027 the average balance for each member wouldn’t change much (the split between Monica and Chandler would still be around 60 / 40).

But making Chandler’s benefit payment might have triggered a large capital gain – let’s say that increased the fund’s Division 296 earnings from $800,000 to $1.5 million.

Now, Monica’s Division 296 tax bill is much bigger – it will be based on earnings of $882,300 (58.82% x $1,500,000) and will amount to:

15% x 45.45% x $882,300 = $60,150.80

So action taken by Chandler has impacted Monica’s tax bill.

That will feel odd.

In fact, it would be even worse if Chandler withdrew his super right at the start of the year. In that case, the actuarial certificate would probably attribute close to 100% of the fund’s Division 296 earnings to Monica. Including all of the capital gain realised to pay Chandler’s benefit!

For most SMSFs, this won’t be an issue very often. It’s likely to emerge most commonly when someone dies as that’s a time when large amounts are taken out of super, often for just one of the two members.

Separate member investment portfolios

The rules for these actuarial calculations specifically require actuaries to ignore anything like separate investment portfolios for particular members or member accounts.

Instead, every fund needs to be treated as a “pooled” SMSF for these calculations.

Imagine a scenario where:

  • Two SMSF members (Harry and Ginny) have roughly equal balances but maintain entirely separate investment portfolios,
  • Harry’s assets have produced virtually no income during the year (perhaps they held a property which was not tenanted). Ginny’s portfolio generated significant income and/or capital gains.

The actuarial certificate would likely provide that around 50% of the overall income would be attributed to each member. Harry would pay Division 296 tax on this income despite receiving absolutely no benefit from it.

Fortunately different investment portfolios are rare in SMSFs, particularly where the balances are very large. But it will be interesting to see if this change prompts those who have them to reconsider.

Non-pension reserves

The formula above specifically refers to pension reserves. Mathematically, this is important to make sure that earnings on these reserves don’t fall into the other member(s) accounts.

For example, Rachel and Ross both belong to the same SMSF. Ross has a defined benefit pension and the account balance supporting that pension is $3 million. Rachel has an accumulation account of $5 million and there are no other member accounts in the fund. Let’s say these are the same as the average balances over the financial year. The formula will mean the earnings attributed to Rachel for Division 296 tax will be:

$5m (average value of Rachel’s accumulation account)
---------------------------------------------------------------------------------------------------
$5m (average value of all the member accounts) + $3m (average value of the pension reserves)

i.e. 62.5%.

(Note: Ross’s Division 296 earnings will be worked out completely differently, using a formula. It won’t equal the remaining 37.5% of the fund’s Division 296 earnings.)

But what if the reserves weren’t pension reserves? Perhaps they were investment reserves leftover from a strategy carried out in the past? Or a reserve that used to be a pension reserve but has made allocations to members that caused it to stop being a pension reserve?

In that case, the formula above would be:

$5m (average value of Rachel’s accumulation account)
---------------------------------------------------------------------------------------------------
$5m (average value of all the member accounts) + $nil (average value of the pension reserves)

Ie 100%.

In other words, all of the fund’s Division 296 earnings would be attributed to Rachel even though 37.5% of the fund doesn’t even belong to her – it’s sitting in a reserve.

Final thoughts

Division 296 tax presents a host of new issues to consider for SMSF trustees. When deciding to sell particular assets, trustees often consider the CGT impact before making a change. Now, the consideration will need to extend to the Division 296 tax impact which means thinking about:

  • Who will the earnings be attributed to?
  • Do they have other super (which will increase the proportion of the capital gain subject to Division 296 tax)?
  • Are there steps we could take first to reduce the impact?


Meg Heffron is the Managing Director of Heffron SMSF Solutions, a sponsor of Firstlinks. This is general information only and it does not constitute any recommendation or advice. It does not consider any personal circumstances and is based on an understanding of relevant rules and legislation at the time of writing.

For more articles and papers from Heffron, please click here.


  •   7 October 2026
  • 12
  •      
  •   
12 Comments
Peter R
October 10, 2026

Good luck trying to find out. I tried, comsuper sent met to the ATO who after a long phone call admitted they did not have the information yet and sent me two useless links to "information" on their website.
"Please see below for information that may help you.
www.ato.gov.au/individuals-and-families/super-for-individuals-and-families/super/growing-and-keeping-track-of-your-super/caps-limits-and-tax-on-super-contributions/division-296-tax/division-296-tax-on-large-super-balances#ato-Furtherguidance
www.ato.gov.au/individuals-and-families/super-for-individuals-and-families/super/growing-and-keeping-track-of-your-super/caps-limits-and-tax-on-super-contributions/division-296-tax/how-division-296-tax-is-calculated"

AI did a much better job I think.

Meg Heffron
October 21, 2026

The defined benefit funds themselves will work out the figures OldbutSane. It's not something you will have to arrange and I assume you won't have to pay for it either. From 30 June 2027 onwards, funds like ComSuper will have to report this value automatically to the ATO every year and you'll see it on myGov. I think they do this around October each year. They have to do it for everyone, even if you're not subject to Division 296 because the definition of total super balance (used for a host of other things) has changed. The ATO will then use this information (together with anything reported by your SMSF) to work out if you're over $3m. If you are, they (the ATO) will go back to ComSuper for more information (your "earnings" for Division 296) and then the ATO will work out your tax. You won't have to do anything.

The real challenge for people in your position is that you probably have no idea what the amount is likely to be because ComSuper has never had to report it for you before. If you're in the CSS, they have special factors they use for divorcing couples at the moment (set out in some horrible formulae here : https://www.legislation.gov.au/F2025L00281/latest/text/2) and they will be able to use these or come up with some new ones that are specifically for Division 296. I don't know what they're doing yet - and in fact they may not even know. A lot of defined benefit funds are still deciding as I understand it.

Barry
October 11, 2026

I believe that if an SMSF only has one member, then you don't need to worry about Div 296 actuarial certificates because all of the income from that SMSF is attributed to just one member. Meg may correct me if I'm wrong.

1
Meg Heffron
October 21, 2026

Correct Barry - you don't need an actuarial certificate if there's only one member.

Rob
October 08, 2026

Meg - layer upon layer of complexity. The other one that hides in plain sight is the need to maintain two cost bases - pre and post June 30th 2026. The mind boggles how complex this may become in 5 years as a fund turns over investments. My personal approach was to sell everything in May and reinvest in July - at least that side of the books are clean - some tax brought forward a price worth paying!

The other issue that keeps popping up as I talk to people, so many freak out at the "number" of $3m as if it is the edge of a cliff. It isn't. There remains a widespread misunderstanding as how the formula actually works, the key variable being the "proportion" over $3m as you have frequently pointed out. For most people with balance of $3-10m, yes there is a tax on wealth, but understand the likely impact before jumping!

OldbutSane
October 11, 2026

I didn't think the CGT changes affected super, so why do you need to sell and buy across 1 July 2027 (let alone 2026!).

lyn
October 11, 2026

OldbutSane,
No expert but I read 2026 as a typo for 2027 & then referral to having a common post - 2027 method for future CGT from 1/7/27 instead of carrying assets into 2027 on current method, to make easier calcs than mix of 2 methods thereon. If sale price suits, considering for self in small capacity just for ease of records--much more reading & understanding lies ahead for me, but only if price meets original goal.
Starting to make one think 'set & forget until need' is old hat but assign percentage to more frequent trading within 12mths (at no disc gain) when price suits & allow for tax on 100% gain! Think longterm planning about to go out of fashion for many in this created mess.

Maybe Rob will reply to yours to clarify.

Meg Heffron
October 21, 2026

I suspect what Rob is referring to is the fact that for Division 296 tax, SMSFs have the option to just pay Division 296 tax on their capital gains built up after 1 July 2026. Most SMSFs will achieve this by making an election to adopt a special cost base for their assets that is the 30 June 2026 value. This special cost base ONLY applies for Division 296 tax - normal fund taxes will still be worked out using the "proper" cost base (back when the asset was acquired). Hence Rob's point about many SMSFs needing to keep records of 2 cost bases for all their assets - one for fund tax and one for Division 296 tax. Fortunately, the major software providers in SMSF-land (Class, BGL and superMate) are all over this and will make the job of tracking these cost bases easy for accountants. But if you do this work yourself without the software, or if your accountant doesn't use specialist SMSF software, I can see it being tricky.

Meg Heffron
October 21, 2026

Absolutely right Rob - if you have $3m + $1 you will pay basically no Div 296 tax. It's a sensible tax in that way (and that way only) - you don't get a massive penalty simply for crossing the $3m threshold.

Tim
October 08, 2026

Wow, this is complicated!
I am glad that my SMSF only has one member, with all funds in the pension phase.

Hazard
October 23, 2026

OldbutSane,

See https://www.firstlinks.com.au/div-296s-million-dollar-reset-worth-25000

"The transitional election lets an SMSF (and other small funds) treat the market value of every asset it held directly on 30 June 2026 as a fresh cost base, for Division 296 purposes only. Ordinary capital gains tax is untouched. Gains accrued before this month then never enter Division 296 earnings; only growth from here does. The election is made at fund level, covers every asset or none, and once made cannot be unwound."

The valuation at 30 June 2026 (no typo) is also about protecting losses from Div 296 tax based on the market value of an asset at that date, not your original cost base.


Leave a Comment:

RELATED ARTICLES

Meg on SMSFs: Where are the risks in our major super sectors?

Red flags to watch out for when considering an SMSF

Navigating SMSF property compliance

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.