For years, one of the most famous economic findings was that money could improve wellbeing only up to a point. I think this likely provided many with a sense of comfort, because it suggested there were limits to what the pursuit of additional wealth could achieve.
More recently, newer research by the same author has complicated the picture by implying that emotional wellbeing continues to improve alongside income, well beyond the thresholds that were previously identified.
This finding came back to mind when reading Shane Oliver’s latest insights on the economics of happiness. Much of the developed world has seen decades of rising prosperity, yet measures of happiness have remained broadly flat.
The two observations are difficult to reconcile. At the individual level, higher incomes seem to be associated with greater wellbeing. At the societal level, ever-increasing prosperity does not appear to be producing ever-increasing happiness.
Beyond the academic jargon, economics has always struck me as an attempt to understand human behaviour. This is why I think the paradox is so fascinating. The average Australian today enjoys material comfort that would have bewildered previous generations. So why aren’t we correspondingly more content?
A life our ancestors would envy
To begin answering that question, we need to step outside our own moment in history. For thousands of years, life revolved around survival and retirement as we understand it today was unimaginable.
My grandmother was born towards the end of World War II. She likes to joke that for most of her life, the family was vegetarian for economic, rather than moral reasons. Meat was a luxury not afforded to the masses.
Truth be told, I occasionally find the thought strangely unsettling. We tend to mull over history as though it belongs to another world when in fact, it often still sits at our dining table. By these standards, many of us now inhabit a different universe entirely.
We can communicate instantly across continents and be anywhere in a matter of hours rather than months. There are now medical treatments for ailments that would have once rendered one incapacitated. A visitor from another century would assume that we had solved the problem of happiness. However, the chart below suggests otherwise.
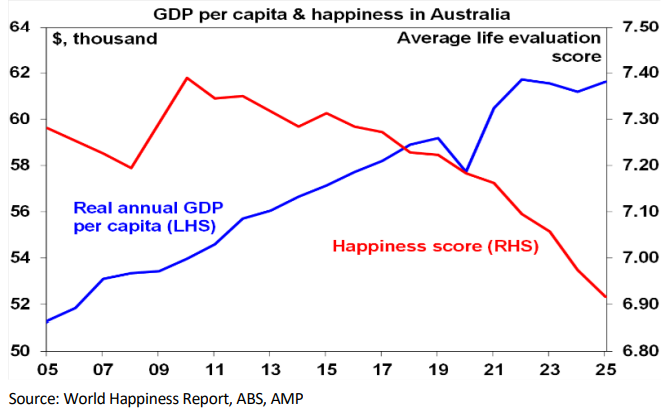
If happiness is primarily a function of material conditions, we should be living through a golden age. Of course, in most respects we certainly are, but clearly comfort and happiness are not quite the same thing.
When money stops being the main problem
A common explanation for this paradox is what psychologists call hedonic adaptation. Economists often refer to this as the hedonic treadmill. It seems that humans tend to adapt quickly to changes in circumstance. The excitement of a new house fades, just as the long-awaited retirement eventually becomes a part of everyday life.
Shane points out that select researchers argue chasing greater levels of material success leads to the discovery that improvements in happiness are only temporary. There might be a good deal of truth to this, though I don’t believe it explains as much as we think.
One thing that strikes me about debates on money and happiness is how quickly they present a false dichotomy. Either money creates happiness or it comes from somewhere else entirely. But as we know, most things tend to exist in the grey.
Financial insecurity is not simply an inconvenience or romantic condition that builds character. It is incredibly difficult to contemplate self-actualisation when you are suffering or worried about keeping a roof over your head. Those who have experienced it know that money can solve an extraordinary number of immediate problems. It is for this reason that I’ve always found the phrase "money can't buy happiness" rather hollow.
The evidence strongly indicates the richer countries tend to be happier than poorer ones. Yet there is also something more complex going on. Switzerland is significantly wealthier than New Zealand but reported happiness levels are similar.
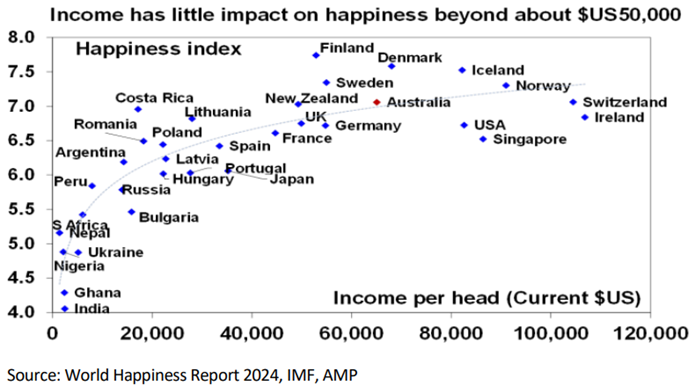
Extra income appears to matter immensely when people are struggling to meet basic needs. However, beyond a certain level, the gains are less dramatic. The better question is why income’s contribution to happiness appears to change beyond a point. Perhaps wealth alters the nature of our problems rather than eliminating them.
The tyranny of expectations
I often feel that modern prosperity has replaced physical burdens with psychological ones. Though there is less uncertainty about survival, perhaps there is more about our significance.
Another finding highlighted in Shane’s paper is that people naturally compare themselves to others. If everyone's income rises together, our relative position is largely unchanged, even if absolute standard of living has improved.
Of course, comparison is not a new notion, but what has changed significantly is its scale. We have moved from comparing ourselves with neighbours, colleagues and a handful of local rivals, to everyone imaginable.
Social media now enables a constant stream of curated lives, which when measured against our own can appear much more prosperous. Shane highlights this as a possible contributor to declining wellbeing, especially among younger people. However, comparison alone likely doesn't explain everything.
A mere few decades ago, an overseas holiday was the sort of experience people spoke about for decades. Today, some regard it as an annual entitlement. I can’t be the only one who becomes mildly irritated if an app takes more than a few seconds to load. I say this while holding a device in my hand that contains most of humanity’s accumulated knowledge.
We possess a strange ability to normalise yesterday's miracles. It is easy to pass this off as ignorance or greed, but it could also simply reflect that hedonic adaptation.
What happens after we reach the finish line?
I would hesitate to conclude that financial ambition is somehow misguided. The more interesting question may not be why people pursue wealth in the first place, rather what happens once they have largely succeeded.
I’d imagine many readers have spent decades saving consistently, investing through several market cycles and preparing diligently for the future. If all goes well, eventually the future arrives.
For much of our working lives, we are occupied by the challenge of accumulation. Then once financial security is achieved, the question is no longer whether we have enough, but what ‘enough’ was even for. What do we do with the freedom that wealth creates?
The purpose of prosperity
I've gradually come to think that the most useful way to view money is as a facilitator of happiness, rather than a source itself. This may be why the relationship between money and happiness remains elusive. A certain level of wealth cultivates a sense of security and choice. Whilst these are not trivial achievements, purpose likely belongs to a different category altogether.
The stern face of Sir John Monash on the $100 note cannot instruct us on how to spend our freedom, or what kind of life is ultimately worth living.
Accumulating "enough" is never the end of the story. For those fortunate enough, it is just the beginning of another chapter.
Simonelle Mody
Also in this week's edition...
Several planning windows are narrowing for those affected by Div 296. Liam Shorte walks through the initial moves to make before your options disappear.
Shani Jayamanne explores one overlooked clause in an estate plan that may create a ticking CGT time bomb for families.
Similar-looking investments can still produce surprisingly different results. Martin Smith analyses the hidden trade-off in fixed income ETFs.
A new study shows that the mortgage free retirement is fading. Retirement researcher, Osei Wiafe suggests a nation-wide rethink.
The transition to retirement can often be harder and less fulfilling than expected. Derek Gascoigne poses a key question to ask before we hit this stage.
Some investors spend years chasing the perfect strategy. Christine Benz makes the case for a 'good enough' portfolio.
Jason Teh is back to evaluate whether the US equity market is really as expensive as the CAPE ratio suggests.
Curated by Simonelle Mody and Leisa Bell
Latest updates
PDF version of Firstlinks Newsletter
Listed Investment Company (LIC) Indicative NTA Report from Bell Potter
Plus updates and announcements on the Sponsor Noticeboard on our website