The recent rise in US equity market concentration has left investors asking whether too much of the market's fortunes now depend on too few stocks.
A commonly used measure of concentration approximates how many companies a market “effectively” contains by expressing its concentration as the equivalent number of equally weighted companies. In the US, the “effective number of companies” fell from around 200 in mid-2006 to around 50 by the end of 2025.[1]
But there’s an important question behind those numbers: does a more concentrated market necessarily mean greater risk or lower returns ahead? Vanguard’s research suggests the answer isn’t so straightforward.
Concentration isn't happening everywhere
But before we get into this, let’s first have a look across equity markets around the world.
The US may be getting more concentrated, albeit not to an extent that is unprecedented, but that doesn't mean the same thing is happening around the world.
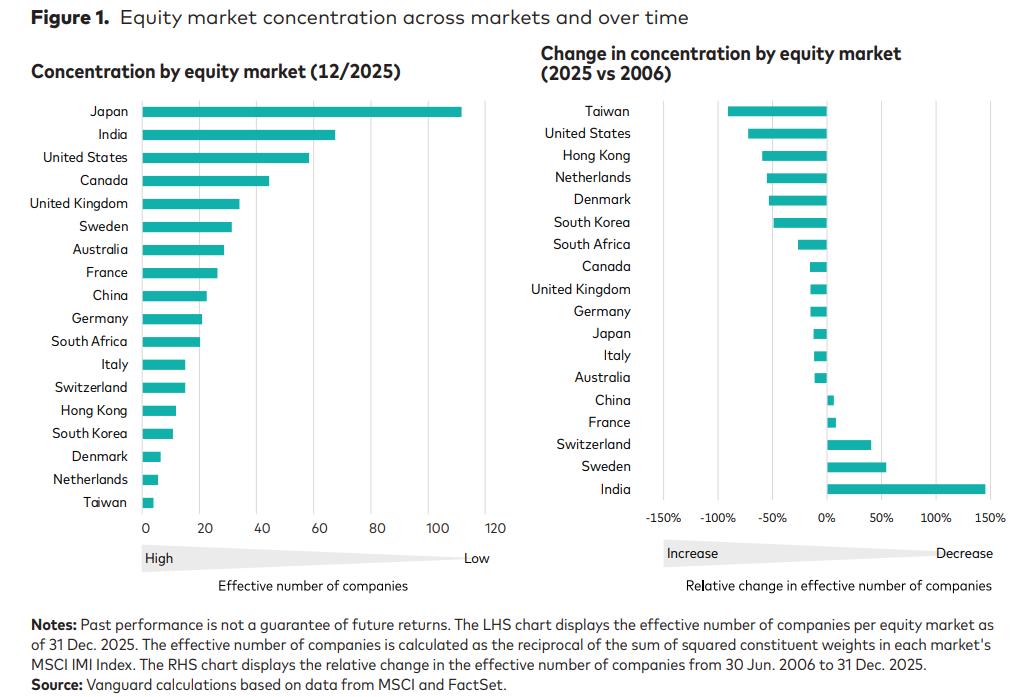
Vanguard looked at 18 developed and emerging share markets and found very different experiences. While concentration has increased in the US, India has become considerably less concentrated in recent years. Australia, meanwhile, has remained relatively stable.
jcp-fig1-equity-market-concentration.png
Note: The example is illustrative only and is based on the factors stated. It should not be taken to contain or provide an estimate of future market performance.
That's an important bit of context. Market concentration isn't one global trend moving in the same direction.
What’s more, next to changes in concentration, it is important to also look at levels of concentration. And here, the US is far from being an outlier. In fact, most equity markets, including the Australian market, are more concentrated than the US market is.[2]
A concentrated market isn't a crystal ball
But perhaps the more interesting question is whether knowing how concentrated a market is helps us anticipate its future performance.
Vanguard tested this by looking at concentration and what happened to markets in the following year. Researchers considered returns, volatility, risk-adjusted returns and whether markets experienced falls of at least 10% or 20%.
The verdict? There wasn't a clear pattern simply linking concentration with what happened next. The analysis didn't detect a relationship between concentration and returns, risk-adjusted returns or large market falls. It did, however, find a positive relationship with volatility, but the effect was relatively small.[3]
But why is the link not much more straightforward? After all, we know that diversifying investments across companies is an effective way to reduce company-specific risk. The more diversified a portfolio is, the less it depends on what happens to any one company.
The answer lies in the characteristics of companies themselves. Vanguard research shows that the largest companies – those that account for a market being concentrated – tend to be much less risky investments than the smallest companies in a market.[4] This is, in part, driven by the fact that these large companies are not homogeneous blocks but have highly diversified lines of business.[5]
So should investors ignore market concentration altogether?
Market concentration is still worth understanding. And building well-diversified portfolios is still a key contributor to long-term investment success.
What’s more, for investors who still feel uncomfortable with any level of concentration in a given market, there are investment options available such as funds that equal-weight rather than market-cap-weight all of their components. But these investment options come with costs such as active risk and higher turnover. Hence, investors may end up exchanging one risk for another.
Looking beyond the headlines
When a handful of companies dominate a market, the numbers can look dramatic. But they don't tell investors what will happen next. A market-cap-weighted index adjusts with those changes rather than requiring investors to predict the winners in advance.
For investors, the better response to concentration may therefore be to step back from the individual index and consider the whole portfolio.
Diversification across Australian and international equities, developed and emerging markets, large and small companies, and defensive assets such as bonds can reduce dependence on any single company, sector or market.
Market concentration deserves attention. But concentration alone isn't a forecast and avoiding it isn't a free lunch.
[1] Ning Yan, CFA and Jan-Carl Plagge, Ph.D, On the link between concentration in stock index portfolios and returns: Separating myth from reality, Vanguard, 2026.
[2] The higher concentration levels of other markets can also be a by-product of many of these markets being more narrow.
[3] Ning Yan, CFA and Jan-Carl Plagge, Ph.D, On the link between concentration in stock index portfolios and returns: Separating myth from reality, Vanguard, 2026.
[4] Ning Yan, CFA and Jan-Carl Plagge, Ph.D, On the link between concentration in stock index portfolios and returns: Separating myth from reality, Vanguard, 2026.
[5] Magnificent Seven: More diverse than they may appear | Vanguard Australia FAS
Jan-Carl Plagge, Ph.D., is global head of Indexing, Active, and ESG Research and the head of the Investment Strategy Group, Asia-Pacific at Vanguard, a sponsor of Firstlinks.
Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) has not taken your objectives, financial situation or needs into account when preparing this article so it may not be applicable to the particular situation you are considering. Before you make any financial decision, you should seek professional advice from a suitably qualified adviser. This article was prepared in good faith and we accept no liability for any errors or omissions.
Past performance information is given for illustrative purposes only and should not be relied upon as, and is not, an indication of future performance.
For more articles and papers from Vanguard, please click here.