Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 571

A licensing regime can get super funds moving on retirement

The Retirement Income Covenant (RIC) was introduced in July 2022 and requires all super funds to develop a retirement income strategy to assist their members in meeting their retirement needs. However, progress made by funds in developing their retirement income strategies has been slow and uneven, as highlighted by two joint reviews by APRA and ASIC found here and here.

Our own discussions with super funds finds something similar. We are observing high dispersion in the progress in developing retirement offerings and the quality of those offerings across funds. Some are well-advanced, while others are lagging badly. No super fund has everything in place to assist all their members with all their retirement needs.

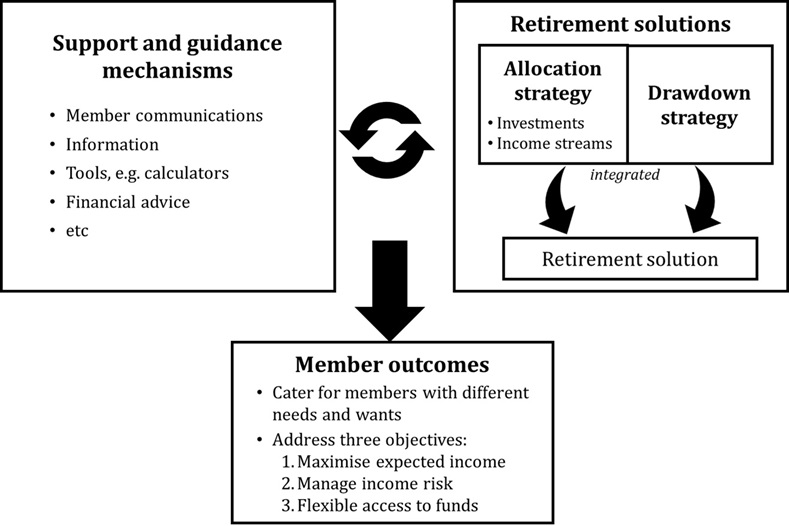
A super fund retirement income strategy should assist fund members through a range of retirement solutions that convert assets into income plus support and guidance mechanisms (see diagram below). However, no super fund yet has the capability to offer bundled solutions comprising investments, lifetime income products and a drawdown plan that are tailored to the needs of the member (or member cohorts). Support and guidance mechanisms are also still being built out. Members have to either seek personal financial advice on how to combine these building blocks or do it for themselves. Many fund members are left floundering as a result.

Components of retirement income strategies offered by super funds
What’s going on here?

Assisting retirees is tough as their personal circumstances can differ in significant ways. Retirees vary in their available assets, access to the Age Pension, household situation, and more. They differ in how they engage with financial decisions. Both the type of retirement solution and support and guidance they need can thus vary greatly. Super funds have to develop a capacity for ‘personalisation’ to cater for these differences. Developing the products, processes and systems takes time and effort, and is quite costly.

However, something else is happening other than development lags. The commitment to delivering a quality retirement offering varies considerably across funds.

Some super funds have a very low portion of members and assets in the retirement phase. For example, APRA data for June 2023 reveals that 27 of the top 50 funds had less than 5% of member accounts in retirement products. And as mentioned above, retirement is costly. There is also uncertainty over how the regulations around retirement might evolve. And super funds have other pressing priorities to deal with, e.g. mergers, organic growth, cybercrime. In effect, some funds face a weak business case to commit a lot of resources to pushing ahead on retirement.

Meanwhile, the RIC only requires super funds to have a retirement income strategy, not necessarily to produce a good one. In this context, the variable progress across super funds is not all that surprising. The problem that arises is that retired or retiring members of laggard funds may be left behind.

Retirement licensing would help move the industry forward

Establishing a retirement licensing regime would help get the super industry progressing in the right direction. It is important that super funds are effective players in retirement, especially as it is unlikely that every retiree will be able to access personal advice from a financial planner. We set out our case in a ‘green paper’ that can be found on the Conexus Institute website here, and welcome any comments. A licensing regime would basically work as follows.

Super funds would be required to meet licensing conditions before being permitted to offer retirement solutions to their members. The licensing conditions could be based around having in place the range of capabilities needed to supply suitable retirement solutions and guidance services to their members, including meeting their individual needs. The regime would formally commence at some future date, allowing funds time to prepare.

Super funds would then face a choice. They could undertake to commit to building the required capabilities within the specified time frame. Or they could decide not to participate in the retirement market, or perhaps defer participation to a later time.

Retirement licensing can offer a number of benefits:

  • Licensing would get funds that do commit to expeditiously push ahead in delivering on retirement.
  • Funds that do not want to commit can opt-out. One issue with the RIC is that it requires all funds to develop a retirement income strategy regardless of whether or not it makes sense for them to do so. Giving funds a route out will reduce the risk of some funds moving forward with low-ball offerings.
  • The licensing conditions could be used to establish minimum standards. This helps overcome another issue with the principles-based RIC – it is silent on required standards.
  • Regulatory uncertainty over what is expected of super funds would be reduced. We envisage that the licensing conditions might be linked to how funds will be assessed by the regulators.

There are of course some issues. One is that procedures would be required for non-licensed funds to ‘hand-off’ members as they approach and then enter retirement. Some early comments we have received are around increased regulatory burden on the industry. While there will be cost involved in administrating the licensing regime, our view is that licensed funds will only be asked to do what they should be doing anyway, while regulatory burden is actually reduced for funds that opt-out. Finally, retirement licensing should help reduce the overhang of regulatory uncertainty.

A retirement licensing regime would be a powerful mechanism for ensuring that only super funds that are committed to delivering a retirement income strategy to a satisfactory standard are operating in the retirement market. We see this as important for ensuring that the needs of all retirees are adequately served, given that many will probably be relying on their super fund in retirement.


David Bell is the Executive Director of The Conexus Institute. Geoff Warren is a Research Fellow with the Conexus Institute, and an Honorary Associate Professor at the Australian National University.


  •   31 July 2024
  • 17
  •      
  •   
17 Comments
Free market advocate
August 01, 2024

Not sure about a licensing regime. Why not let the free market work its magic? The urge to fix things immediately can lead to all kinds of unintended consequences.

David Bell
August 01, 2024

We're quite open to free markets as well. A reasonable portion of the paper is dedicated to that very issue. Unfortunately in the case of retirement we're concerned the market will not work well for many retirees, especially those who aren't advised by independent advisers. The financial products and decisions are hard to compare making choice of solution and choice of provider difficult.

AlanB
August 02, 2024

No. No. No. The last thing we self funded retirees and SMSF trustee need is more regulation and more complexity. Nor do we want to be pushed into the clutches of so called independent advisors. Wouldn't they salivate at taking control of our savings. Licensing is a barrier to entry and always promoted by those in an industry to gain benefits for themselves, never for the public they cynically claim to be protecting. Licensing will require more government bureaucracy and interference, as industry self regulation rarely works, unless to protect the fees and activities of licensed members. The ultimate aim of licensing would be to drive more people from SMSFs, along with funds and fees, into industry super funds, for the benefit of licensees. Self funded retirees and SMSF trustees are not calling for licensing so we should all be wary of those who are promoting their own interests, at our expense.

David Bell
August 02, 2024

Hi Alan, thanks for sharing your thoughts. We considered many of the concerns you have raised when working on this and I think they are all addressed. Firstly, this is all about APRA-regulated super funds, and has nothing to do with SMSF's. Secondly, if a member wanted to drive their own retirement through an APRA-regulated fund the only difference would be (under a licensing regime) is that the fund would have met minimum conditions so you are starting from a sounder position when making your retirement decisions. Finally, the regulatory overhang in the sector (around how retirement will be assessed) will be reduced, creating a clearer pathway for funds to innovate.

David
August 04, 2024

All I need, in my APRA-regulated super fund from which I run my retirement finances, is to be left alone to do just that. I do not need any further regulation which will undoubtedly embed further cost into said fund.

Some of us know exactly what we're doing and don't require any further assistance. Your "starting from a sounder position when making your retirement decisions" is my "increased cost and bureaucracy".

What happens if my fund, faced with licencing, either declines to participate, or fails the licencing test?

Just leave me alone.

John
August 02, 2024

Would those regulations include the retail and bank managed funds ??

David Bell
August 02, 2024

John - if you mean retail super funds then yes, the intention would be that a retirement licensing regime would apply to all APRA-regulated super funds. Those managed funds which aren't part of the superannuation system would not be captured.

BeenThereB4
August 02, 2024

First of all go back to the Cwlth Government (Minister Jones) and point out that their regulations have led to a vast reduction in Advisers because of lunatic requirement for Financial Advisers of long-standing to study/ complete an Ethics exam, and other regulations. I am one of many who were unwilling to do FASEA exam following servicing clients with their SMSFs for 20+ years.

From my experience, major issue is financial illiteracy and lack of engagement of many people with financial matters. This leads to discomfort with automated systems. I use a major institution's Super Fund service. When I had a problem, I was able to have a sensible conversation with a knowledgeable representative. I now have to go through a tedious CHAT process.

Too many people in Canberra are completely out of touch IMHO

Acton
August 02, 2024

"The Retirement Income Covenant (RIC) was introduced in July 2022 and requires all super funds to develop a retirement income strategy to assist their members in meeting their retirement needs."

In 2021 I put a submission in to Treasury on the Retirement Income Covenant, giving reasons why self-managed superannuation funds should be exempted from the proposed requirement to have a mandatory retirement income strategy. Following public submissions, amendments were made to the draft legislation so the Retirement Income Covenant does not apply to trustees of self-managed superannuation funds.

David Bell
August 03, 2024

I can reassure you that this policy idea is only focused on APRA-regulated super funds.

Chris
August 02, 2024

This is a worthwhile contribution to the debate.
However, by far the biggest impediment - and I would suggest the driver for a lot of cost and confusion - to people approaching retirement is the current maze of rules and regulations in this area. Just understanding whether or not you can access the age pension is difficult because of the way the asset and incomes test operate and whether you are single or a couple, your ages and whether or not you are a homeowner. Then you have superannuation which most people have but many don't really understand particularly how you actually draw money out once you retire. Then you have the interaction between these basic foundations and your home and other savings.
I struggle to see how superannuation providers can provide wholistic advice in this area even with some form of limited licencing.
Make the system simpler. Remove the useless hoops people have to jump through. Give people access to enough basic information etc to make informed choices. Allow those that do need to get more complex advice the ability to do it cost effectively.
I am a financial planner and if I could provide advice the same way accountants, lawyers and doctors do it would cost a lot less and I could see a lot more clients.

Anne
August 04, 2024

Chris, couldn’t agree more. I’d love to be able to go and see my financial adviser with a simple question and pay a reasonable fee, but instead I have a conversation that goes round in circles and says nothing unless I take out a specific SOA which takes time and larger amounts of money. It slows down the whole process and makes one think twice about visiting. Retirees, particularly new ones, have frequent questions and can probably make up their own minds to some degree, after getting the facts.

john
August 04, 2024

Understanding whether or not you can access the age pension, the assets, incomes tests and so on is not difficult. Anyone can do it with some straightforward minimal research.
If you disagree, explain where the difficulties are in proper detail.

Matthew Bull
August 05, 2024

Where are the difficulties?

* What are the rules if you have spent time living / working overseas?
* What happens to superannuation if you have one spouse under age pension age, whilst the other is of age pension age, and one is in accumulation whilst the other is not?
* What is the situation if you have income from employment that is sporadic and periodic in nature, but is in excess of the Work Bonus?
* What are your entitltlements if you have a partner but do not share financial arrangements?

I could go on.............

Geoff Warren
August 05, 2024

We agree with most of what is being said around this post. The licensing regime idea is not intended to fix the issues being raised, though.

Michael Skully
August 04, 2024

Another gap in the retirement market seems to be advice on retirement itself. Superfunds can cover the financial aspects, but there are other matters to be consider. The choice of retirement homes for indepedent living versus nursing homes is an area where some body might offer advice. The mental and social change from full time work to full time retirement is another area where people could benefit from advice.

Geoff Warren
August 05, 2024

Also agree with your points about there being gaps these areas, Michael, but again this is not what the retirement licensing idea is intended to address.


Leave a Comment:

RELATED ARTICLES

Reader Survey on retirement income

How retirees might find a retirement solution in future

Leading superannuation members to the Promised Land

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.