As a Financial Planner and SMSF Specialist Advisor with over two decades helping families take control of their super, I’ve seen it all. Every week I speak to people who’ve been approached about setting up a Self-Managed Super Fund (SMSF). Some of those approaches are genuine, but many are not.
Too often, what looks like helpful advice is really a cleverly disguised sales pitch — designed to get you to move your super so the promoter can sell you their product, charge high fees, or worse, put your retirement savings at risk. The ATO is watching this space more closely than ever, and the consequences for getting it wrong as a trustee are serious and personal.
Consider this your no-nonsense guide before you sign anything.
How are you being approached? Sales pitch or genuine advice?
Legitimate SMSF advice starts with your situation — not the adviser’s product. A proper adviser asks about your retirement goals, risk tolerance, existing super balance, insurance needs, available time, and whether an SMSF even makes sense for your circumstances before making a recommendation.
The product-led approach works the other way around. The SMSF is not the goal; it is simply the vehicle. Someone wants to sell you a property, a managed fund, an unlisted investment, or a crypto platform. The SMSF is simply how they access your superannuation balance.
Warning signs
- Unsolicited contact — cold calls, emails, social media ads, or “free seminars” promising to “unlock the power of your super”.
- Pressure to act fast — “limited time offer”, “EOFY special”, or “get your money out before the rules change”.
- Focus on a single product — a specific property deal, crypto scheme, or investment the promoter (or their related parties) controls.
If the conversation quickly moves to rolling your super into a new SMSF so they can “invest it for you” or “help you buy that investment property” — stop. That is usually the gateway to selling their product, not acting in your best interests.
Do they provide genuine education — or just hype?
Real SMSF education explains the responsibilities, not just the glamour. Any adviser worth trusting will make sure you understand what you are signing up for before you commit to anything.
Any adviser recommending an SMSF should explain your ongoing responsibilities as trustee, including compliance obligations, annual audits, record-keeping requirements and your personal liability for breaches. If those issues are glossed over, you're not receiving balanced advice. You're being sold the benefits while the obligations and risks are quietly ignored.
The true costs of running an SMSF
The cost of running an SMSF is one of the most consistently misrepresented aspects of the whole conversation — and for many people at lower balances, it is the deciding factor.
What you should expect to pay
Setup costs: Expect $1,400–$2,000 for a proper trust deed, corporate trustee structure, ATO registration, and an initial investment strategy. Cheap setups often cut corners on documentation that you may regret later.
Ongoing costs: Based on the latest ATO statistical data, median annual operating expenses range from approximately $4,139–$4,628 per year. This includes auditor fees, accounting, administration, and the supervisory levy.
Many people are shocked to learn the real annual cost often lands between $3,500 and $6,000 once everything is factored in — before investment fees, platform costs, or adviser fees.
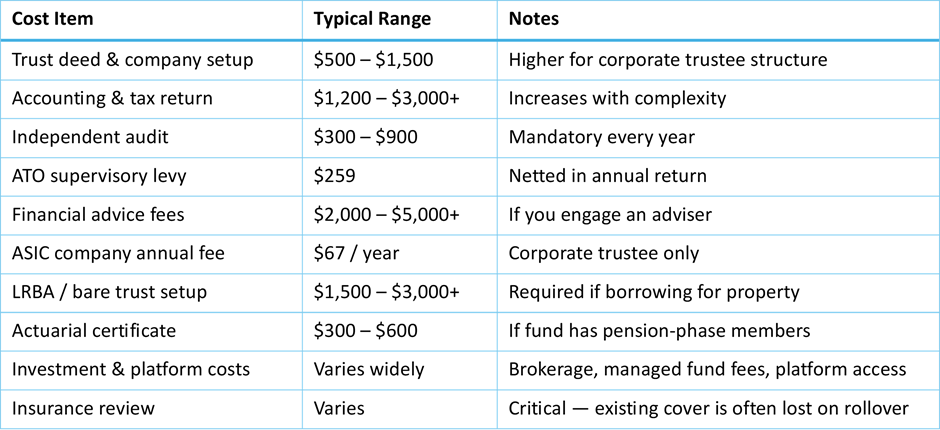
The old ASIC figure of $13,900 per year was significantly overstated, but the ATO’s median numbers are the ones you should use as your benchmark. If your balance is under $500,000–$750,000, those fixed costs can seriously erode your returns when expressed as a percentage of your balance.
Another red flag is if costs have not been fully and transparently disclosed. Say you have only been quoted setup costs, not ongoing annual running costs. No comparison has been provided between the SMSF and your current fund as a percentage of your balance. No one has mentioned that ATO administrative penalties are personally payable by trustees — not from the fund. Insurance implications of rolling out of your current fund have not been raised.
My tip: Before you proceed, demand written fee disclosure.
- Total fees expressed in dollars AND as a percentage of your fund balance.
- A side-by-side comparison between the SMSF and your current super fund, after all fees and tax.
- Full disclosure of any referral fees, commissions or benefits the adviser or their network receives.
- Confirmation that ATO administrative penalties are your personal liability — not payable from fund assets.
The most common mistakes — and what the ATO does about them
The ATO regulates more than 630,000 SMSFs and its compliance data makes uncomfortable reading. Contraventions increased by 10% in the 2024 income year, and by a further 13% in the first half of the following year. Here are the traps that catch trustees out most often.
- Illegal early access — setting up an SMSF specifically to withdraw funds before you meet a condition of release (generally age 60 upon retirement, or age 65 regardless). This is the ATO’s single biggest compliance focus.
- Lending to yourself or related parties — or using SMSF assets to support a struggling business. The ATO’s estimate of prohibited loans this year is $231.7 million.
- In-house asset breaches — investing more than 5% of the fund’s assets in related-party assets or loans.
- Poor record-keeping and valuations — no market-value asset valuations at 30 June, missing trustee minutes, or unsigned trustee declarations.
- No investment strategy — or a strategy that does not match your actual investments.
- Mixing personal and fund money — paying private bills from the SMSF bank account, or depositing SMSF income into a personal account.
- Contribution cap breaches and NALI — non-arm’s length transactions that trigger punitive tax at the highest marginal rate.
- Ignoring ATO authority notices — including excess contribution determinations and commutation authorities. Not responding does not make them disappear.
- Non-lodgement of annual returns — approximately 85,000 SMSFs had not lodged their 2023 return as at early 2025. Non-lodgement removes your complying status from Super Fund Lookup, cutting off employer contributions and rollovers.
The cost of getting it wrong
Administrative penalties can reach 60 penalty units — currently around $18,780 per breach, per trustee. Loss of complying fund status can result in severe tax consequences, including taxation at the highest marginal tax rate instead of 15%. Trustee disqualification goes on the public record and applies to all future SMSF roles. These penalties are paid personally by trustees — not from the fund.
An ATO case that should make you think twice
The ATO does not just issue warnings — it acts. The following court and tribunal decisions illustrate what happens when things go wrong.
NSW Promoter — Federal Court Penalty
One of the most striking enforcement actions involved a NSW promoter who set up (or attempted to set up) 35 SMSFs for 68 individuals. She charged fees to help people who were not eligible to access their super to roll it into a new SMSF and withdraw it immediately — often the same day — for home renovations, stamp duty and personal expenses. The Federal Court imposed a $220,000 penalty and banned her from setting up SMSFs for seven years. The individuals involved were also exposed to back-taxes, penalties and trustee disqualification.
My final coaching advice
An SMSF is a genuinely powerful tool but only when it is the right fit and set up properly. The key question is always: who is this arrangement actually serving?
Before you say yes: your pre-commitment checklist
- Ask yourself honestly: is this person acting in my best interests, or theirs?
- Demand clear, written disclosure of all fees and ongoing costs — in dollars, not just percentages.
- Insist on a Statement of Advice (SOA) that documents why an SMSF is recommended for your specific situation.
- Insist on proper education about your trustee responsibilities before you sign anything.
- Check every licence on the ASIC Financial Advisers Register and the Tax Practitioners Board.
- Get a second opinion from an independent SMSF Specialist Adviser who has no connection to the product being recommended.
- Confirm your existing insurance coverage position before rolling out of your current fund.
- If anyone promises access to your super now for a non-retirement purpose — stop. It is illegal and a major ATO compliance focus.
An SMSF done right is one of the best structures available for building retirement wealth. An SMSF done wrong — for the wrong reasons, promoted by the wrong people — can cost you your retirement savings, your trustee status, and years of financial recovery.
Key takeaways
- An SMSF is right for the right person — but the approach, the advice, and the cost disclosure must all check out first.
- If someone approached you unsolicited and led with a product, the starting position is one of conflict of interest.
- Understand the full annual cost (typically $3,500–$6,000+) and compare it to your current fund before deciding.
- Always verify licences, demand a written SOA, and get an independent second opinion.
- The ATO will find non-compliance. Trustees cannot hide behind their accountant or adviser. They remain legally responsible for their SMSF, regardless of who recommended the strategy, completed the paperwork, or manages the administration.
This article is an adapted version of an original blog post that can be found here.
Liam Shorte is a specialist SMSF adviser and Director of SONAS Wealth. He is also a Director of the SMSF Association and he writes under the social media identity of 'The SMSF Coach'. If you’d like a no-obligation conversation about whether an SMSF is right for your situation — or you want a straight-talking second opinion on an offer you’ve received — reach out.
General Advice Disclaimer: This article is general information only and does not constitute personal financial, legal or tax advice. The rules governing SMSFs are complex and individual circumstances vary significantly. You should obtain advice from a licensed financial adviser before acting on anything in this article. The author holds AFSL authorisation through Sonas Wealth Pty Ltd, corporate authorised representative of Viridian Advisory 476223.