In "Are Active Managers Bringing a Knife to a Gunfight?" I argued that the rise of passive investing has handed price-setting to sophisticated systematic players, and that discretionary active managers must evolve. Markets are not the only place this has happened. Professional basketball, Formula 1 and chess were all reshaped by data over the past two decades, and each has something to teach active managers facing the same shift.
The NBA: asymmetric mathematics
For decades, shot selection was a matter of feel. Guards and forwards worked the mid-range, the zone between the key and the three-point line, taking jump shots based on spacing and personal comfort. Camera-tracking technology ended that. Once analysts could calculate the expected value of every square foot of the floor, the mid-range jump shot was the least efficient play in the sport.
Kirk Goldsberry's shot charts capture the shift. Map the league's top 300 shot locations in 2003-04 and the mid-range is dense with activity. Map the same thing in 2023-24 and it has been hollowed out. The volume migrated to two zones: at the rim, and behind the arc.
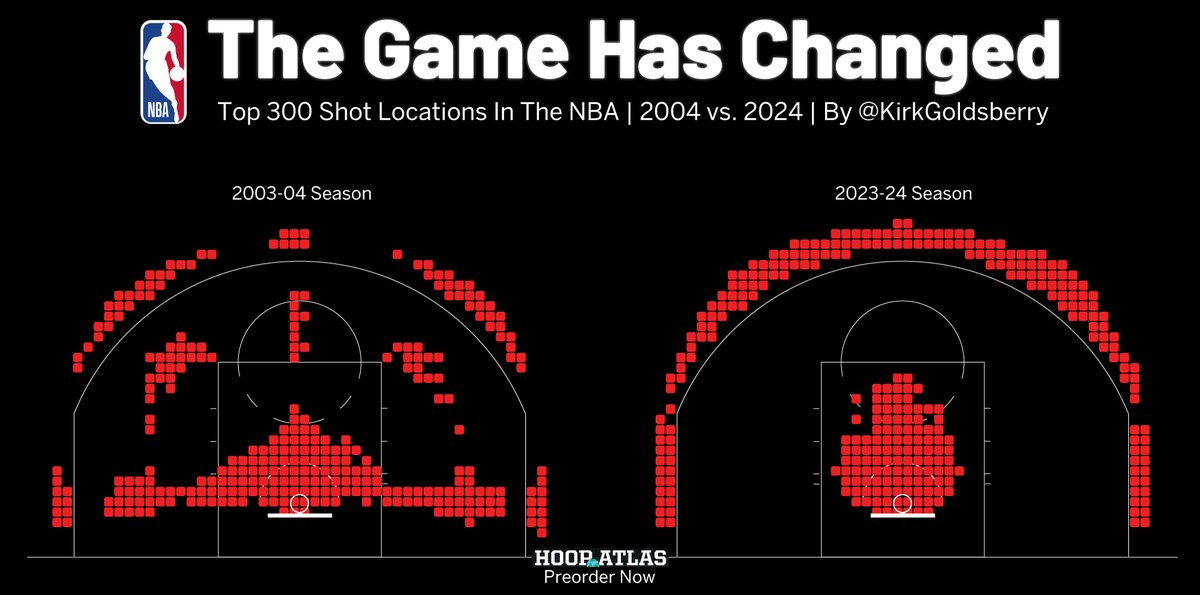
Source: @kirkgoldsberry
The two zones win for different reasons, and the mid-range loses on both counts. Using recent league averages, the maths is revealing:
- At the rim, shooters convert around 66%. Two points a time, that is 1.32 points per shot (66% x 2).
- From mid-range, accuracy falls to about 41%. Still two points, so 0.82 points per shot (41% x 2).
- Behind the arc, accuracy drops further to roughly 36%. But the shot pays three, lifting the return to 1.08 points per shot (36% x 3).
The mid-range sits between the other two on the floor but finishes behind both on the maths. The rim wins on accuracy, the arc wins on payout, and the shot in the middle wins on neither. A lower accuracy shot can still be the better shot if it pays enough, which is the logic the hedge fund manager Paul Tudor Jones built a career on.
"Five to one means I'm risking one dollar to make five. What five to one does is allow you to have a hit ratio of 20%. I can actually be a complete imbecile. I can be wrong 80% of the time, and I'm still not going to lose."
- Paul Tudor Jones
This is the first lesson. Being right more often is not what separates the best. Citadel is one of the most successful hedge funds ever built, yet its top portfolio managers are correct only 54% of the time. Accuracy is not what sets them apart. Position sizing and portfolio construction turn a hit rate slightly above 50% into strong, consistent returns.
Formula 1: the infrastructure behind the driver
If basketball shows what an optimised strategy looks like, Formula 1 shows the infrastructure required to execute one.
An F1 driver is the ultimate discretionary manager, turning the wheel and managing risk in real time. But the driver does not operate on intuition. He sits at the tip of a computing ecosystem. Before a race weekend, simulation engines run millions of permutations across tyre degradation, track temperature, fuel weight and safety car probability, mapping the physical limits of the car.
During the race, hundreds of sensors feed telemetry to a pit wall that resembles mission control. The driver does not change tyres on a hunch about the asphalt. He receives an instruction because a model just recalculated the optimal pit window against live competitor data.
The pit stop itself makes the point. Through the 1990s and 2000s a stop took eight to ten seconds, most of it spent pumping fuel. When refuelling was banned in 2010, the tyre change became the only variable, and the entire engineering effort turned to shaving it. Times fell to around three seconds within a year, and the record now stands at 1.80 seconds, set by McLaren at the 2023 Qatar Grand Prix. That was not achieved by telling mechanics to move faster. It was unlocked by embedding sensors in the wheel guns, feeding an automated system that triggers the green release light the millisecond the job is mathematically complete. The modern pit stop is a software loop executed by human hands.
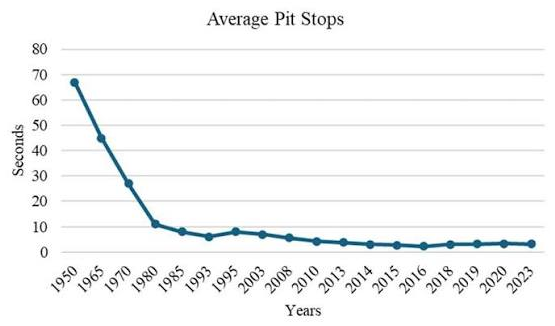
Source: L. Belkovics, K. András and I. Takács, "The Technological Innovation of Pit Stops in Formula 1," 2024 IEEE 22nd Jubilee International Symposium on Intelligent Systems and Informatics (SISY), Pula, Croatia, 2024, pp. 101-106.
Markets have run the same compression. A result used to reprice over days while analysts interpreted it. Now the systematic players read the announcement and reprice the stock before a fundamental manager has finished the first page. The reaction has become its own software loop, run at machine speed.
This is the second lesson. The pit crew did not get faster by trying harder. They got faster by measuring the task and stripping out everything a machine could do better. The same is true in markets: you cannot out-react a machine, so the edge moves upstream, to understanding the forces acting on a price before the catalyst hits and surviving the move when it comes. Reading how earnings drive company value is only one of those forces. Understanding the others requires quantitative machinery that can stress test a portfolio across environments, the way an F1 car is simulated across weather conditions. Navigating machine-driven factor rotations on intuition alone is driving in the wet without radar.
The rise of the centaur
Basketball showed a strategy solved by maths, and Formula 1 the machinery to execute it. Chess put a name to what both were really doing: combining human and machine. In 1997, world champion Garry Kasparov lost a match to IBM's Deep Blue supercomputer. Everyone took it as proof the machine had won. Kasparov asked a different question. If a machine could beat the best human alive, what could a human and machine do together? The pairing became known as a centaur, half human, half machine.
The proof came at the 2005 PAL/CSS Freestyle tournament, where two amateur Americans running three ordinary computers beat both grandmasters with supercomputers and the machines alone. The winning ingredient was neither the strongest human nor the strongest machine, but the best process for combining them. Chess has since moved past this. The engines no longer need humans, because chess is a closed, unchanging system. Its rules are fixed, so a machine that has mastered it never falls behind. Markets are not. What worked last year may stop working this year. Regimes turn over, and the model tuned to the last environment is the most exposed to the next. The judgment never fully transfers to the machine.
That is the choice active managers face. The apex predators are already centaurs, human oversight wired to systematic machines. The manager who still runs on fundamental research alone is the last standalone grandmaster in the room. Survival does not mean out-computing the predators. It means keeping the one edge they lack, deep conviction on individual businesses, and wiring it to enough systematic risk infrastructure to stop being run over by the forces they set in motion.
The reverse is also true. Even the purest machine still answers to a human. Renaissance is the most successful quant fund ever built. When its models bled 20% in three days during the 2007 Quant Quake, Jim Simons considered pulling the plug. The firm had to decide: let the models run or override them and cut risk. They let them run, and Medallion finished the year up around 85%. Even at the apex of quantitative sophistication, the machine could measure the loss but not decide what it meant. That call belonged to a human.
Adapting to the modern arena
The mid-range shooter and the refuelling-era pit crew have one thing in common. They no longer exist. Once an arena has been mapped and quantified, there is no going back, and the competitors who refused to adapt disappeared with them.
Survival does not belong to the manager who tries to out-calculate the machines, nor to the one who trusts them blindly. It belongs to the centaur: fundamental conviction wired to systematic risk and factor infrastructure, with the judgment to know when the model has stopped describing the world. Stephen Curry still has to shoot. Lewis Hamilton still has to drive. Jim Simons still had to decide when to trust the machine. A model is built for one world, and it cannot tell you the moment that world has changed. That judgment is the one thing the machine cannot hand back.
To bring a gun to the gunfight, you must let the data build the weapon and keep a human to aim it.
Jason Teh is the founder and Chief Investment Officer of Vertium Asset Management; and a Portfolio Manager at Clime Investment Management Limited, a sponsor of Firstlinks. This article is general in nature and does not constitute or convey personal financial advice. It has been prepared without consideration of anyone’s financial situation, needs, or financial objectives. Before acting on the areas discussed and contained herein, you should consider whether it is appropriate for you and whether you need to seek professional advice.
For more articles and papers from Clime, click here.