Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 486

Hold fire on your fund manager over short-term declines

Who hasn’t wanted to be Biff Tannen in the 1980s cult classic movie, Back to the Future Part II?

As an old man in 2015, Biff discovers Grays Sports Almanac. It shows the outcome of every sporting event from 1950 to 2000. Biff hops in the DeLorean time machine and travels back to 1955. He gives the magazine to his young self. Young Biff places bets on sporting events listed in the Almanac. He quickly builds his evil financial empire from the guaranteed profits.

This doomsday timeline is only extinguished by Marty McFly and Doc going back in time to steal the Almanac from Young Biff, masterfully aided by Marty’s hoverboard from the future. (An aside: thanks Mattel for not delivering on that promised future tech by 2015!). Marty then eventually burns the Almanac, much to the collective sigh of sports betting fans everywhere.

An investor’s dream

What if you had an Almanac for the share market?

That’s what US based investment group Alpha Architect took a look at a few years ago. In their study, they looked at the question: “What if you had perfect (God-like) foresight and knew exactly which stocks would be the best and worst performers over the next 5 years?”.

Their conclusion: Even God would get fired as an active investor.

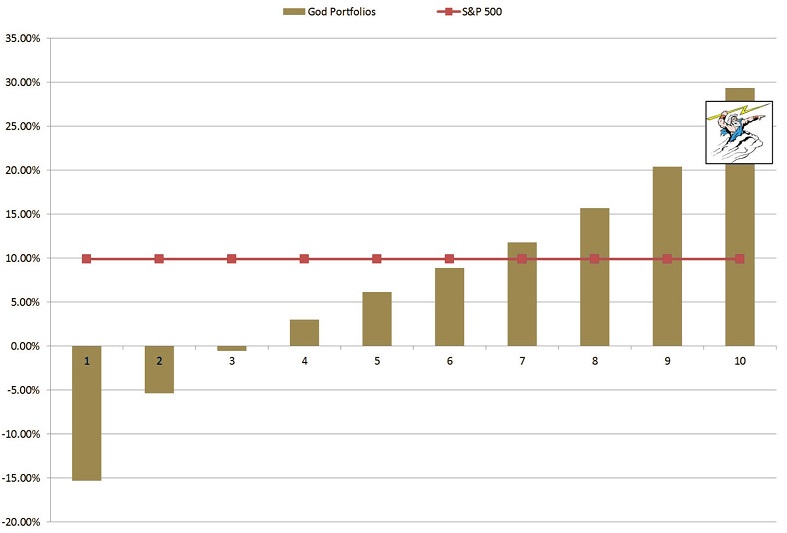
CAGR by ranking decile (1927 to 2016)
Source: Alpha Architect.

The chart above shows the outcome of having God-like skills and investing in the top-performing 10% of US stocks over every 5-year period since 1927. In terms of performance, you would have knocked it out of the park, returning just shy of 30% per annum. Eat your heart out Warren Buffett.

Dramatic drawdowns

But there is a catch.

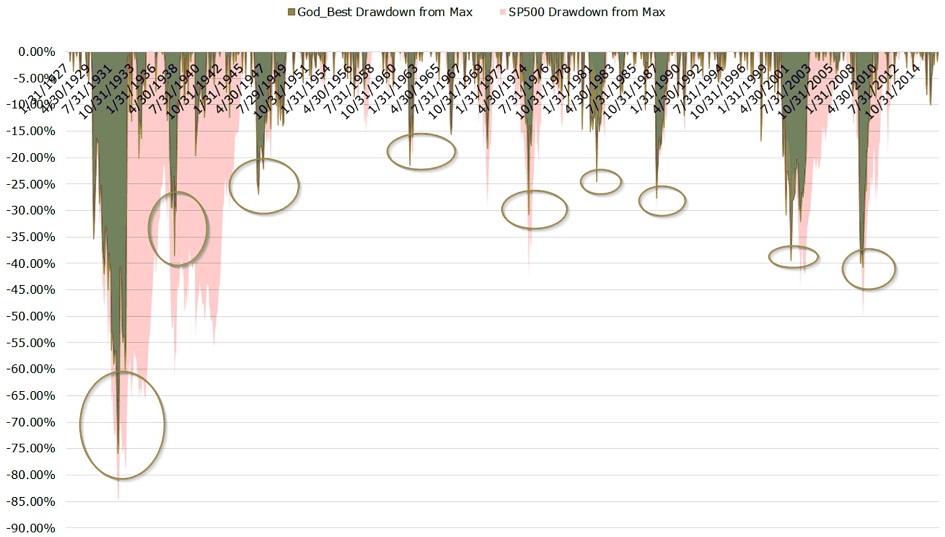
As you can see in the chart below, to get that 30% per annum return, investors in the hypothetical ‘perfect’ long-term active share fund would have suffered extreme gut-wrenching drawdowns (peak-to-trough falls).
Source: Alpha Architect.

Between 1929 and 1932, the fund would have lost nearly 76% of its value before staging a recovery. Drawdowns of -20% to -40% were routine, including 40% falls during the GFC and the 2000’s tech-wreck.

How does this happen? Because even the best stocks don’t go up in a straight line over the long term. The share market is a volatile place, even if God is picking the stocks.

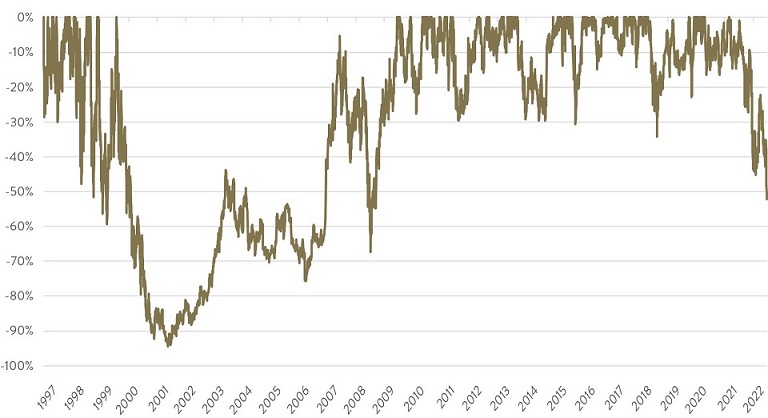
The spectacular success story of Amazon is a prime example. It has returned over +119,873%, or over 32% per annum, since listing in 1997. Yet its share price fell 94% in 2001. It took 10 years to recoup that loss. During that decade, it suffered falls of 45% in 2005, 63% in 2008, and also fell 34% in 2018. It is currently down 52%.

The lesson is that even if you possess godlike skills, you can’t avoid big drawdowns.

Amazon share price drawdown
Source: Factset

The danger of focusing on short-term fund manager performance

This has serious implications for how investors judge performance. High-performing active fund managers don’t post strong returns or outperformance day in, day out. Or even year in, year out. They suffer drawdowns and periods of underperformance.

Investors, therefore, need to back the long-term track record of their fund manager through the shorter-term volatility. If they don’t, they risk jumping from manager to manager and missing the inevitable rebound from skilful managers – and long-term outperformance.

(For our suggestions of what to look for in a fund manager instead, please read our Investment Strategy notes on the topic here and here.)

Myopic investors can drive fund managers to focus short term

If enough investors pull their money when short performance falls, they are ultimately incentivising the fund manager to focus on short-term performance too.

Most share funds disclose that the minimum investment time horizon for their fund is 5+ years. Industry investor funds flow data, however, suggests many investors don’t wait around that long for a fund manager to recover if they are suffering a significant drawdown. In that scenario, even some of the top performing fund managers can be fired. The natural consequence is managers are focussed on the short term and ensuring portfolio company results keep beating short-term expectations.

Shares, however, are a long-term asset class. They benefit from the ingenuity of businesses in raising productivity, creating new products or services, or improving existing ones. This takes time, often at least 3-5 years.

This has led to CEOs the world over lamenting how fund managers are so intently focussed on the next quarterly result, whilst they are generally focussed on setting and implementing business strategy for the next 3-5+ years. We have seen this too, many times over the years. Our response is unless investors’ time horizons become longer in their decision making, then fund managers are unlikely to focus more exclusively on the long term too.

Why investors need to understand their fund’s investment horizons

As we have seen, even a fund manager with perfect ‘God-like’ foresight would suffer major short-term falls. Investors need to accept the best-performing funds over the long-term can also post significant drawdowns.

It is terribly damaging for fund managers if lots of investors redeem during tough times. This is magnified for small caps. Fund managers have to sell less-liquid companies at fire sale prices to fund these investor withdrawals.

Sometimes, of course, investors are justified in withdrawing their capital. But short-term declines shouldn’t be one of those reasons.

Investors need to understand the investment horizon for the fund, and ensure they are aligned with that horizon. Long-term investors are one of the most valuable assets a fund manager can possess. At Ophir, we deeply value ours.


Andrew Mitchell is Director and Senior Portfolio Manager at Ophir Asset Management, a sponsor of Firstlinks. This article is general information and does not consider the circumstances of any investor.

Read more articles and papers from Ophir here.


  •   30 November 2022
  • 5
  •      
  •   
5 Comments
Graham Wright
November 30, 2022

The perpetual argument with another set of supporting data to show that long, long term investing will be profitable. An argument well established to support fund-managers and other professional "administration types" living off the investment industry with no care for the possible alternative needs of the investor.
The investor has only one factor within his/her control re the investment: 1) remain invested and take the consequences good or bad, 2) withdraw the invested funds and preserve the capital from deterioration that he/she expects could occur if the investment continues. If you have no control, you are relying on faith.
The investor has one further consideration. "If I lose any or all of the investment funds, am I losing funds I will need for my future living and will I have time and opportunity to recover the funds by the time I need them?
The investors self needs prevail over those of the fund needs as far as the investor must be concerned.
Finally, there is a weighted factor available to many fund managers, to protect the fund and that is the ability to close the fund to withdrawals, beneficial to the fund but detrimental, sometimes seriously detrimental to retiree investors. Thus the fund manager is far better self-protected than the investor.

michael
November 30, 2022

Surely god would have the ability to go to cash, since god knows what is going to happen.

Dazza
December 02, 2022

More and more research highlights that active fund managers underperform their benchmarks over the long-term and as a result investors are turning to lower cost ETFs and other passive investments. As a result we continue to see fund managers trying to justify their existence in defensive articles such as this. Unless they radically re-think their business model their days are numbered.

Peter Voight
December 02, 2022

There seems to be some cynicism towards fund managers among the comments. For balance, I think that while it's correct that most fund managers do underperform the index, there are some who can outperform over long-term periods. For example, recent data from S&P Dow Jones Indices shows that for Australian mid and small caps managers, 47% outperformed over a 3 year period, 40% over a 5 year period and 49% over a 15 year period. Consistent outperformance can happen and there are some good managers out there if you do your homework.

Graham Wright
December 03, 2022

LICs can easily demonstrate the situation in this current economic environment, re fundmanager's best interests and investor best interest and the principle extrapolates into all fund environments. Easily visible watching monthly statements of NTA and shareprice movements.
NTAs are generally trending downwards at the moment due to investment values falling as a generalisation. At the same time shareprices of LICs are falling as a generalisation. If both moved relative to each other the gap would remain the same. This gap consistency remains relatively constant with unlisted funds/trusts/etfs because managers contrive to maintain the gap consistency. With LICs, there is no market price control, just market free forces so that investors can walk away faster or buy in quicker than NTA changes as is their whim. The gap shows the difference between investor expectations and the fund managers expectations/expertise.
In today's market, outperformance means the fundmanagers investment selections are losing less than the goalpost performance. A wonderful claim, "I'm good because I am not as bad as the rest". For the investor, any loss could mean unpaid bills, sold (other) assets, changed education arrangements for kids. Fund managers can protect their fund by changing investments without telling the investor instantly that the change occurs and they can close the fund to withdrawals. The investor can only follow the manager blindly and faithfully or withdraw from the fund. Today, in LICs, we see investors selling with prices falling and the gap widening in most instances. Of course there are always a few exceptions to every circumstance.


Leave a Comment:

RELATED ARTICLES

Bigger fall, bigger bounce: small caps into and out of recessions

Bear markets don't go paw-in-paw with recessions

7 truths of volatility, but are they friends or foes?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.