The economic outlook is uncertain for all sectors of the market with rising interest rates and still high inflation. Equity markets have been volatile and come sharply off highs reached earlier this year and late last year. Small companies have not been immune and have been beaten up badly, which is often the case with market drawdowns.
Inflation does appear to be peaking but the actions of central banks around the world will depend largely on what kind of trajectory that reduction in inflation follows. The rhetoric coming from the US Federal Reserve suggests that they're not done hiking yet. And the Reserve Bank of Australia appears to be of much the same view.
The big question is 'how high will rates go and how long will they stay there?' At the moment, we're not seeing much of an impact of tighter monetary policy within some of the consumer facing sectors in the domestic economy. But it certainly feels like there is more pressure emerging in some of the other developed markets, such as the United States, where rates have gone up faster and in larger increments, and where cost-of-living pressures have been bigger.
Why small companies?
What attracts us to the small company sector is that if you are able to identify the right ones, you can get the benefits of above average earnings growth early in a company's growth phase along with possible re-rating benefits as markets become more aware of the potential of the company.
Because of this, a bottom-up investment process is important when it comes to small companies. An important stage in our investment process is the company visit. It complements our analysis of a company and the sector that it operates in, along with research of its competitors and suppliers. That analysis will have led to the belief that there is an investment opportunity. So, when we visit a company, we are trying to ascertain whether the management team and the board can deliver the outcomes that we believe are possible based on our prior analysis.
COVID-19 obviously impinged on our ability to physically visit companies but not on our ability to interact with company management, as video calls were a reasonable substitute. Physical interaction will usually lead to a much better discourse and understanding of a company, but there were some benefits to video calls as they facilitated a larger number of meetings with companies.
What sectors?
There are parts of the small cap market that have seen more material drawdowns, which are now starting to pique our interest. We put tech, consumer discretionary and building materials into these categories.
Although consumers may still be yet to feel all of the impacts of rising interest rates - as monetary policy is a lagging indicator – an important difference this time around is that balance sheets were in a pretty good position going into the downturn. Many people were able to get ahead during the pandemic and associated lockdowns as they couldn’t spend on discretionary items, such as holidays, and thus have some buffer in their budgets for the impact of higher interest rates.
Consumer discretionary make up a big chunk of the S&P/ASX Small Ordinaries Accumulation Index and we were slightly overweight the sector in October in anticipation of good quality companies with strong cost management practices being able to outperform.
Other themes we like in small caps, which are persistent across the whole market, are the long-term themes attached to energy transition and the increasingly short supply of some metals.
We believe the demand for metals - as a result of the electrification of many aspects of society is going to require - has been vastly underestimated. The companies which foresaw this and eked out opportunities for themselves are of particular interest to us.
Small cap winners
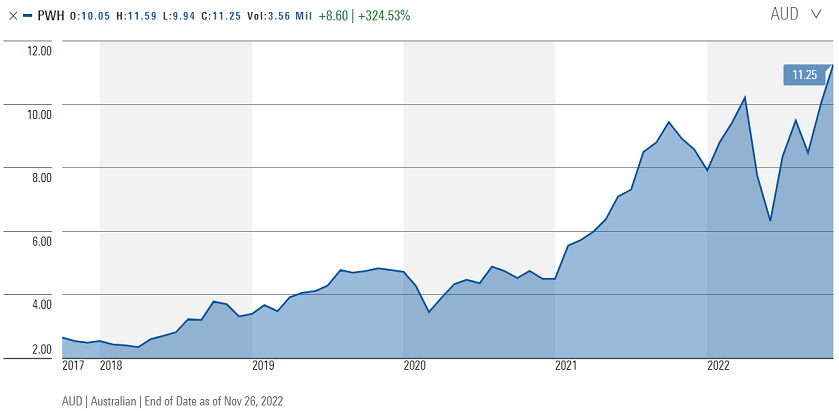
PWR Holdings Ltd (ASX:PWH)
PWR Holdings listed in 2015 and although we've not traditionally invested in too many IPOs we believed that this was a high quality business with entrepreneurial founders that led with reasonable skin in the game. We accepted that they genuinely wanted to raise money to keep growing the business.
Source: Morningstar
Originally PWR Holdings was an Australian-based radiator manufacturer, but they were able to pivot their intellectual property (IP) into advanced cooling technology that is used in cooling high performance engines in areas such as motorsport. They have continually been able to use the IP within their business to keep expanding into adjacent markets, and that has led to a very strong compound annual growth rate (CAGR) of about 25% in the nine years since it's been listed.
They been able to grow the business without jeopardising the returns that they're earning, and that is a very strong formula for market outperformance. PWR has seen a fair re-rating since it first listed and while it does trade at a 35% premium to the S&P500 aero and defence index, we feel this is justified given materially higher growth and superior returns on invested capital.
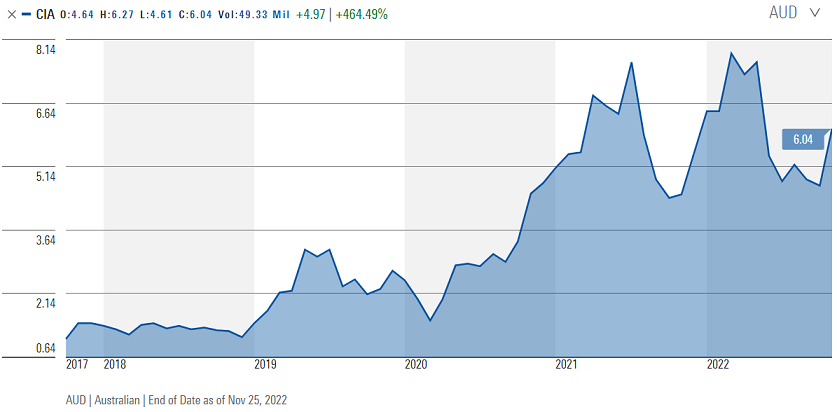
Champion Iron Ltd (ASX:CIA)
Champion Iron is another founder-led story. Back in 2016 Champion bought a high-grade iron ore mine out of administration in Quebec, Canada. A large portion of capital had been already sunk into the mine and its infrastructure, and with some incremental investment it was able to bring the mine back into production.
Source: Morningstar
That investment paid off and they are now mining high grade iron ore and looking to play into the area of 'green steel'. They are providing high grade ingredients that can help reduce emissions in blast furnaces, or which can be used as a product that's used in electric arc furnaces.
Champion understands that as steel produces approximately 7-8% of global carbon emissions, iron miners that want to continue to exist as the energy transition progresses, need to part of the decarbonisation of the steel production process.
When Champion Iron's Bloom Lake site was recommissioned in 2018 its emissions were reduced by 40%, and 65% of the company's energy consumption is supplied by renewable hydroelectric generation.
Renewable energy use also offers the company a real competitive advantage as it takes a lot of power to convert high-grade iron ore into direct reduced iron and pelletize it. It is essentially pure iron that can go into blast furnaces.
Champion also now has a long mine life and relative to other global green steel producers has a bottom quartile cost of production. But it's being put in the same boat as some of the majors - the BHPs and Rios - when it comes to valuations whereas we believe it should be trading at a material premium.
Champion is one of those commodity businesses with very attractive attributes that should be able to withstand some of the volatility underlying commodity prices.
The payoff
Smaller companies do of course come with higher risk. For every Champion or PWR Holding there are dozens of failures. But if you can be astute in your investment process and conduct a thorough analysis of a company, which may involve looking beyond its market valuation, it is possible to find the next Australian small company star.
Simon Brown is a Portfolio Manager at Tribeca Investment Partners. Tribeca is a specialist investment manager partner of GSFM Funds Management, a sponsor of Firstlinks. Tribeca may have holdings in the companies mentioned in this article. This information is general in nature and has been prepared without taking account of the objectives, financial situation or needs of individuals.
For more articles and papers from GSFM and partners, click here.