Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 35

Residential investment property fails simple valuation test

The Herengracht Canal in Amsterdam has been a favoured strip of real estate in the city since the 1620s. The Herengracht House Index, constructed by finance professor Piet Eichholz of Maastricht University, tracks house prices in the area over a 380 year period – commencing with the Dutch ‘Golden Age’. Over that time, real (i.e. inflation adjusted) house prices have only doubled, which corresponds to an annual average price increase of something like 0.1%. This would indicate that despite short-term rises and falls, prices roughly follow inflation.

Valuing like other financial assets

What could this mean for investors in the Australian residential property market? It may have looked like an attractive option recently. Auction clearance rates have been healthy, but rising prices have prompted media commentary on a possible housing ‘bubble’. What do we find if we apply value-investing principles?

We’ll start by assuming that residential property, at least the investment kind, derives its value in the same way as other financial assets - by producing cash flows - and obeys the same fundamental financial laws.

Since property income is fairly predictable, the valuation exercise should be straightforward. We just need three numbers:

  • discount rate, or rate of return required by an investor
  • net rental income generated
  • long-term rental growth rate

We can plug these values into a simple formula that will calculate the present value of the cashflows into perpetuity, following the same principles used to value a business.

A discount rate reflects the rate of return an investor needs to compensate them for the risk of investing in a particular asset. A good way to estimate it might be to start with the 10-year government bond rate (a proxy for the rate that applies when there is no risk, currently around 4% p.a.), and add a risk premium.

In the case of equities, the risk premium is commonly thought to be around 5-6%. I think a case can be made for a lower risk premium for property, given that it has a more stable profile, but we should also consider that property is a much less liquid asset than equities, and investors should demand some compensation for this. For the sake of argument, let’s choose a risk premium of 4%. This gives us a required rate of return of around 8%.

Net rental yield is the next piece of information we need. The chart below, published by RP Data, shows a current gross rental yield for Australian capital cities of around 4.3% p.a.
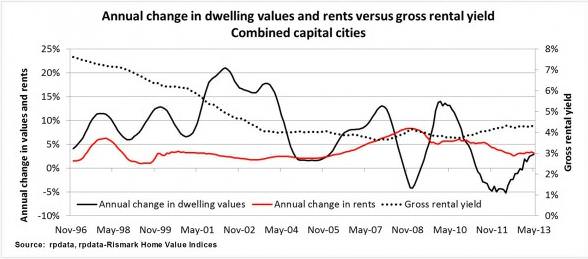
To calculate a net rental yield, subtract all the expenses that an investor must incur in generating the gross rent, including property management fees, maintenance, insurance etc. A reasonable estimate may be around 1.0%, which gets us to a net rental yield of 4.3% - 1.0% = 3.3%.

The final number required is the long term growth rate in rents. As shown in the chart above, a figure just above 3% p.a. may be a reasonable estimate. Let’s assume 3.2%.

Combining these numbers into a valuation can be done as follows: divide the annual rent earned on a property by a divisor, which is calculated by subtracting the long term growth rate from the discount rate, as set out below.

Value = Net Rent p.a. /(Discount Rate – Growth Rate)

This is the formula for calculating the present value of a stream of cash flow that grows at a fixed rate in perpetuity. If a property generates $20,000 per year of net rent, we would calculate its value as $20,000/(8% - 3.2%) or $20,000/4.8%, equal to around $416,667.

If that property can be bought today at a net yield of 3.3%, it would imply that the market price of the property today is $20,000/3.3% = $606,061. This is significantly higher than our valuation of $416,667. On the basis of the discount rate and long term growth rate we assumed, buying property on a net rental yield of 3.3% appears hard to justify.

Continuing assumption of capital growth

Over the past three decades, there has been a fourfold increase in Australia’s indebtedness as a percentage of annual disposable income, to 150%, as well as massive growth in property prices. Together with the above analysis, these facts indicate that the same level of growth is not sustainable. If this is correct, it may pay to be cautious about buying on the basis of a continuation of assumed capital growth.

Of course, the conclusions you reach with this approach depend on the assumptions you put into it, and the purpose here is not to argue that property is overpriced. Rather, it is to set out a framework that allows some basic assumptions to be converted into a fundamental value. By doing this, you can decide for yourself whether there is long term value to be gained.


Roger Montgomery is the Chief Investment Officer at The Montgomery Fund, and author of the bestseller, ‘Value.able'.


  •   11 October 2013
  • 4
  •      
  •   
4 Comments
Steve
October 29, 2013

Dear Roger, Thank you for the article, I very much agree with your 'cash flow' approach, but wondered if the inclusion of a long term interest rate and an assumed level of long term financial gearing would reduce the cost of capital and bridge the valuation gap between intrinsic value and prevailing markets prices?

Roger Montgomery
October 30, 2013

Yes Steve, it might but the objective of a valuation is not to explain or arrive at the current price. We already know what the price is.

We look at valuations as a reference point below which we would be willing buyers.

Sydney
May 24, 2014

Hi Roger,

For some reason I think demand supply dynamics have been missed in your calculations. That's true in equities as well. If there is less free float of a stock then buyers who are interested in those assets must pay a higher price to obtain them. They may also have huge premiums to underlying value. Now how does one calculate what premium can be given to a property is based on ones needs and affordability. By your argument a 2bedroom in north shore should be similar to 2bedroom in western Sydney since cost of actual construction is similar except for council rates etc. which would be a small percentage to the actual cost of property.

I think there is a supply side issue in property markets especially in Sydney. Negative gearing has made it worthwhile for owning properties with low rental yields and till that does not stop property will continue to be the investment choice for Australians.

James
May 26, 2014

Roger,
A very good article. We have the incipient problem in Australia that many country towns, especially mining communities, are destined to become unviable as their population is replaced by automatic, remote-control operations, falling commodity prices (meaning that many mines will continue to operate only to service existing contracts) poor health and education choices (no specialists, long distances to travel for medical and hospital treatment) diminishing community spirit as workers leave in droves on weekends of at completion of fly-in, fly-out arrangements. Many people ave evaluating these choices as against living in expensive cities, even if they have expensive public transport. However, with the escalating cost of fuel, there will be no choice for many but to move to cities. This may appear to be a cause of higher prices in the capital cities, especially Sydney, Melbourne and Brisbane but it is apparent that country property has been declining at an astonishingly fast rate, with banks in general virtually not financing property in country towns unless the purchasers can almost afford to pay cash.


Leave a Comment:

RELATED ARTICLES

'FOMO' is driving residential property prices, not yields

Lending policies can spoil good SMSF strategies

A better approach to post-retirement planning

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.