Glencore's arrival on the ASX gives Australian investors a new choice. Should they stick with BHP and Rio Tinto, or allocate some capital to Glencore (GLC)?
BHP and Rio offer franked dividends, stronger governance credentials and established places in Australian portfolios. Glencore is cheaper, has a trading arm and ambitious copper growth potential. Its Australian listing is designed to help narrow its valuation gap.
Our view is that Glencore deserves consideration, particularly for investors seeking copper exposure and a different source of earnings. But there are good reasons why BHP and Rio shareholders might be better off doing nothing.
How Glencore works
Glencore is one of the world's largest miners and one of its largest commodity traders. That combination makes it different from BHP and Rio. Three features matter most to investors: the trading arm, coal and copper.
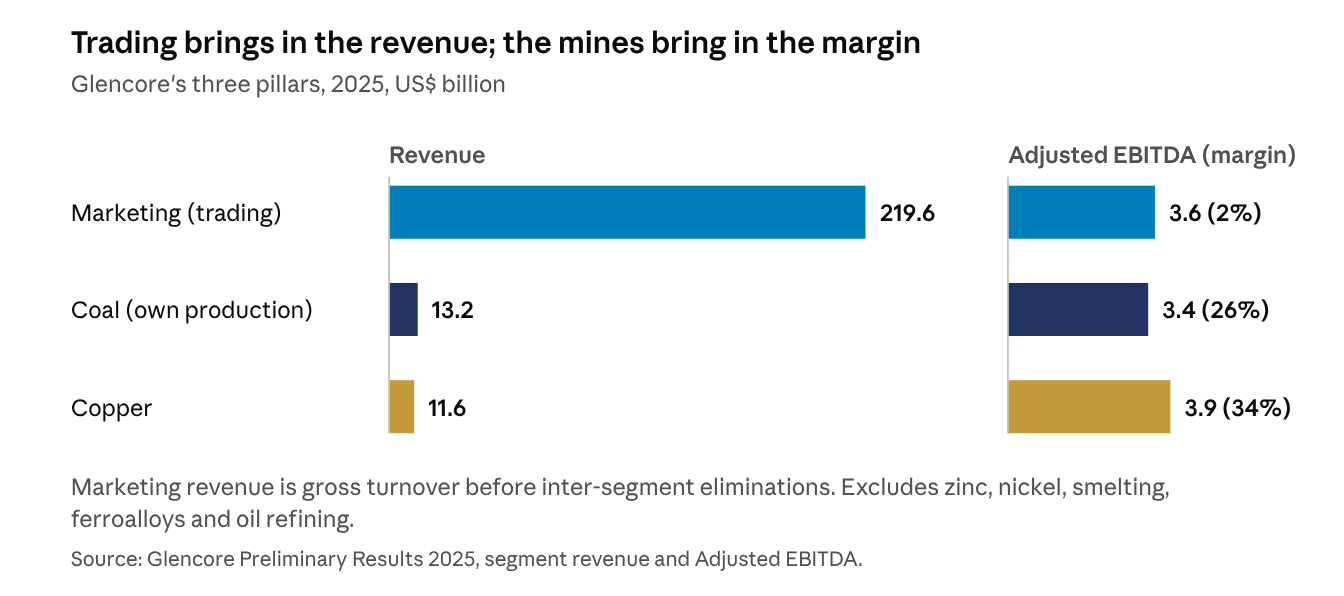
Coal is an important differentiator. Glencore produces both steelmaking coal and thermal coal, which is burned to generate electricity. It plans to keep mining both for decades.
Rio, by contrast, has exited coal entirely. BHP's last thermal mine, Mt Arthur, closes in 2030. Thermal coal is the sticking point: investors must weigh Glencore’s current cash flows against uncertain long-term demand, environmental liabilities and a shrinking pool of investors willing to own it.
Copper is the major attraction. Glencore is already one of the world's largest copper miners and has substantial room to expand. But its third business, marketing, is what really sets it apart.
The trading arm, explained
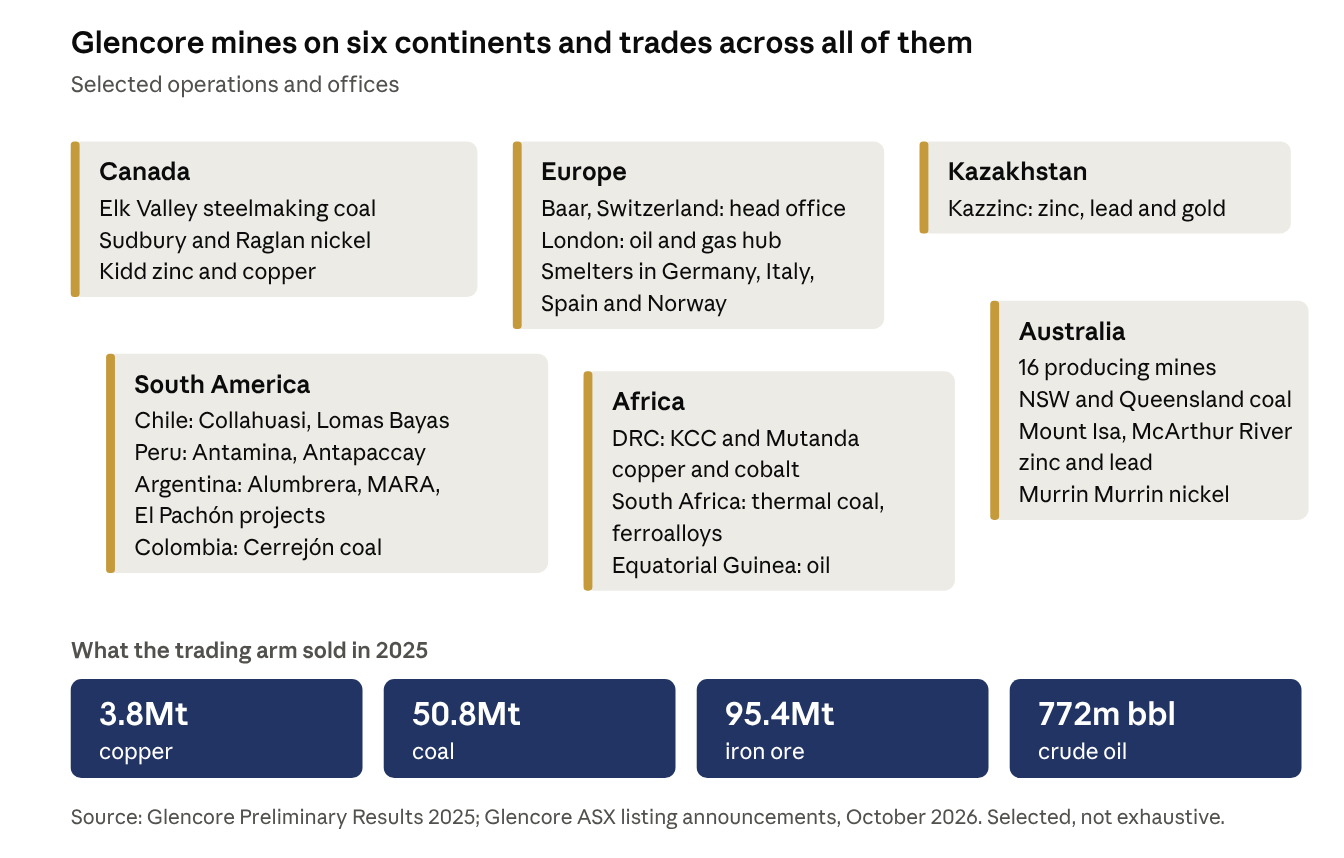
Think of Glencore as the Amazon of bulk commodities. It moved about US$220 billion of metals, coal, oil and other products in 2025, much of it produced by other companies.
In normal markets, trading margins are modest. But when volatility rises – through war, natural disaster, or something else – profits rise sharply.
We’ve seen that this year. Suppose a Singaporean refiner suddenly needed crude oil after a disruption in the Strait of Hormuz. Glencore may have a tanker loaded in West Africa for another customer. It can divert the ship to the Singaporean refiner willing to pay a premium, compensate the original buyer and keep the difference. The trade only works for someone with the cargo, the relationships and the logistical flexibility to act while other buyers scramble.
Operations: Glencore has an edge over BHP and Rio
Trading profits act as a useful shock absorber and give Glencore an earnings stream that BHP and Rio lack.
It is not a perfect hedge, but the type of events that make mining profits fall can also be the ones that make trading profits rise.
Glencore’s trading business also partly explains why we believe Glencore may have an edge in copper – at least over Rio.
Glencore traded around 3.8 million tonnes of copper in 2025. That’s more than four times its own mine output. Its traders bring commercial intelligence about future supply and demand.
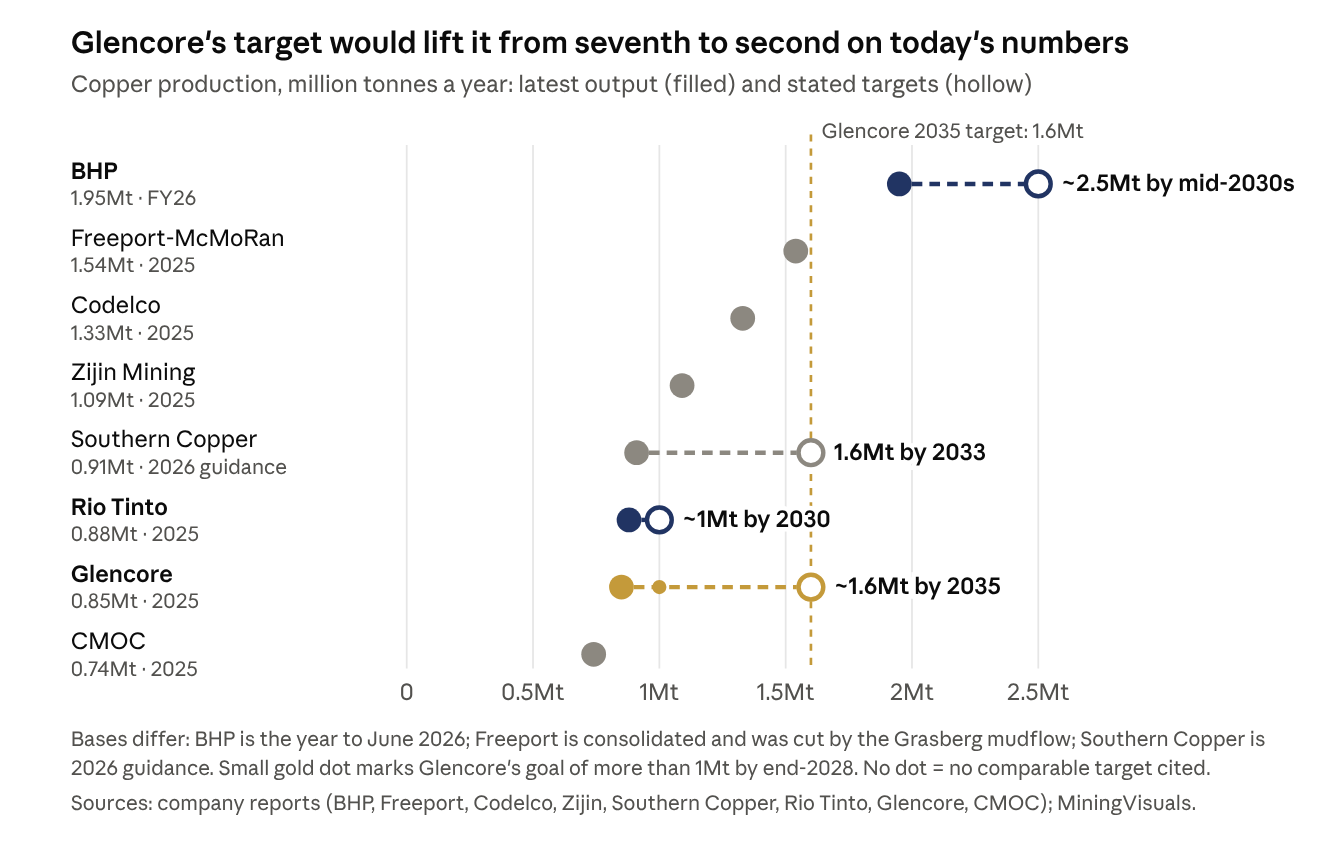
Adding to its copper advantage is that Glencore has some of the most scalable brownfield copper mines. In its ASX investor presentation, Glencore outlined a pathway to more than one million tonnes a year by the end of 2028 and about 1.6 million by 2035, which would make it one of the world's largest copper producers if achieved.
Globally, that only really leaves BHP in front.
Valuation and dividends: BHP and Rio win
On the surface, Glencore is the cheapest of the three. JPMorgan has it on about five times forecast 2027 EV/EBITDA, against more than six times for BHP and Rio.
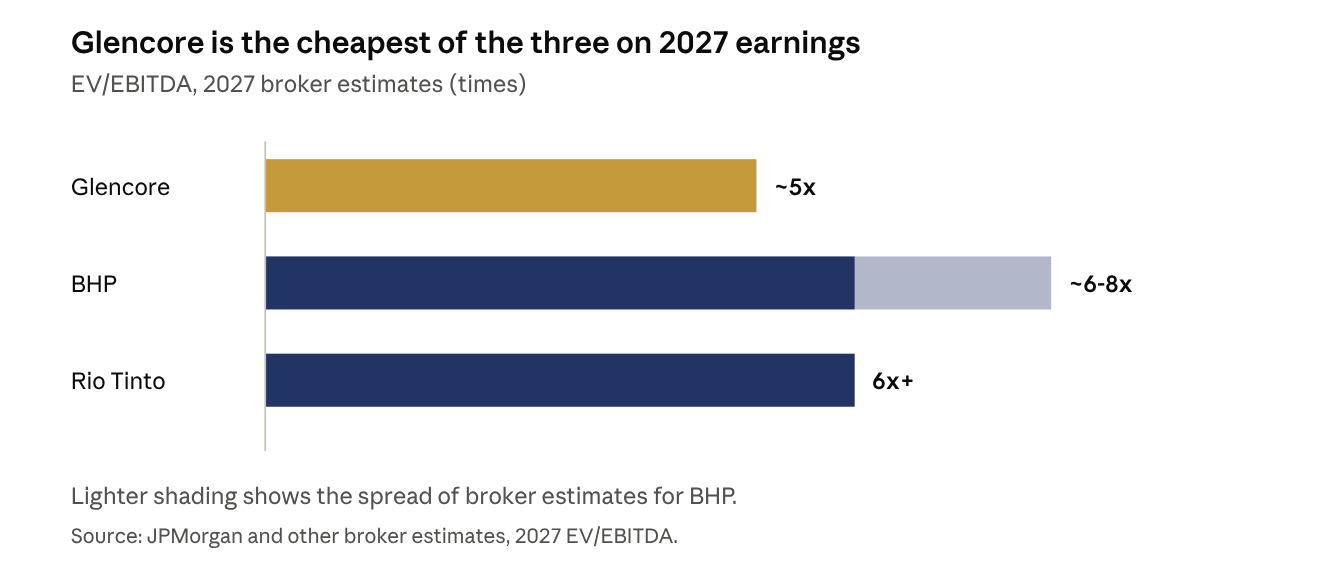
However, this discount needs to be partly understood as governance concerns and a narrower potential shareholder base. For Glencore, there is heavy coal exposure, which many pension funds are restricted from owning. The market also discounts thermal coal assets because of uncertainty around long-term demand and ESG-related constraints.
The trading arm arguably deserves a higher valuation than traditional mining earnings. But a problem is Glencore’s top competitors – like Mercuria, Trafigura, Vitol – are privately held. Meaning there aren’t many comparables.
Dividends unquestionably favour BHP and Rio. Both currently yield about 4%, fully franked.
Glencore tends to prefer buybacks and has a strong track record of buying the dip on its own stock. Its cash dividend yield is around 2% and unfranked.
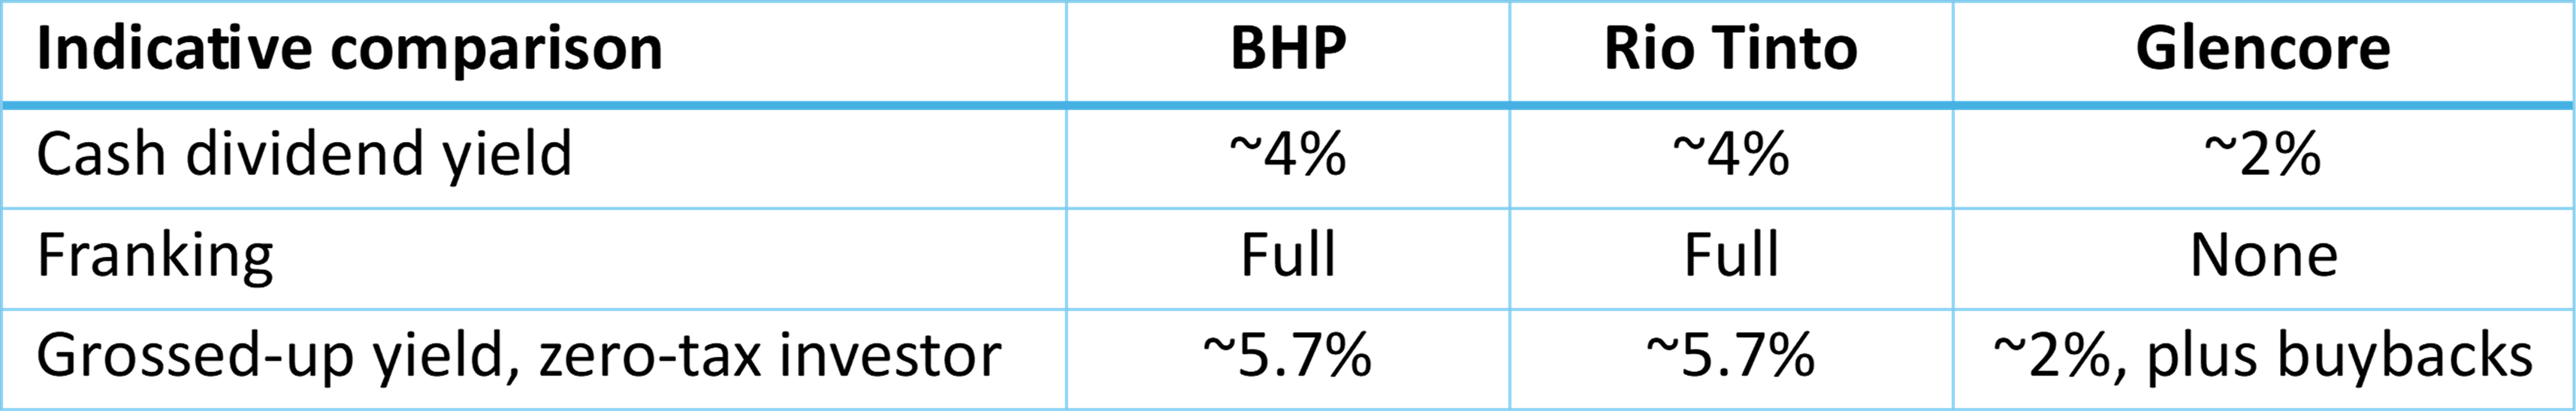
Indicative yields at the time of writing; they move with share prices and distributions. Grossed-up yields assume full franking and a 30% company tax rate.
Franking matters most to super funds in pension phase, which can claim refunds of unused credits. For them, a fully franked 4% dividend is worth roughly 5.7%.
Glencore's distribution framework works differently. It combines a fixed US$1 billion payment from marketing cash flows with a variable component linked to industrial free cash flow, and the board can add special distributions or buybacks when the balance sheet allows.
Its chief financial officer has argued that BHP's and Rio's franking advantage will shrink as their operations become more international. That may happen over time, but for now their Pilbara iron ore earnings remain a deep source of Australian franking credits.
Why buying Glencore early may have benefits over time
Glencore has listed in Australia partly to attract more investment from superannuation funds and narrow its valuation discount. If this works, ASX investors who get in early could benefit.
Index funds and benchmark-aware strategies increasingly dominate Australia’s superannuation system. The result is that yields are thinning and index inclusion premiums for ASX-listed securities are rising.
Glencore's ASX debut exploits that. Glencore is starting small, with just $500 million worth of shares on the ASX. It expects to qualify for the S&P/ASX 200 within 12 months, and the ASX 100 within two years.
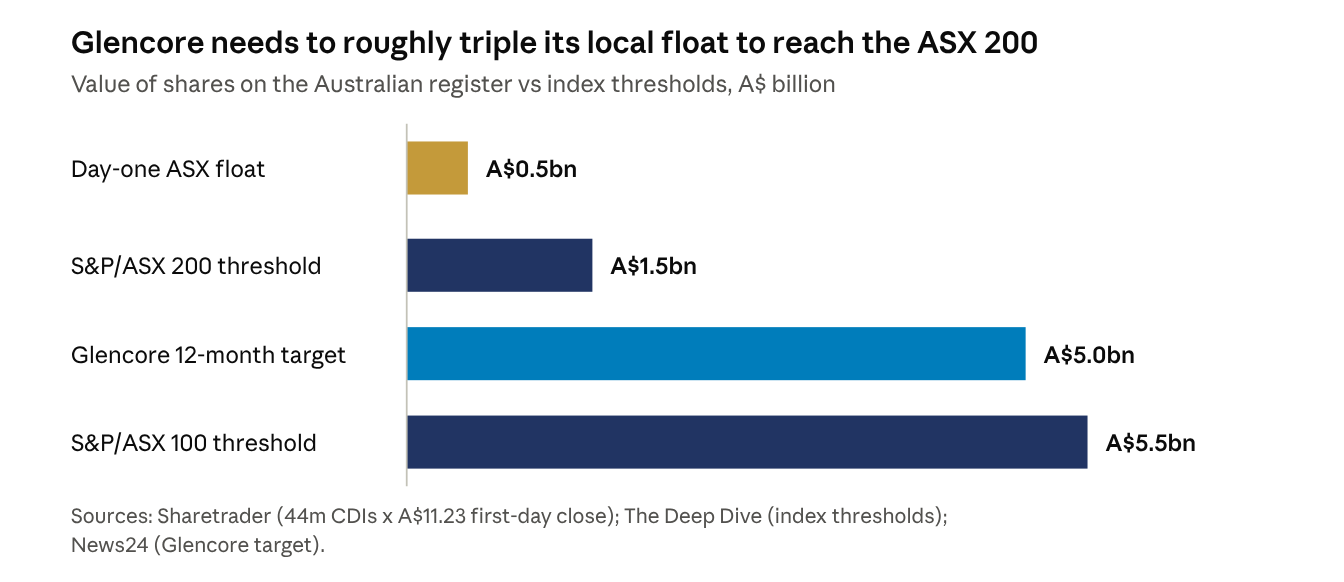
Those targets appear achievable. As Glencore joins the major indices, it may receive a modest valuation uplift (although this is very difficult to quantify).
The key benefit, though, is that local listing raises Glencore's profile with Australian investors.
The verdict
Glencore's arrival gives more copper optionality and a unique trading business for ASX investors.
But BHP and Rio's franked income and stronger governance credentials remain compelling. By coming to Australia, Glencore may benefit from greater visibility and index inclusion over time.
For most investors, BHP and Rio remain credible core holdings. Glencore is worth considering as a satellite position for those who want its mix of copper growth and trading earnings and are comfortable with the risks that come with it.
ETF Shares provides the ETFS Global Pure Play Copper Miners ETF (ASX: CPPR) which began trading on the ASX in April 2026. For more information click here.
David Tuckwell is the Chief Investment Officer at ETF Shares, a sponsor of Firstlinks. He is also a journalist and researcher specialising in finance and international politics. The information provided in this article is general in nature. Before acting on any information in this article, you should consider the appropriateness of the information having regards to your objectives, financial situation or needs and consider seeking independent financial, legal, tax and other relevant advice. Past performance is no guarantee of future performance.
Disclaimer: This article is issued by ETF Shares Management Limited (“ETF Shares”) (ABN 77 680 639 963, AFSL: 562766) and ETF Shares is solely responsible for its issue. Under no circumstances is this article to be used or considered as an offer to sell, or a solicitation of an offer to buy, any securities, investments or other financial instruments. Offers of interests in any retail product will only be made in, or accompanied by, a Product Disclosure Statement (PDS) and target market determination (TMD) available at www.etfshares.com.au.