Somewhere in the paperwork there was a box, and you almost certainly did not tick it. ‘Unhedged’ is the default on most international share funds and the standard setting inside most super options, and it reads like an administrative detail, something to do with plumbing, safely left to the professionals. It is not plumbing; it is a currency position. Taken on your behalf, in your name, and last financial year it was expensive.
Here is the arithmetic up front. In Chant West’s survey of super fund returns, international shares gained 25.5% in 2025-26 in hedged terms and 17% unhedged. Same companies, same year, same underlying performance. The difference, 8.5 percentage points, went to the Australian dollar on the way home. A member with $500,000 in a typical growth fund holds about 31% in international shares, roughly $155,000. Fully unhedged, that grew to about $181,000 over the year; fully hedged, to about $195,000. The gap the currency opened, 8.5 percentage points, is around $13,000 on that $155,000, and most members, whose funds sit somewhere in between, gave up a slice of it. The price of a position they never knew they held.
One caveat: this is not an argument for hedging, or against it. Over long periods the currency has been a friend far more often than an enemy, and that case is the strongest part of this article. The argument is with the word ‘default’. You hold a currency position either way. The only real question is whether you know it.
Two bets in one trade
The mechanics are simple once you say them out loud. Buy a US share and your Australian-dollar outcome turns on two things: what the share did in US dollars, and what the Aussie did against the greenback while you held it. At around US72 cents, every one-cent move in the Australian dollar shifts the Australian-dollar value of a US holding by about 1.4%.
That sounds small until you see how far the currency travels. The Aussie has climbed since the end of 2024, from about US62 cents then to US67 cents a year later, and on to around US72 cents now, its highest level in over a year. Ten cents. About 16%, as big as a strong year in the share market, layered on top of it and running the other way.
What the two funds actually do
The hedged fund strips the currency out and pays you the world market return. The unhedged fund pays that return combined with the move in the Australian dollar. Neither is safer in the abstract. They fail in opposite conditions.
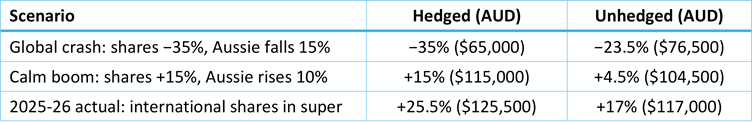
Two Australians, $100,000 each in global shares. The first two rows are illustrative; the third is the actual 2025-26 outcome for international shares in superannuation (Chant West). Source: author’s calculations.
The first two rows are the shape of the thing. In the crash, the falling Aussie absorbs a third of the damage. In the calm year, the rising Aussie eats two-thirds of the gain. Which one you would rather own depends on which year you get, and nobody chooses the year.
The honest objection: the hedged fund is usually the riskier one
Here is the strongest counterargument to everything above, and it is a good one. You would assume that leaving the currency exposed is the risky choice and that ‘hedged’ is the prudent one. For Australians in global shares, the long record says the opposite. The reason sits in the character of the currency. The Reserve Bank puts it plainly: the Aussie is a risk-sensitive currency, one that tends to rise when markets are calm and fall when they panic. So when world shares crash, the Australian dollar usually crashes with them, and that fall quietly rescues the unhedged investor, because a weaker Aussie lifts the Australian-dollar value of every offshore asset they own. The bet nobody chose becomes a shock absorber at the exact moment one is needed.
The global financial crisis is the cleanest example. As markets collapsed the Australian dollar fell around 31%. On Macquarie’s analysis, unhedged global shares fell 33% for an Australian. Painful. The currency-hedged version, stripped of the cushion, fell 51%: half as much again, leaving about a quarter less capital standing. And it is not only crises. Over the two decades to September 2025 the same analysis puts unhedged global shares at 9.5% a year against 9.8% for hedged, all but identical, with the unhedged version delivering it at 11.5% volatility against 14.3%. Less risk, for a rounding error of return.
So 2025-26 is not evidence that the default is wrong. It is evidence that the default is a position, and positions have bad years. What should not survive the year is the idea that the box is administrative.
What to actually do about it
The answer is not the same for every dollar, which is why one setting across a whole portfolio is the mistake underneath the mistake. Money with a deadline in Australian dollars, a house deposit or a portfolio being wound down to a fixed number, is where the case for hedging is strongest: nobody wants a currency swing standing between them and a date, and that money is usually heading to cash regardless. International bonds are the other clear case, and it is why they are so often hedged as a matter of course; their job is to be the calm part of the portfolio and an unhedged currency swamps that job entirely. Equities held for decades are where the case for leaving it alone is genuinely strong, and the record above is why.
For super, the question worth 10 minutes is a factual one: what is your fund's hedge ratio? Most publish it in their investment guide. On Macquarie's reading of APRA's figures, more than three-quarters of the nation's international super exposure is unhedged. That is not a considered national view on the Australian dollar. It is a default, inherited by millions of people who were never asked. One honest uncertainty: the cushion depends on the Aussie continuing to do what it has reliably done, and that is to fall when world shares fall. That is a regularity, not a law. A shock that originates here rather than offshore, or one where the US dollar is not the haven everyone runs to, could see shares and the currency drop together, and the unhedged investor would wear both. Nothing in the record above is a guarantee about the next one.
So the choice between a hedged and an unhedged global fund is not the dull administrative checkbox it looks like on the application form. It is a decision about how much of your portfolio’s fate rides on your own currency, and most Australians are making it by accident. It has been a good accident. But a bet you didn’t know you made is still a bet, and the least you can do is make it on purpose.
Trevor Schmid has more than 20 years’ experience across superannuation and financial advice. He holds a portfolio of unhedged international shares of the kind described here. This article is general information only and does not consider any individual’s objectives, financial situation or needs.