Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 680

Welcome to Firstlinks Edition 680

  •   17 September 2026
  • 5
  •      
  •   

Australians appear to be far more pessimistic about retirement before they get there, than after they arrive.

The latest findings from Vanguard reveal that retirees were considerably more likely to express positive sentiment toward retirement than working-age Australians. In some respects, retirement may turn out better than many people expect.
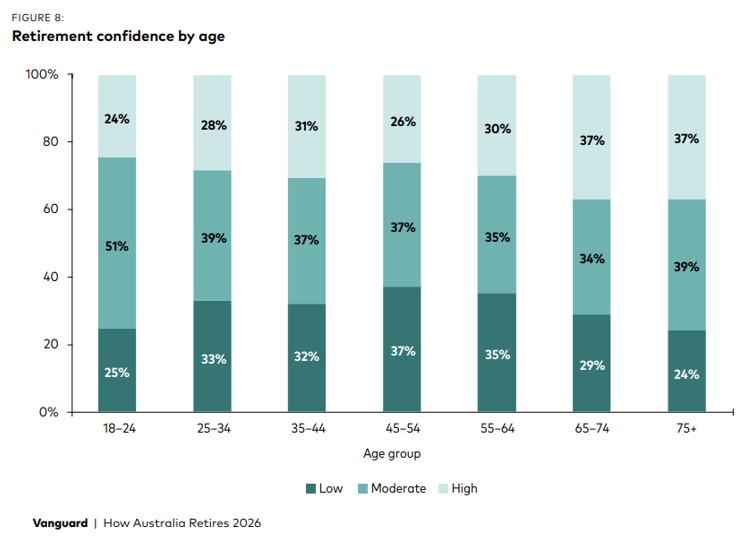
The report suggests this might reflect the advantages many existing retirees enjoy, such as greater accumulated savings, lower levels of debt and clearer retirement plans. That is hardly surprising, but is this gap is misplaced pessimism or a genuine structural shift?

Higher expectations

Working-age Australians increasingly believe retirement will require exceptionally high income levels, exceeding $90,000 per year for a household among younger cohorts. Meanwhile, today's retirees report far lower income needs. 
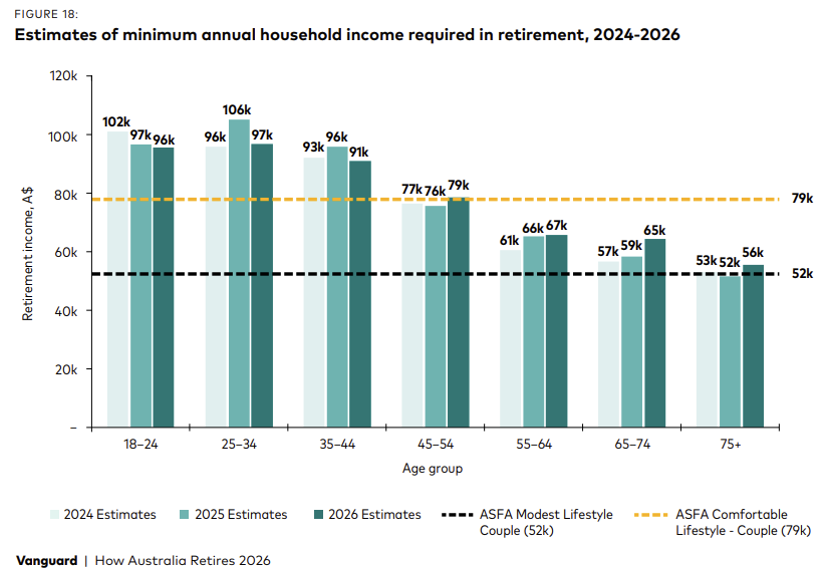
One could argue that social perceptions of retirement have shifted from achieving financial security to achieving something closer to financial abundance. Though I don’t believe the story is simply one of unrealistic expectations.

The role of housing debt

To some extent, younger Australians may be justified in their concerns. Around 61% of respondents identified having little or no debt as an important contributor to retirement confidence. But many of them are unlikely to have the same starting position as current retirees.

Where previous generations viewed retirement as a period free from major financial liabilities, the younger generations increasingly expect those obligations to follow them into retirement. To me, this is the more consequential notion buried in the survey.

For decades, Australia's retirement system has rested on the implicit assumption that retirees own their homes outright, but this appears to be increasingly fragile.

Nearly half of Gen Z respondents and over a third of Millennials expect to retire with a mortgage. Many also expect to continue paying down debt during retirement or to use superannuation to extinguish it. If these expectations prove correct, it will represent a profound change in the way retirement is funded and experienced.
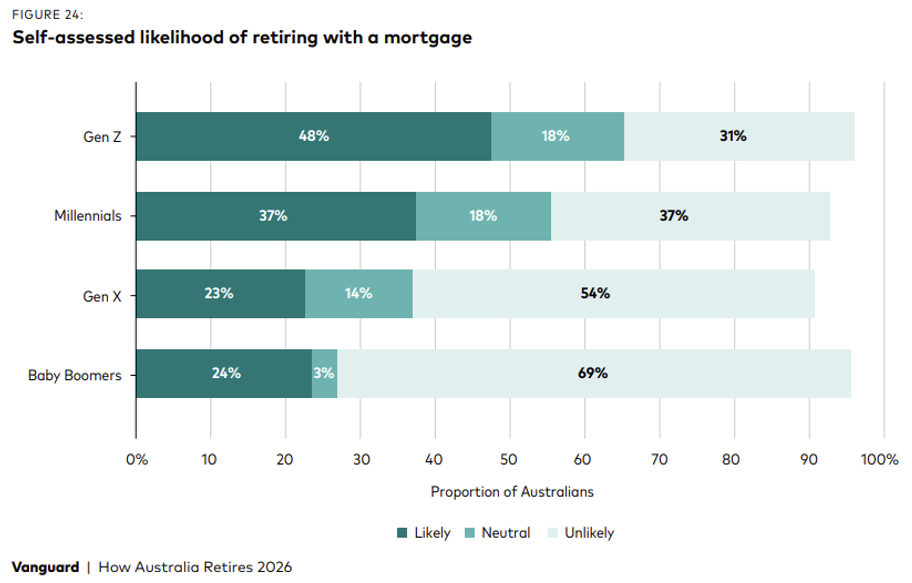
This notion may appear perfectly rational. Eliminating debt before or at the beginning of retirement can dramatically improve cash flow and financial security. Yet it also highlights a shift in the role of superannuation itself. A vehicle for generating income may increasingly become a way to repair household balance sheets.
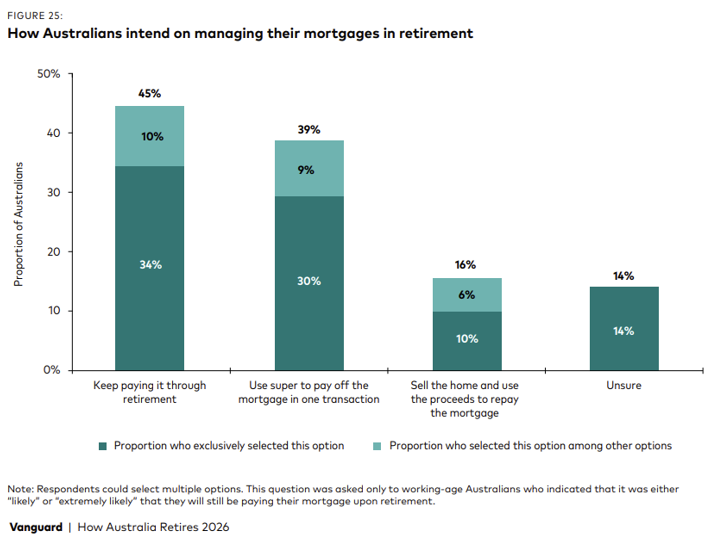
More broadly, it raises questions about how retirement adequacy should be measured. Two retirees with identical balances can face vastly different realities if one owns their home outright while the other is still servicing debt.

There is also a wider policy implication. For years, the assumption has been that compulsory super would lessen dependence on the Age Pension. Yet if a growing share of retirement savings is diverted toward mortgage repayment, the outcome may be more complex than anticipated.

While converting superannuation into home equity may improve Age Pension eligibility, it also leaves retirees with less capital available to generate income. Either way, the assumptions underpinning much of our retirement planning warrant a closer look.

Simonelle Mody

*Please not that the weekend market update is not available this week*

Also in this week's edition...

Testamentary trusts have survived the trust tax. Rachael Rofe is back to reveal a hidden technical detail that could still force many families to rethink wills. 

Shani Jayamanne models how the recent tax changes complicate the task of rebalancing your portfolio. 

Ashley Owen shares a chart that reveals how population growth is masking Australia's productivity problem. 

Despite eyewatering returns from mega-caps, Robert M. Almeida and Ross Cartwright discuss why tomorrow’s winners may not be today’s index leaders. 

Sometimes the important information in an earnings result isn't the number itself. Jarrad Stuart explains why an earnings beat might reveal about future returns. 

Michael Hallinan details a rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong.

Buying global shares means making a bet on both the companies and on the Australian dollar. Trevor Schmid shows how the second bet cost investors 8.5% in the last financial year. 

Curated by Simonelle Mody and Leisa Bell

A full PDF version of this week’s newsletter articles will be loaded into this editorial on our website by midday.

Latest updates

PDF version of Firstlinks Newsletter

Monthly Gold ETF Flows from World Gold Council

Monthly Bond and Hybrid updates from ASX

Monthly Investment Products update from ASX

Listed Investment Company (LIC) Indicative NTA Report from Bell Potter

Plus updates and announcements on the Sponsor Noticeboard on our website


  •   17 September 2026
  • 5
  •      
  •   
5 Comments
John G
September 18, 2026

All mortgages should be interest only with capital repayment at the discretion of the mortgagee without penalty when financial circumstances permit. A property purchased in the early 40's would still have 25 years of compounded inflation whilst the value of the mortgage would at worst remain stagnant. The killer for a retiree is that they are still paying back capital at a high rate for 5 - 10 years instead of just paying interest. Let inflation of income and property carry the burden.

Dudley
September 20, 2026


"Nearly half of Gen Z respondents and over a third of Millennials expect to retire with a mortgage. Many also expect to continue paying down debt during retirement or to use superannuation to extinguish it.":

Those Rational Gen Z individuals without prospects of accumulating ~$2,000,000 in today's money by Age Pension Eligible Age would look at the incentives offered by the Age Pension and conclude that the Commonwealth wants them to convert their Superannuation and other Age Pension Assessable Assets in excess of the Age Pension Asset Test Full Pension Threshold to Home Equity to position themselves to be eligible for the Full Age Pension.

Having passed through the age of the smallest savings interest rates in the history of the known universe resulting in unusually large home price growth rates the Rational Gen Z would have joined the fray and mort-gaged themselves to the gills to position themselves to collect the tax free capital gains resulting from that home price growth.

Possibly just in time for a home price recession and resulting negative equity and increased Age Pension dependency resulting from normalising interest rates and the perverse Age Pension Asset Taper Rate.

Mike
September 21, 2026

Then Gen Z are fools, because no one in their right mind would want the Age Pension. It is set at 'just above' the poverty line for this very reason, so that you save for your own retirement.

Gen Z won't even be taking the plane on overseas holidays, let alone be in Economy class if they go on the pension.

Dudley
September 21, 2026


First calculate how much capital an Age Pensioner couple currently needs to have a cashflow exceeding the age pension plus earnings on the Full Age Pension Assessable Assets Threshold?

Second what portion of the Age Pension Aged or older will have that amount of real capital or more?

Look for my calculations here:
https://www.firstlinks.com.au/why-spending-more-in-early-retirement-can-improve-lifetime-income


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.