Rebalancing has been one of the simplest rules in investing. Set your target asset allocation, let your portfolio move away from it as markets rise and fall, then periodically sell what has done well and buy what has lagged.
It sounds almost mechanical and this is why it works. Setting a structure instead of leaving buying and selling to chance can improve outcomes. If you want a portfolio with 70% growth assets and 30% defensive assets, you sell enough of your growth investments when they reach, say, 75%, and put the proceeds into defensive assets.
The result is a risk-considered portfolio that remains aligned to the asset allocation required to achieve your goals. This is not an exercise free of consequence. Selling appreciated investments will create a tax bill for most.
As we move from the 50% capital gains discount after 12 months to a minimum 30% tax rate, rebalancing becomes more expensive. The new tax environment favours those that are in it for the long haul. The nuance is that investors in it for the long haul will likely pay more for the benefits of rebalancing.
I look at the real cost below, and alternatives to the approach.
The hidden cost of rebalancing
Consider an investor that has a 70/30 split between international shares and bonds. Over a year, international shares perform strongly and the portfolio becomes 80% international shares and 20% bonds.
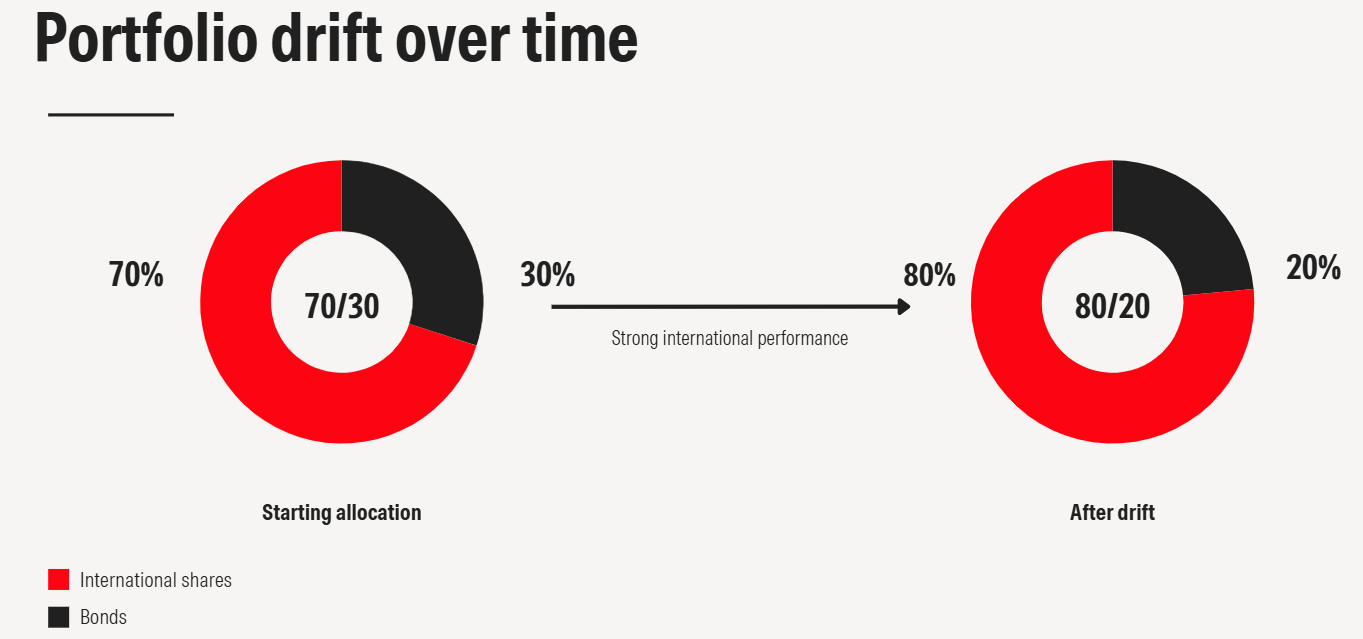
The textbook rebalancing move is straightforward: sell some international shares and buy bonds. The international share allocation has generated a large unrealised capital gain, and selling crystallises that gain.
Under the current system, if the assets are held for 12 months, the capital gain may be reduced by the 50% CGT discount. The system in place from 1 July 2027 operates on an indexation method. Selling assets frequently to maintain asset allocation percentages in your portfolio will have larger consequences.
Let’s go through an example. You had $10,000. You invested 70% of your portfolio in Betashares Asia Technology Tigers ETF (ASX ASIA) and 30% in Ishares Core Composite Bond ETF (ASX IAF) on 24 August 2025. One year later, you have a portfolio worth $14,137.45, with ASX ASIA returning 58.82% for the period. This position has grown to 80% of your portfolio, and you want to return it to 70%. The sale would look as follows under the two tax regimes.
Sale of $1309.70 to bring ASIA holding back to 70%.
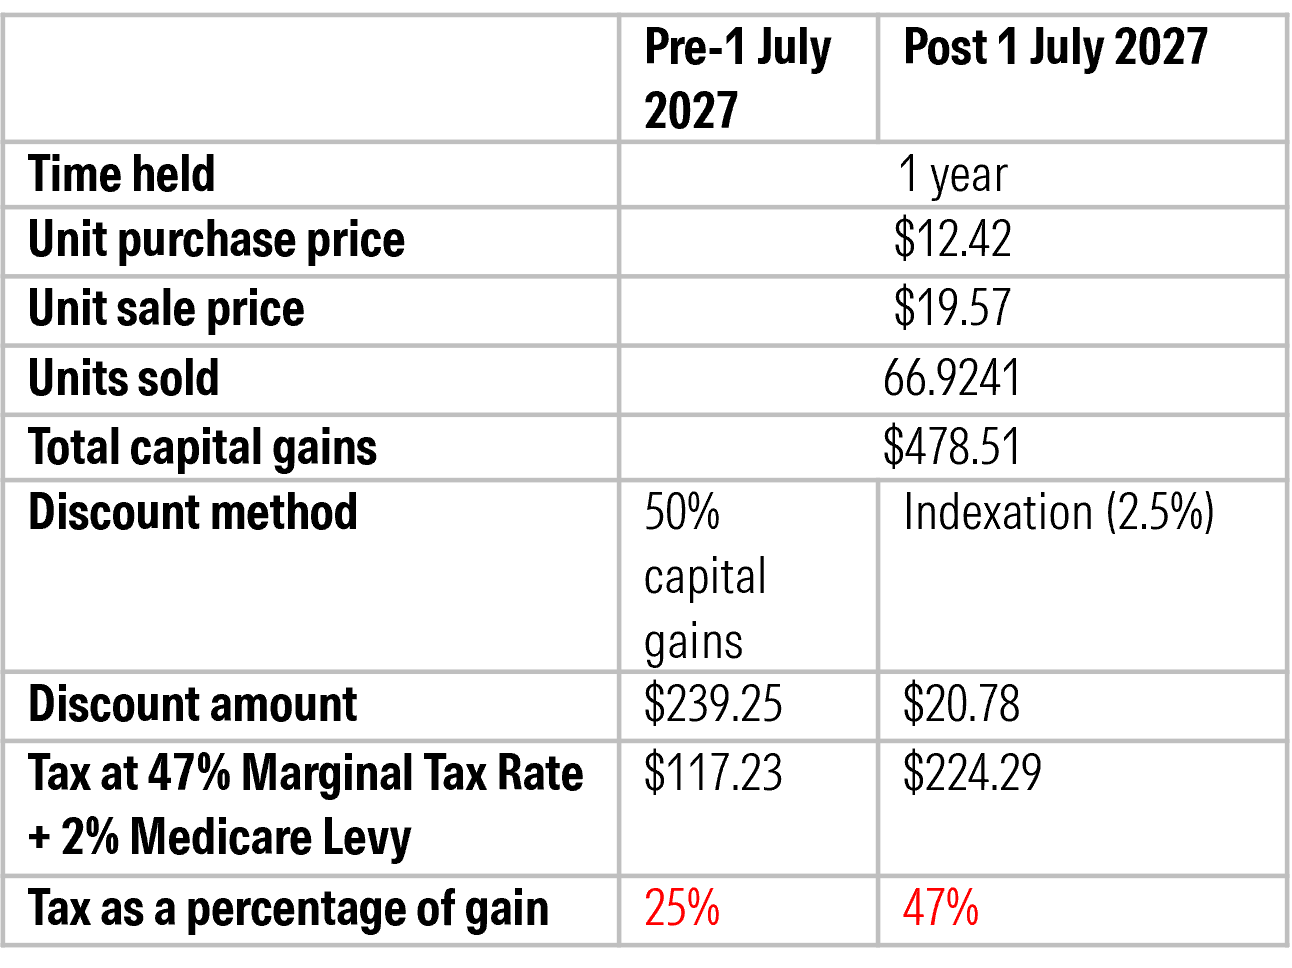
A sale like this at each rebalancing interval makes a meaningful difference to your portfolio outcomes over the long term.
This may change the mindset from ‘how do I reduce risk in my portfolio?’ to ‘what will it cost to fix it?’. It may encourage investors to leave portfolios alone for longer while they drift further away from the target asset allocation.
When tax efficiency starts driving portfolio decisions
There is nothing wrong with considering tax when managing investments. In fact, tax is an important part of an investor’s total return. I’ve written about tax alpha here.
The danger comes when tax efficiency becomes the objective rather than one of many considerations in a broader investment plan. An investor might look at a portfolio and conclude that selling an overweight asset is too expensive because of the capital gain and leave the portfolio as is which may lead to a worse long-term outcome.
The good news is that selling isn’t the only way to bring a portfolio back towards its target. Here are a few ways to temper risk in your portfolio without resorting to what may be an expensive sale.
Ways to rebalance without selling
Using new money
One of the simplest alternatives is to use new money. Suppose an investor wants a 70/30 portfolio but it has drifted to 75/25 because shares have performed strongly. Rather than selling shares, the investor could direct new contributions towards defensive assets until the allocation moves closer to the target.
This is particularly useful for investors who are still accumulating wealth and regularly adding money to their portfolios. It is not as useful for investors in retirement.
Redirecting portfolio income
The same principle can apply to dividends, distributions and other portfolio income. Instead of automatically reinvesting every dollar into the asset that generated it, investors can direct that cash towards whichever part of the portfolio is underweight. It is a form of rebalancing that doesn’t necessarily require selling.
Rebalancing across accounts
It is common for investors to undertake ‘mental accounting’. Assigning particular investment accounts to certain goals and not taking a step back to look at their portfolio holistically. I am guilty as sin on this count.
For investors with investments held in different structures, there may be opportunities to make allocation changes where the tax consequences are more advantageous. Superannuation, for example, operates under its own tax rules, so the most tax-efficient way to change an overall investment mix may not involve selling assets in a taxable investment account. This is where portfolio management involves more than looking at an individual brokerage account.
It may be worth looking deeper at where in an overall portfolio a change can be made, including the structures that hold each asset class. Generally, it is worth holding growth assets where capital gains may be incurred in more tax effective accounts such as superannuation, with defensive assets held in less tax effective environments.
Rebalancing bands may become more important
Another approach is to stop thinking about rebalancing as something that happens at a particular time of year. Instead, investors can establish a range around their target allocation. For example, an investor might decide that a 70% allocation to growth assets is acceptable if it fluctuates between 65% and 75%. For investors with longer time horizons, this range may be even broader.
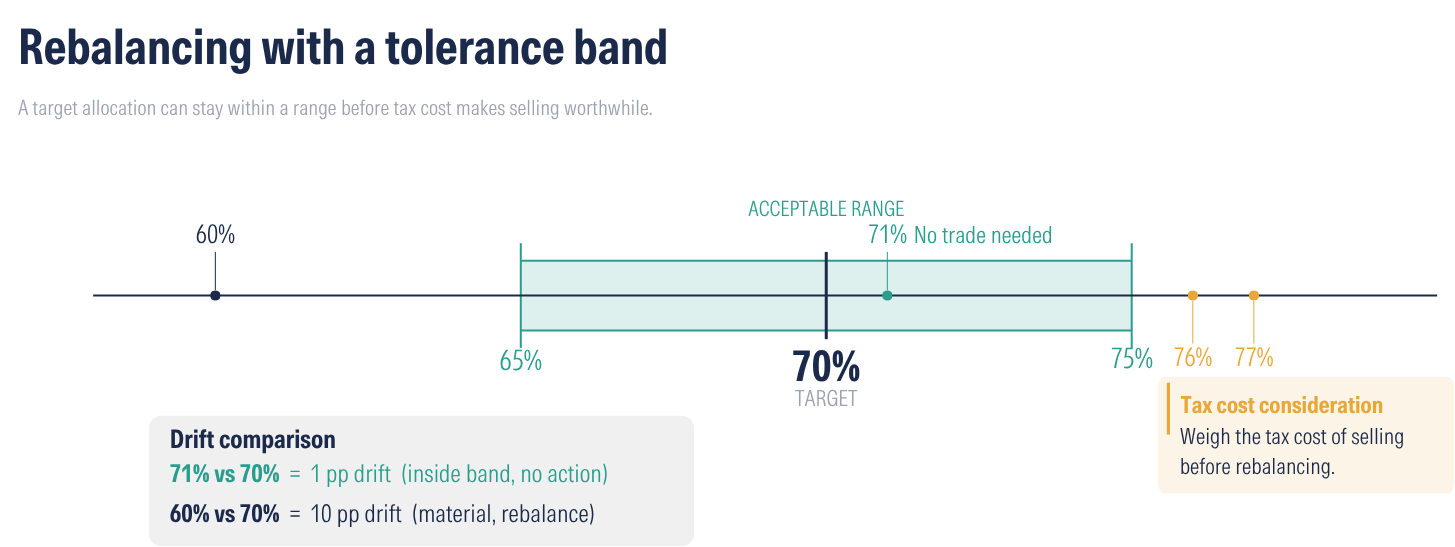
There is no need to sell simply because the portfolio moves from 70% to 71%. If it reaches 76% or 77%, the investor may decide the deviation has become large enough to justify the tax cost of selling.
The bigger the unrealised gain, the more valuable it is to tolerate some portfolio drift. That doesn’t mean every investor should have enormous tolerance bands. A portfolio that is 60% growth assets instead of 70% is materially different from one that is 71% instead of 70%. The appropriate threshold will depend on your time horizon and capacity for risk.
Selective selling
Even when selling is necessary, you don’t necessarily have to sell the asset with the largest overall gain. A portfolio can contain multiple parcels of the same investment purchased at different prices.
One parcel might have a substantial unrealised gain while another parcel has a smaller gain. Selling the parcel with the smaller gain may achieve much of the same portfolio adjustment with a smaller immediate tax consequence. Keep good records for the ATO.
One strategy that may be used in conjunction with a professional accountant may be to choose selective parcels based on future income tax assessments. If you are close to retirement, older parcels with large gains could be deferred, with the CGT discount being grandfathered for holdings prior to 1 July 2027. This will not cover gains past 1 July 2027, but will mean the bulk of these parcels are not subject to the minimum 30% tax.
Capital losses can also be used as an offset. An investor who has realised or carried forward capital losses can use them to their advantage, subject to the tax rules.
The risk of becoming too tax efficient
There is a paradox here. One of the biggest benefits of the Australian tax system has historically been that investors can defer tax on unrealised capital gains. You don’t generally pay CGT simply because an investment has gone up in value.
That creates a powerful incentive to hold investments rather than constantly trading them. There is a point where avoiding tax becomes counterproductive. Imagine an investor owns an asset they no longer want, but they refuse to sell because it has a large capital gain.
This may be seen as tax efficient, but the opportunity cost is high if the investment no longer fits their risk profile, asset allocation or financial goals. The net funds could be put to better use.
The same is true at the portfolio level. An investor who has gradually become significantly more exposed to shares because shares have outperformed may be taking considerably more risk than they intended. Avoiding a tax bill doesn’t make that additional risk disappear. It simply means the investor is paying for tax efficiency with a different currency - portfolio risk.
Rebalancing is not dead – it may still be the answer
For some investors, paying the tax bill will still be the right decision. Consider someone approaching retirement whose portfolio has become substantially more aggressive after a strong run for shares. They may have accumulated a large unrealised capital gain and selling some of those investments could trigger a significant tax liability.
If the alternative is entering retirement with substantially more investment risk than they can afford to take, the tax bill may be a price worth paying.
The same applies to investors whose circumstances have changed. A portfolio constructed for someone in their 30s may no longer be appropriate when they are in their 60s. A portfolio built around a particular financial goal may need to change once that goal is approaching. It may mean that when the goal appears, the portfolio is in the wrong place to actually use the funds sacrificed for said goal.
Tax should influence the implementation of that change. It shouldn’t necessarily determine whether the change happens.
Think about the portfolio, not the tax bill
The biggest lesson from the CGT changes may have less to do with tax and more to do with how investors think about their portfolios. The changes have disappointed many investors, but instead of structuring around the changes, ask a more useful question – what portfolio gives you the best chance of achieving your financial goals?
It may mean using some of the alternative methods to ‘rebalance’ your portfolio, or it might just mean biting the bullet. Rebalancing is simply a tool that keeps your portfolio on track, and the tax changes make that tool more expensive to use. It does not make the tool obsolete.
Shani Jayamanne is Director, Investment Specialist, at Morningstar Australia.