Many investors think of the share market as a multiple-choice test with just two answers. An investment is either good or bad. Find the good investments and you get rewarded.
In reality investing is a multiplayer game. The people you are playing against matter in the outcome you achieve.
A company’s future earnings matter, but how they compare with everyone else’s expectations matters. A wonderful business can produce disappointing investment returns if priced for perfection. Conversely, a mediocre company can generate excellent returns if expectations were excessively pessimistic.
I try to explain this to friends of mine who have received company shares as part of their remuneration package. They tell me about their companies’ strong earnings and growth but can’t figure out why the share price is stagnant.
Investing isn’t a mathematical formula. Expectations and the decisions and opinions of other investors matter. Fundamentals matter but so does the study of how the decisions of others influence outcomes. This is called game theory.
The prisoner’s dilemma of investing
One of the best-known examples in game theory is the prisoner’s dilemma. For those who are unfamiliar, a quick explainer. This is a famous thought experiment where two criminals are arrested. Both prisoners are placed into solitary confinement with no means of communicating with each other.
Police do not have enough evidence to convict either criminal on a severe charge but enough to convict both on a lesser charge carrying a sentence of one year. The police offer both criminals the opportunity to testify against their partner. If they take the deal they will be let off and the other criminal will get the main charge and penalty of three years.
If both take the deal, they will be sentenced to two years of gaol. Neither criminal has any insight into what the other has decided.
Both criminals take the deal because they are worried the other will inform on them. They each get two years, but the best action would be to stay silent and get one year.
Investing has its own version of the prisoner’s dilemma.
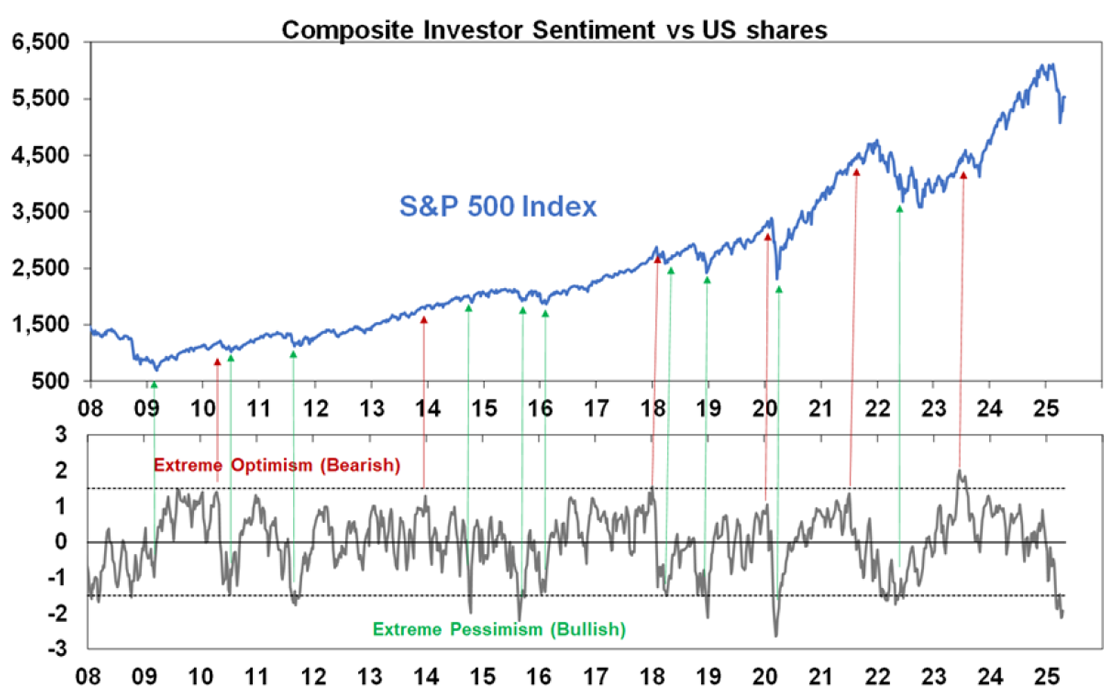
The above chart from AMP looks at April 2025 during tariff turmoil in the US. It shows investor sentiment which includes surveys of investment newsletter writers and individual investors and the ratio of puts (options to sell shares) to calls (options to buy).
Extreme pessimism often leads to large dips in the index, where investors clammer to remove themselves before others do. They do not want to be the one left holding the bag. This is an example of the concept of loss aversion – where a loss feels twice as painful as an equivalent gain
Conversely, extreme optimism leads to insertion into the market as investors look to capitalise before others.
Imagine if more investors remained patient during a market correction. Share prices would likely recover more quickly, and everyone would benefit. Instead, many investors sell because they fear others will sell and try to get out first. Those sales encourage further selling, which reinforces the original fear.
The same dynamic occurs during market bubbles. Investors buy not because they believe prices are justified, but because they believe someone else will pay even more tomorrow. Neither behaviour needs irrational people, it just requires people responding to their perception of the incentives they face.
The best path forward as an investor is to avoid collusion with this short-term prisoner’s dilemma – in other words, focus on market fundamentals instead of following the herd.
Avoid portfolio decisions based on anticipating what everyone else is going to do. Make decisions based on frameworks that outline what does and doesn’t belong in your portfolio irrespective of how you think others will react over the short-term.
The danger of following the crowd
Game theory explains why following the crowd isn’t always the safest option. When uncertainty increases, investors naturally look to others for reassurance. If everyone seems optimistic, buying feels safer. If everyone appears fearful, selling feels sensible.
Markets have a habit of rewarding investors who can separate information from emotion. This doesn’t mean always being contrarian, because often the crowd is right. What it means is recognising that popularity itself isn’t evidence that an investment will pay off over the long term. By the time everyone agrees on an opportunity, much of the potential upside may already be reflected in the price.
Every generation has had their version of this danger. The dot-com bubble, lithium, crypto – the list goes on. Some of these prove to be great long-term investments, but many investors still lose money because they buy at inflated prices.
Think about incentives
One of the simplest lessons from game theory is that incentives are important. Every participant in financial markets has different objectives.
A fund manager may be judged against a benchmark every quarter, so they’re expected to keep adjusting their portfolio while providing compelling justifications to clients.
A CEO may focus on short-term earnings because their remuneration depends on it. Financial commentators and ‘finfluencers’ are rewarded for making bold predictions rather than admitting uncertainty because it generates engagement.
ETF providers compete by launching products that attract investor attention – including those that encourage investors to follow the herd.
None of these incentives are inherently bad. They’re simply different from the incentives I face as I invest for retirement over the next 30 years. I don’t need to outperform a benchmark every quarter, and I don’t need to have an opinion on every earnings season.
Fund managers and professionals are intelligent people, but that does not mean that every decision they make is appropriate for individual investors. Understanding this can help investors avoid reacting to decisions that make perfect sense for someone else but may not be appropriate for them. I’ve written about this in detail here.
Being the best investor is less about intelligence and more about discipline
One more insight for investors from game theory – success often comes from choosing the right game rather than trying to outsmart everyone else.
If you are picking individual shares, it’s important to recognise if you have an ‘edge’. What I would add to having an edge, is that you are able to maintain an edge and apply it consistently.
Most investors cannot consistently predict earnings better than the market or forecast interest rates more accurately than economists. Fortunately, long-term investors can hand off most of the work to the passage of time – an edge that institutional investors do not have.
There is no pressure for us to outperform this quarter or explain short-term underperformance to clients. We do not have to listen or respond to daily market noise.
Remaining invested in low-cost investments, diversifying appropriately for your goals and avoiding emotional decisions can be a powerful investment strategy.
Final thoughts
Game theory reminds us that investing is as much about human behaviour as it is about finance. Every day, millions of investors are responding to uncertainty, incentives, headlines and each other.
That interaction creates opportunities, but it also creates temptations to chase performance, panic during downturns or assume that popular investments are automatically good ones.
The investors who tend to succeed over long periods aren’t necessarily those who know the most. They’re often the ones who understand the game they’re playing.
Shani Jayamanne is Director, Investment Specialist, at Morningstar Australia.