For much of the past decade, the United States appeared unassailable in technology. Its world-leading universities, deep capital markets and ecosystem of entrepreneurial companies created a durable advantage across software, semiconductors and digital platforms. China, by contrast, was often viewed primarily as a manufacturing power: highly capable, but more dependent on imported technology and foreign intellectual property.
That distinction is becoming increasingly outdated.
The accelerated development of China’s technology sector has not been reflected in its stock market performance, and Chinese tech company valuations continue to lag their US peers, which have soared following an extended bull run. Regulatory uncertainty, geopolitical tensions and intense domestic competition have weighed on valuations and shareholder returns, even as China has significantly strengthened its technological capabilities.
Today, China has developed a technology ecosystem that is broader, deeper and more innovative than many international investors appreciate. From artificial intelligence and advanced manufacturing to electric vehicles, batteries and semiconductors, Chinese companies are increasingly competing at the technological frontier. In some areas, China is not only competing, but is the clear global leader, with the country accounting for 59% of global robotics developments[1] and 75% of global EV manufacturing[2] last year.
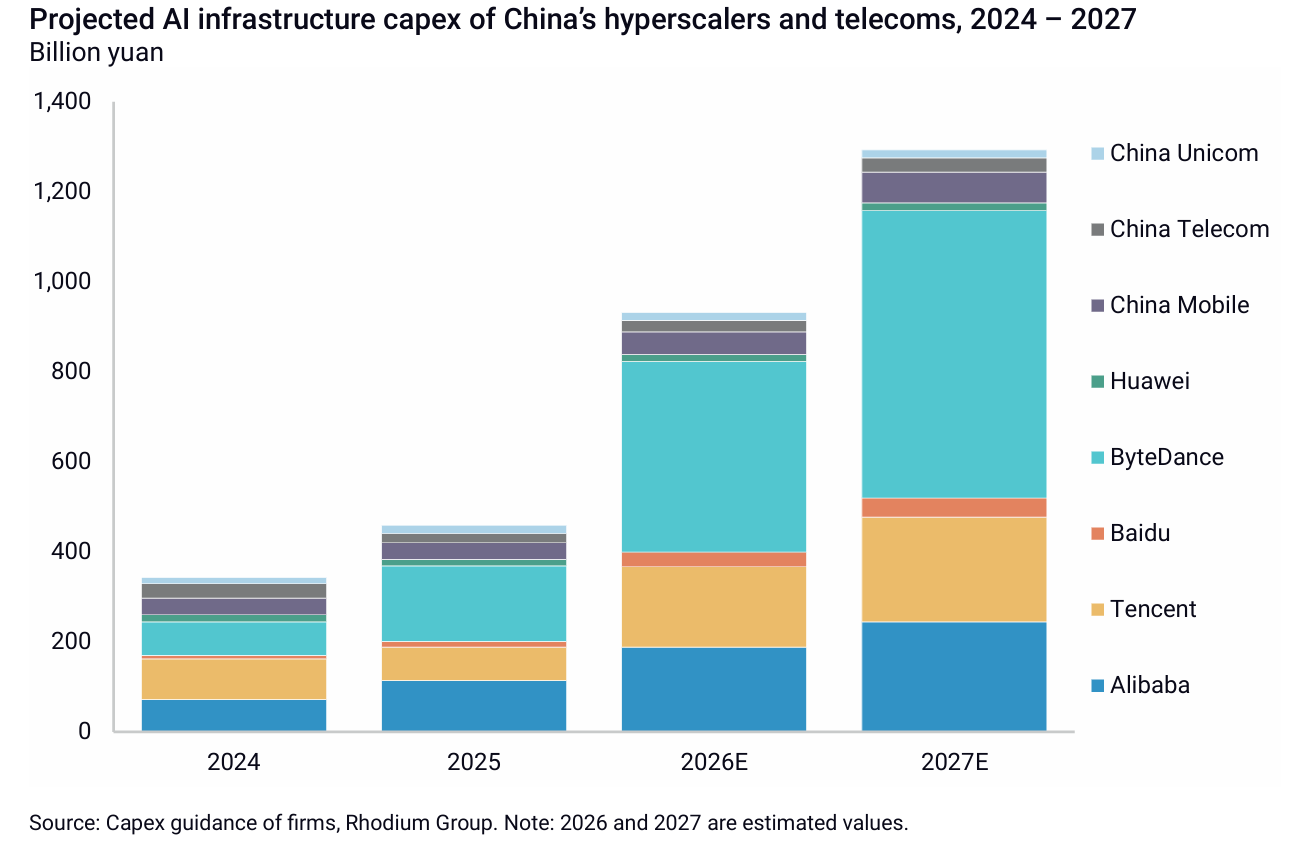
What I find particularly interesting is that the US and China are actually moving in a similar direction. Both have decided that technological leadership matters enormously, and both are committing extraordinary amounts of capital and resources to AI, semiconductors and advanced technology. In China, AI infrastructure capex is expected to more than double this year, rising 103% to RMB 932 billion ($139 billion) following 33% growth in 2025.[3] What differs is how they are going about it. For investors, this matters because the opportunity is no longer simply about choosing between US and Chinese technology. Both markets are producing innovation, but through very different ecosystems, and increasingly with different sources of competitive advantage.
The US remains exceptionally strong in areas such as advanced semiconductor design, cloud computing, software and the development of frontier AI models. Its combination of capital, talent and entrepreneurship remains difficult to replicate.
China’s strengths are different. Its enormous domestic market, manufacturing depth and highly integrated supply chains allow new technologies to move rapidly from development to commercial deployment. In areas such as electric vehicles, batteries, renewable technology and increasingly AI, Chinese companies can innovate, manufacture and scale at remarkable speed.
The development of AI illustrates the contrast particularly well. The US has led much of the global investment in the most advanced models and computing infrastructure. China, facing tighter access to some leading-edge technologies, has been focusing on efficiency, domestic capability and the practical application of AI across its economy. That focus is helping create a more self-sufficient technology ecosystem, with Chinese companies investing across the semiconductor value chain, data infrastructure, AI models and applications. The result may not mirror the US technology sector, but that is precisely the point: two distinct models of technological development are emerging.
This is also not simply a China story. The same shift is visible elsewhere in emerging markets.
Some of the world’s most important technology companies sit in Korea and Taiwan, and they are where much of the AI infrastructure is physically made. Advanced foundry capacity and high bandwidth memory are genuine bottlenecks in the AI build, and the companies that control them have been the principal driver of strong emerging market returns since the start of 2025.
What interests me most is a change in the character of those businesses. Memory has historically been a commodity, priced on the spot market and prone to violent cycles. Increasingly, it is being sold under multi-year supply agreements, at price floors above the peak margins of the last cycle, while new capacity looks likely to remain constrained into 2028. That points to better and more visible earnings through the cycle than investors are used to.
Across these markets, the more interesting question is not which country leads, but which companies do. For a long time, the assumption was that China’s largest technology platforms would naturally lead the next phase of innovation. I don’t think that is a given anymore. Increasingly, capital and attention are moving towards AI-native companies, semiconductors and the infrastructure underpinning the next wave of technology, rather than automatically towards the large-cap incumbent platforms.
Identifying where innovation is happening is only half the task. The second half is what you are being asked to pay for it. US technology companies offer exposure to some of the world’s most profitable and innovative businesses, but in many cases those characteristics are already reflected in valuations. Elsewhere the picture is different. Years of regulatory uncertainty, geopolitical concerns and weak investor sentiment have left parts of the Chinese technology sector trading at lower valuations, while in Korea and Taiwan share prices do not yet obviously reflect the shift in earnings profile.
Lower valuations alone do not make an investment case. The more important question is whether the underlying businesses are improving and whether innovation is translating into sustainable earnings growth, which has traditionally led to equity returns. Increasingly, in selected areas of emerging market technology, we believe that is happening.
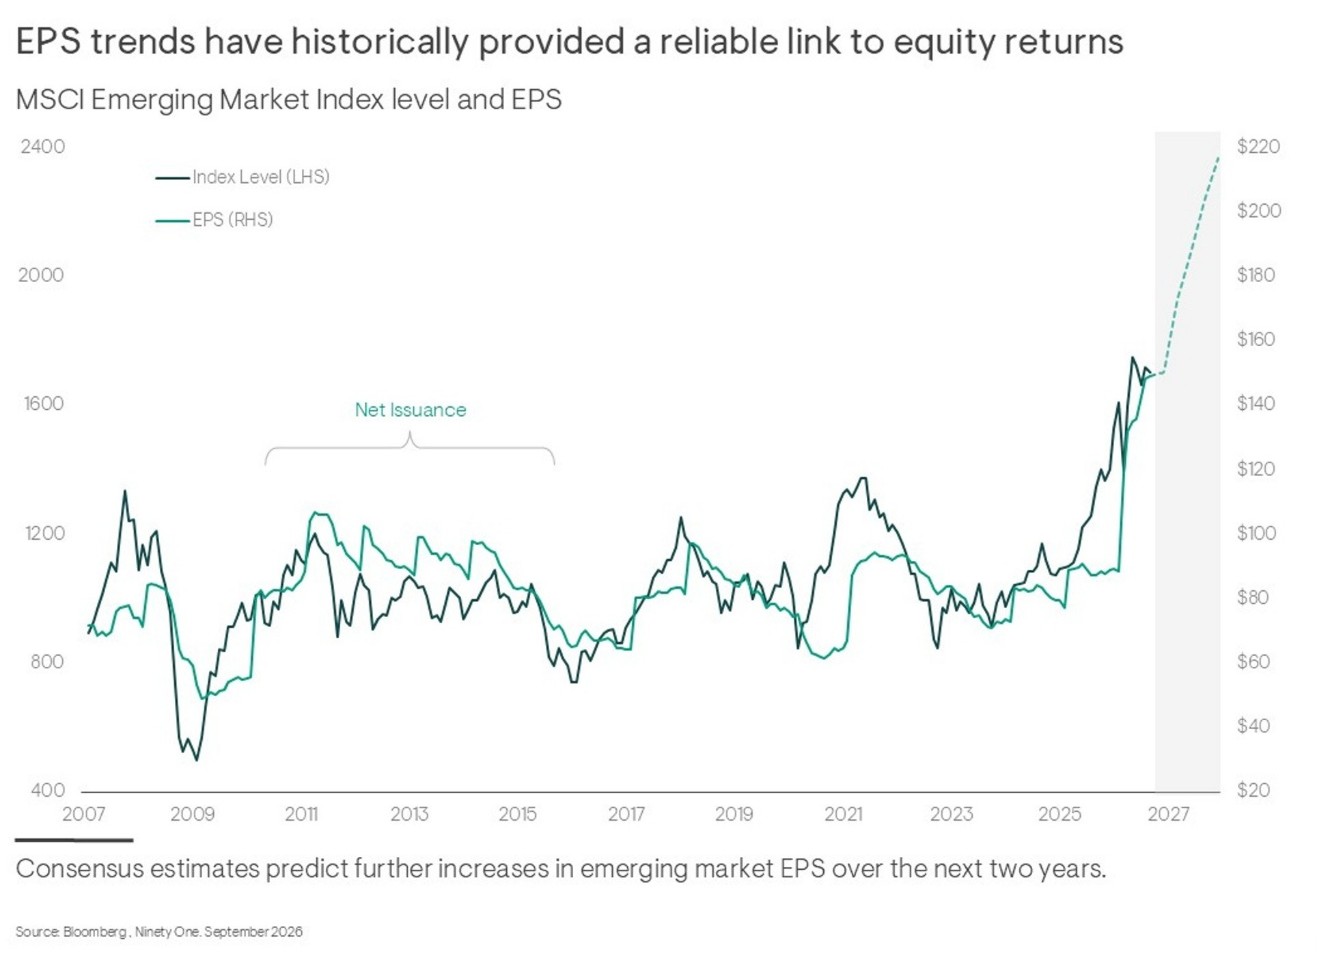
For investors, that changes the question we should be asking. It is no longer simply which companies dominate technology today. It is which companies, and which ecosystems, are best positioned to lead the next wave.
Varun Laijawalla is an Emerging Markets Equity Co-Portfolio Manager at Ninety One. Archie is a co-portfolio manager for the Emerging Markets Equity and Emerging Markets ex China Equity strategies in the 4Factor team at Ninety One.
This article is for general information only and should not be construed as advice. This information is believed to be reliable but may be inaccurate or incomplete. The views are those of the contributor at the time of publication and do not necessarily reflect those of Ninety One. Any opinions stated are honestly held but are not guaranteed and should not be relied upon.