Markets are constantly trying to anticipate what comes next. Reserve managers at central banks, by contrast, spend far more time thinking about the forces that could reshape the global financial system over the next decade and beyond.
Regardless of timeframe, all investors are navigating a changing investment environment. Assumptions that underpinned portfolio construction for much of the past three decades; stable inflation, deepening globalisation, low government debt and reliable diversification from government bonds, are being challenged. Inflation has become more persistent. Fiscal deficits have expanded. Geopolitical fragmentation has intensified. Traditional relationships between major asset classes have become less predictable.
Against that backdrop, the question is becoming less about which asset performs best in the next six or twelve months, and more about which assets can help portfolios remain resilient across a much wider range of possible outcomes.
Gold sits at the centre of that discussion. Not just because it has performed strongly in recent years, but because it possesses characteristics that are increasingly difficult to replicate elsewhere. Put simply, gold is valued not just for what it is, but also for what it is not: it is no one's liability, no government's promise, and no country's currency.
A different way of thinking
The World Gold Council's latest Central Bank Gold Reserves Survey provides an important insight into how reserve managers are viewing gold within the changing landscape.
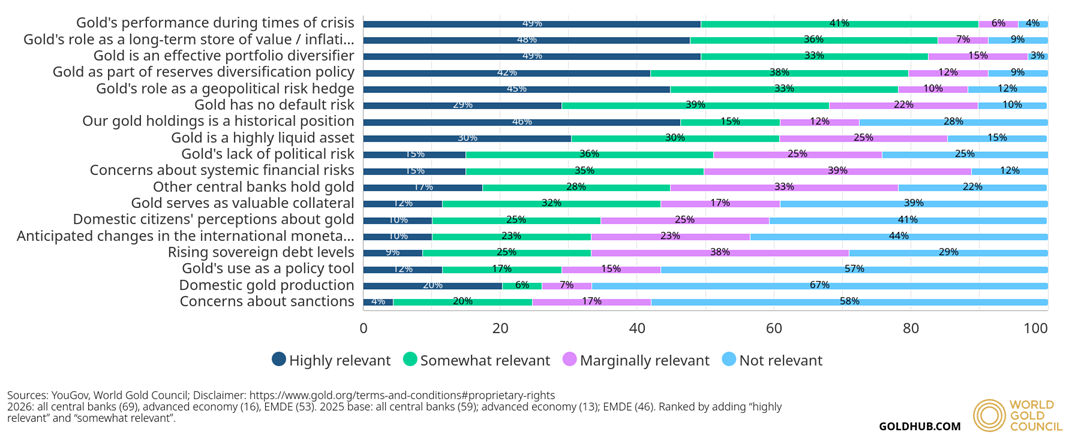
Almost half (45%) expect to increase their own gold holdings over the next twelve months and nearly nine in ten (89%) expect total global central bank gold holdings to continue rising. They cite gold's performance during crises, its long-term store of value and its diversification benefits as the primary reasons for holding it. They also place less weight in holding gold as a historical legacy, inherited from prior monetary regimes. Gold is increasingly being viewed not as an inherited reserve asset, but as a deliberate strategic allocation.
Equally revealing is what they expect to happen elsewhere. Nearly three-quarters (74%) believe the US dollar's share of global reserves will decline over the next five years, over which time, more than four in five (83%) believe gold will account for a larger share of global reserves over the next five years.
This should not be interpreted as a prediction of the end of the US dollar. Rather, it reflects an effort among central banks to build more balanced reserve portfolios in a world where economic power, trade relationships and geopolitical risks are becoming more diffuse.
Understanding what makes gold different
Understanding why reserve managers continue to allocate to gold requires understanding what makes it fundamentally different from most financial assets.
Unlike equities or bonds, gold generates no earnings, dividends or coupons. Traditional discounted cash-flow models therefore have limited relevance. But this is also one of gold's defining strengths. Without an issuer, gold carries no credit risk and no counterparty exposure.
Its value is driven instead by a remarkably diverse set of demand sources: jewellery, technology, retail investment, institutional investment and central bank purchases.
This diversity gives gold what we often describe as its "dual nature".
During periods of economic expansion, rising incomes typically support jewellery demand and long-term household savings, particularly across Asia. During periods of uncertainty, investment demand tends to strengthen as investors seek diversification, liquidity and protection from financial stress.
So, unlike many assets whose fortunes depend on one dominant economic driver, gold benefits from multiple and often opposing sources of demand. Weakness in one segment or region can frequently be offset by strength elsewhere. That helps explain why gold has historically demonstrated resilience across a wide range of economic environments.
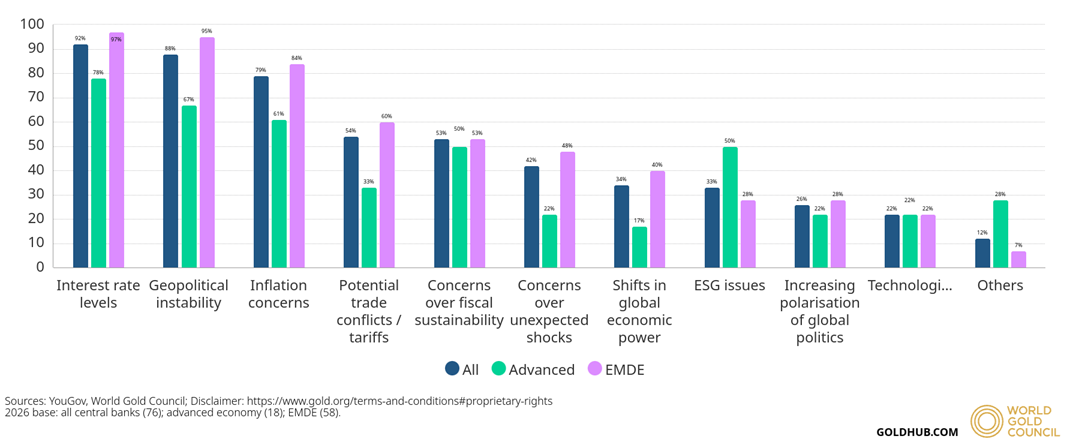
Q: What topics are relevant for your reserve management decisions?
Q: How relevant are the following factors in your organisation's decision to hold gold?
Looking beyond short-term price moves
Gold's performance during the first half of 2026 provides a useful illustration of these dynamics.
The metal briefly traded above US$5,500 an ounce before retreating sharply as markets reassessed interest-rate expectations, the US dollar and geopolitical developments.
Profit-taking after an exceptional rally also contributed to the correction.
Viewed in isolation, those moves might suggest gold's investment case has weakened.
The World Gold Council's 2026 Mid-Year Outlook suggests otherwise. Our analysis indicates that gold's current price broadly reflects today's macroeconomic consensus: moderate global growth, cooling but still elevated inflation, and expectations for only limited additional central bank tightening. Under those assumptions, gold may remain broadly rangebound during the second half of the year.
But markets rarely remain at consensus for long.
A deterioration in growth, renewed geopolitical shocks or a shift towards lower interest-rate expectations could provide renewed support for gold. Equally, stronger growth, higher real yields and improved investor confidence could create additional headwinds. History also suggests that periods of weakness often attract renewed buying from investors, consumers and central banks, helping to stabilise demand.
The point is not that one outcome is more likely than another. It is that gold's role does not depend on accurately predicting any single one.
Diversification when it matters most
For many years portfolio diversification relied heavily on the negative correlation between equities and government bonds. That relationship has become less reliable during periods of elevated inflation.
Recent market episodes have demonstrated that equities and bonds can sometimes fall (and rise) together, reducing the defensiveness of fixed income that many investors have come to expect.
Gold has historically behaved differently.
It has shown low or negative long-term correlation with equities, while also helping preserve purchasing power during periods of sustained inflation and heightened uncertainty. Analysis by the World Gold Council has also shown that even modest strategic allocations to gold can improve long-term portfolio efficiency by increasing risk-adjusted returns within diversified portfolios.
This goes to show that diversification is not simply about owning different assets. It is about owning assets that behave differently when it matters most.
A different question
For decades, the investment debate centred on whether portfolios needed an allocation to gold.
That debate is evolving, not because gold has enjoyed a strong rally, but because the world in which portfolios operate has changed.
Central banks appear to recognise that reality. They are not buying gold because they expect every geopolitical risk to materialise or every macroeconomic forecast to prove wrong. They are buying it because the range of possible outcomes has widened.
Investors may continue debating where gold goes next. The world's central banks appear more focused on how the world is evolving.
Shaokai Fan is Global Head of Central Banks and Head of Asia-Pacific (ex-China), at World Gold Council, a sponsor of Firstlinks. This article is for general informational and educational purposes only and does not amount to direct or indirect investment advice or assistance. You should consult with your professional advisers regarding any such product or service, take into account your individual financial needs and circumstances and carefully consider the risks associated with any investment decision.
For more articles and papers from World Gold Council, please click here.