Government bond markets today look very different from the low-yield environment that followed the global financial crisis. Across developed markets, for example, 10-year yields have returned to levels not seen for much of the past two decades.
Stronger nominal growth, persistent inflation and tighter monetary policy have driven much of the shift, while term premia have recovered from unusually compressed levels. Investors can once again earn income from high-quality government bonds, with higher starting yields providing some protection against further increases in interest rates.
Yet relatively high levels of income are also available from shorter-dated bonds. With market volatility high and bond-equity correlations positive, government bonds currently add to, rather than offset, equity risk. Geopolitical tensions leave markets exposed to further energy shocks, while fiscal pressure could push term premia higher.
The case for duration therefore depends on how much of the repricing is complete, what could push yields higher and whether weaker growth could turn the bond-equity correlation negative.
How much of the repricing is behind us?
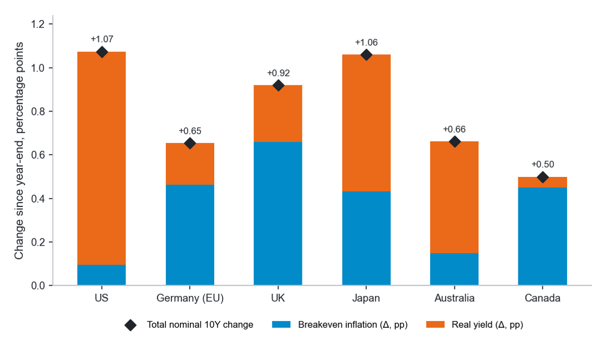
In the US, most of this year’s increase in 10-year nominal yields has come through higher real rates, rather than breakeven inflation. Oil supply shocks have added to near-term inflation pressure, while growth has remained resilient. With longer-term inflation expectations anchored, markets have responded by pricing a higher expected path for policy rates, in turn pushing up real yields. Elsewhere, the split between real rates and breakeven inflation has depended on domestic growth and inflation dynamics.
Figure 1: Real rates have been the key factor behind the recent rise in bond yields
Source: Fidelity International, Bloomberg, October 2026. For illustrative purposes only.
Note: Year-to-date change in generic 10-year nominal government bond yields decomposed into changes in 10-year real yields and breakeven inflation. Breakeven inflation calculated as nominal less inflation-linked yields.
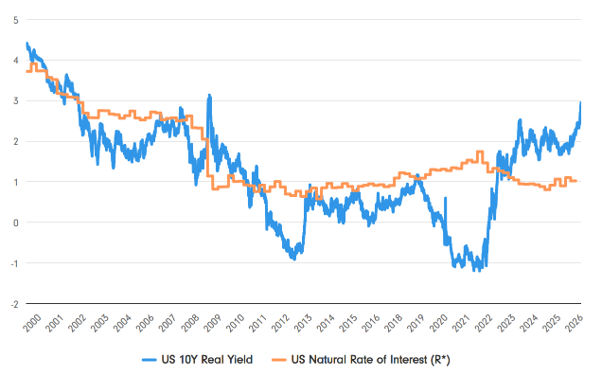
US 10-year real yields are now close to 3%, around their highest levels in 25 years and well above typical R* (the neutral real rate of interest that equilibrates the economy in the long run) estimates of around 1%. That is consistent with monetary conditions that may already be restrictive. From these levels, a further large rise in real yields would likely require stronger growth or more persistent inflation than markets are currently expecting.
Figure 2: Real yields are well above estimates of the neutral real rate
Source: Fidelity International, Bloomberg, October 2026.
Note: US 10-year real yield compared with the Holston-Laubach-Williams estimate of the US natural real rate of interest, (R*).
What could push long-dated yields even higher?
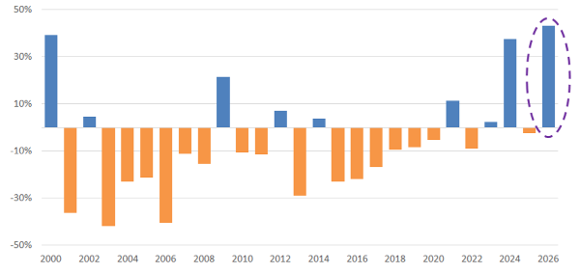
Another energy shock could still push real yields higher. The correlation between oil prices and US real yields has risen sharply in recent episodes. A larger or more persistent energy price shock could also begin to feed into longer-term inflation expectations, exerting upward pressure on nominal yields through both real rates and breakeven inflation.
Figure 3: Oil and US real yields have been unusually correlated this year
Source: Fidelity International, Bloomberg, September 2026. For illustrative purposes only.
Note: Calendar-year Pearson correlations of weekly changes in Brent crude oil with US 10-year real yields and 10-year breakeven inflation. Years with fewer than 40 weekly observations are excluded; 2026 is year to date.
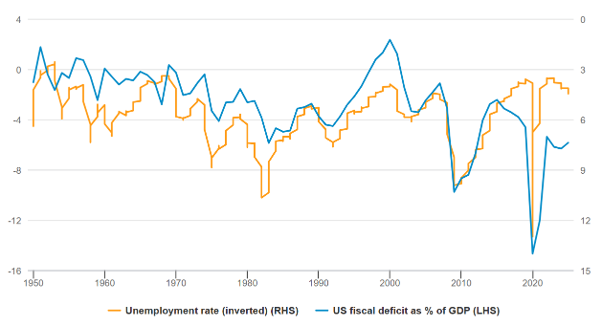
Fiscal policy is a slower-moving but important factor affecting bond yields, mainly through the term premium channel. In the US, the fiscal deficit remains around 6% of GDP even though the economy is close to full employment. That is unusual for this stage of the cycle and points to a more structural deficit problem. Debt held by the public is already around the size of annual GDP and, on current projections, is heading towards roughly 110% of GDP by 2030, increasing the amount of Treasury supply investors must absorb.
Figure 4: US deficits remain large despite a strong labour market
Source: Fidelity International, Marobond, U.S. Bureau of Labor Statistics (BLS), September 2025.
This is not an immediate debt-service problem because the effective interest rate on the existing debt stock remains below current market yields. But that buffer erodes as debt is refinanced. If yields stay high and deficits persist, interest costs rise, making debt stabilisation harder and keeping pressure on term premia. Fiscal sustainability concerns can be further amplified through the changing debt ownership structure. For example, US Treasury holdings have shifted towards more price-sensitive private investors and away from more price-insensitive holders, which could require a larger yield move to absorb additional supply.
AI investment adds another source of competition for capital. Hyperscaler and broader AI-related debt issuance is expected to rise further, while investment plans appear largely insensitive to borrowing costs. That additional supply could increase long-end yields’ sensitivity to issuance and exert upward pressure on term premia.
France brings fiscal risk into sharper focus
France’s 2026 deficit is now projected to be 5.4% of GDP, compared to prior expectations of 5%, after weaker growth, higher rates and inflation-linked spending. Beyond this, there are warnings that without consolidation the deficit could widen to 6.5% in 2027. The proposed budget requires a 1.2% of GDP primary structural consolidation just to return the deficit to 5%, still well above the European Commission’s 3% reference point. Passing that adjustment through a fragmented parliament ahead of the presidential election in six months’ time will be difficult. A watered-down budget looks the most likely route, while a rollover budget would bring more fiscal slippage and likely lead to continued uncertainty ahead of elections in spring.
The move in OAT-Bund spreads (the yield differential between comparable French and German government bonds) is a live example of the term-premium risk facing long bonds. Investors are pricing not only higher borrowing needs, but also the political difficulty of stabilising the deficit. For the European Central Bank (ECB), French spread widening on its own may be insufficient to justify intervention via their Transmission Protection Instrument, given the country’s weak fiscal position. The ECB threshold is more likely to be spread widening beyond France. If pressure reaches countries with better fiscal fundamentals, such as Spain, the issue becomes less about national fiscal risk and more about monetary policy transmission – possibly meriting intervention in the long-end of the curve.
A structurally higher term premium
A higher term premium is consistent with the macro regime embedded in our Capital Market Assumptions. These forces all raise the compensation investors require to hold long-duration government debt.
Our US fair-value model captures them through debt-to-GDP growth, Treasury holdings by price-insensitive investors, macroeconomic volatility and the convenience yield. It points to a medium-to-long-term equilibrium term premium of around 1%, well above much of the 2012–2019 period.
Figure 5: US term premium has widened, with long-run fair value around 1%
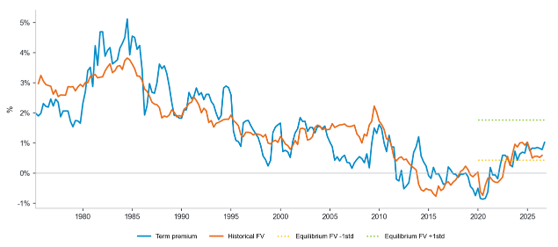
Source: Fidelity International, Bloomberg, Haver Analytics, September 2026. For illustrative purposes only.
Note: US 10-year term premium shown against historical and long-run equilibrium fair-value estimates. Historical fair value is estimated using Treasury holdings by US Banks’, federal debt/GDP, macroeconomic volatility and the Treasury convenience yield. Long-run equilibrium fair value is approximately 1.1%, with ±1 standard deviation of 0.66 percentage points.
That view also reflects our expectation that inflation and policy rates will settle above their 2010s averages. Term premia will continue to move through the cycle, but the unusually compressed levels of the post-GFC period are not the long-run anchor in our framework.
The role of duration in portfolios
Higher yields alone do not make a strong case for extending duration. Yield curves are relatively flat, and investors can earn substantial income from shorter-dated bonds. Volatility also remains high, and the bond-equity correlation is positive. On all three measures, conditions are unfavourable for duration.
Figure 6: All three key portfolio construction variables are unfavourable for duration risk
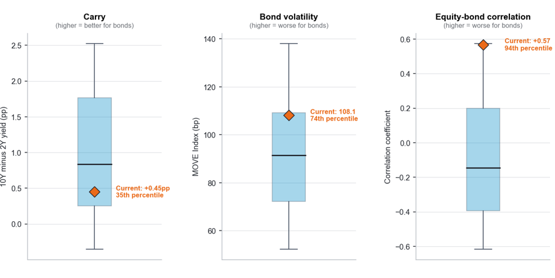
Source: Fidelity International, Bloomberg, October 2026. For illustrative purposes only.
Note: Distributions based on daily data from 1990 to present. Boxes show the 25th to 75th percentiles and whiskers the 5th to 95th percentiles. Carry is the US 10-year less 2-year Treasury yield; equity-bond correlation is the six month rolling correlation between daily S&P 500 price return and S&P 7–10 Year US Treasury total returns.
The case for duration would strengthen if growth became the dominant macro risk. A sharp weakening in activity would put downward pressure on policy-rate expectations and bond yields as equities weakened, making the bond-equity correlation more likely to turn negative. In that environment, duration could once again offset part of the equity drawdown.
A sharp repricing of expectations for AI-related capital expenditure and earnings is one possible trigger. US equity markets are highly concentrated in a small group of companies tied closely to the AI investment cycle. A large cut in expected spending or earnings could weaken both equity returns and the broader growth outlook, potentially prompting markets to price a lower policy path and pull real yields down.
Asset allocation implications
Higher yields improve income, but the right duration exposure depends on the dominant macro risk. Government bonds cannot be relied on to protect against inflation and energy shocks in the way they can against growth shocks.
Key takeaways
- Higher government bond yields have restored bonds as an important source of income, improving the outlook for prospective returns.
- Bonds are less reliable diversifiers when inflation, fiscal or energy shocks are driving markets and bond-equity correlations are positive, but duration can still provide an effective hedge against weaker growth.
- Investors should incorporate additional sources of diversification, including, for example, absolute return, market neutral strategies, gold and greater diversification within equity portfolios.
Salman Ahmed is Global Head of Macro and Strategic Asset Allocation; Stefan Rusev is a Senior Strategist, Global Macro and Strategic Asset Allocation; and Conor Parle is a Eurozone Economist at Fidelity International, a sponsor of Firstlinks. The views are their own. This content is issued by FIL Responsible Entity (Australia) Limited ABN 33 148 059 009, AFSL 409340 (‘Fidelity Australia’), a member of the FIL Limited group of companies commonly known as Fidelity and Fidelity International. This content is intended as general information only. You should consider the relevant Product Disclosure Statement available on our website www.fidelity.com.au.
For more articles and papers from Fidelity, please click here.
© 2026 FIL Responsible Entity (Australia) Limited. Fidelity, Fidelity International and the Fidelity International logo and F symbol are trademarks of FIL Limited.