Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 490

Doubling down on dividends

Market commentators love speculating on which direction markets are heading and when they’re likely to turn. But while expert speculators are loved by the media, they’re not much use to long-term investors. That’s because any experienced investor will tell you that it’s incredibly difficult to time the market – so you’re usually better off not trying. What you’re better off doing is looking at long-term fundamentals and trends, and making decisions on where you’re likely to get the best return in the medium to long term.

When we look at the data, we think that now’s the time to invest in income. Why?

Capital growth is likely to be lower in the next decade

Ultra-low interest rates and readily available, cheap, money drove a long bull market. With high inflation and rising rates, that era has passed. While markets may, or may not, perform well in 2023, what is very unlikely is that we’ll enter another long bull market with a similar amount of capital growth.

Rising interest rates are driving down company earnings and company valuations. Central banks in the US, Australia and elsewhere are adding further macro-economic headwinds by continuing to remove money from the economy via quantitative tightening.

These factors should drive lower capital growth in the medium term and it’s unlikely to be a smooth ride. Volatility may remain elevated in the near term. While this makes it a challenging market for investors, it also offers opportunity. With company valuations fluctuating, it’s a stock pickers’ market, with a great chance to pick up high-quality companies at bargain prices.

For us, with capital growth likely to be lower in the medium-long term, it’s the right time to place greater focus on income.

There are different ways to generate income from an equity portfolio. In IML’s Equity Income Fund we use three main streams for income: dividends, options and capital gains. We use simple options strategies to generate around 2% income yield from the portfolio – it tends to be a bit higher in flat or bear markets. We also generate up to 1% through realising capital gains – this is higher in bull markets, but we make sure we leave room for capital growth so investors can keep pace with inflation. And then we generate around 4% income yield through dividends. This diversity of income sources tends to give us a higher, and steadier, income stream paid quarterly. At the core, we still look to dividends from low-risk industrial stocks to generate the bulk of the income.

Dividends are likely to make up a greater share of total return 

For us, dividends have always been an important part of investment returns, but at times like these, their importance increases. There are two main reasons why:

  1. Dividends provide more reliable returns than capital gains
  2. Dividend yields can act as a ‘safety net’ at times of volatility

1. Dividends provide more reliable returns than capital gains

Returns from a share portfolio come from two sources – the capital appreciation from the shares, as well as the dividends received from each share. If you look at the table below showing returns from the ASX 300 over the last 20 years, you can clearly see how important dividends are to overall returns.
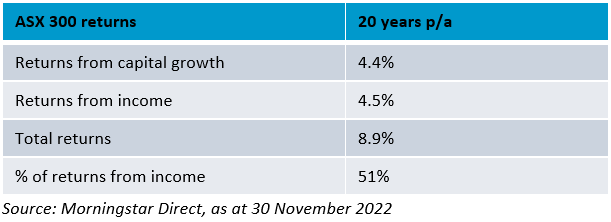
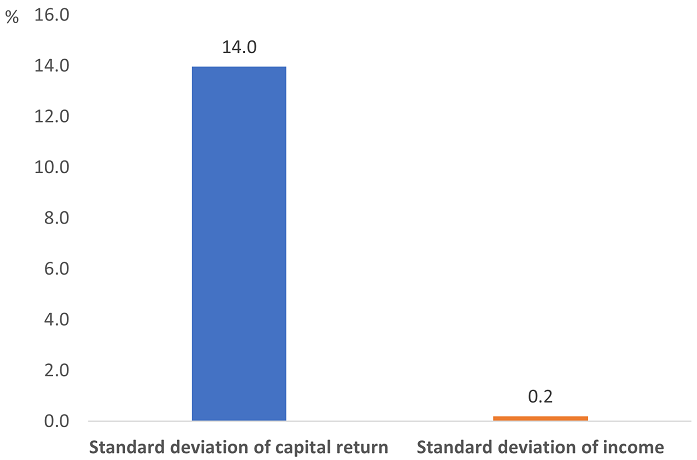
Over the last 20 years, dividends have returned 51% of overall returns. While this figure alone is evidence enough of dividends’ importance, it becomes more striking when you look at the volatility of these returns.

Volatility of returns of capital and income of the ASX 300 over 20 years
Source: Morningstar Direct, as at 30 November 2022

As you can see, return on capital fluctuates significantly, but dividend returns are remarkably reliable – making them particularly valuable when returns on capital are low, or negative.

While the level of capital returns from a share portfolio depends on movements in individual share prices, this is not the case for dividends. That’s because the level of dividends received by an investor is decided by the company’s board and is generally a reflection of the company’s overall profitability – its financial performance. So, in periods where the overall sharemarket goes down, an investor’s dividends should stay much the same if they have a diversified portfolio made up of quality companies.

2. Dividends can act as a ‘safety net’ in times of volatility

The movement in the sharemarket – particularly over shorter time periods of 6 to 12 months - is often dictated by investor sentiment. Sentiment can be erratic, impacted by anything from predictions of future levels of economic activity, to inflation and interest rates, or perceptions of geopolitical stability.

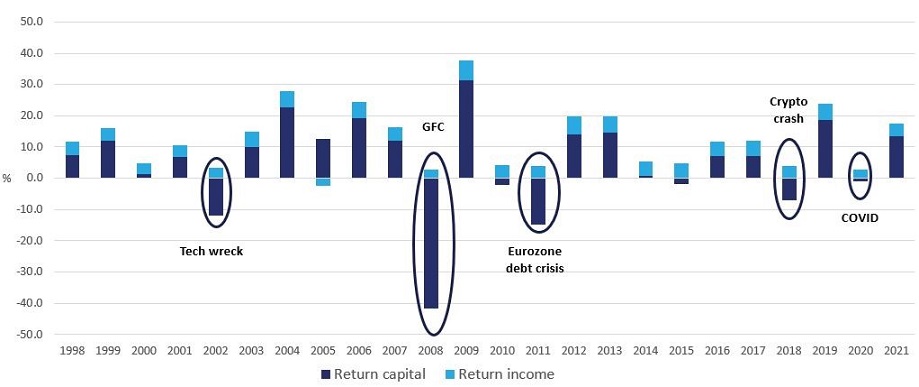
Take a look at this chart of ASX 300 returns over the last 20 years with the light blue bars showing dividends and the dark blue bars showing capital growth.

ASX 300 returns capital vs income
Source: IML and Morningstar Direct, S&P ASX300 01/01/1998 – 31/12/2021

You can see how important dividends were during those years where the ASX dropped significantly, or capital returns were lower. In the peak of the Tech Wreck in 2002 the ASX 300 provided a return on capital of -12% but dividends returned 3%.

  • In 2008, at the start of the GFC, capital dropped 42% but dividends returned +3%
  • In the 2011 Eurozone debt crisis capital returned -15% but income returned +4%

And while the sharemarket recovery from COVID was very swift, the ASX 300 still dropped 1% but income? It returned a steady 3%.

When the mood of the market is negative, stocks can fall heavily as investors and traders reduce their overall level of sharemarket exposure by rapidly selling shares - indiscriminately and independent of their quality. What we have observed over many years of investing is that once sentiment starts to turn, companies with sustainable earnings that support a healthy, consistent dividend stream are often the shares that recover the most quickly.

The reason for this is simple - rational, long-term investors are always attracted to companies that pay a healthy dividend from a sustainable earnings stream. They understand that the level of returns from dividends are not dependent on future share price performance. In other words, once shares in quality companies fall to a level where the dividend yield is attractive and sustainable, long-term investors buy them so they can ‘lock in’ high income levels, whatever happens to the sharemarket in future.

Which stocks and sectors are likely to pay the best dividends in future?

With the economic outlook uncertain and lower growth and high inflation likely to stick around for a while, it’s a good time for investors to think seriously about where they are likely to get the best income for the medium to long term. Investors should be cautious of overconcentrating in riskier sectors such as commercial property, resources, and other cyclical sectors.

We prefer industrials for long-term, consistently high dividends. We are also looking at which sectors and stocks are likely to perform well, and so provide a steady or growing dividend, in a high inflation environment. The types of companies that tend to perform well when inflation is high are companies:

  • With pricing power – their strong market position gives them the ability to pass on rising costs to their customers e.g., home and motor insurance companies like Suncorp (ASX:SUN).
  • In a rational industry – the main players are motivated by profit and act ‘rationally’ to maximise long-term profits – not spending large amounts of capital at the top of the cycle or chasing market share at all costs through unprofitable discounting. The explosives industry for example has rationalised significantly and is at a strong point in the capital cycle, benefitting companies like Orica (ASX:ORI).
  • That sell essential products and services – people need to buy them, no matter how high prices go e.g., consumer staples companies like Metcash (ASX:MTS).

In addition to the above, companies need to have capable, proactive management that can put well-structured contracts in place that make difficult conversations about passing on inflationary costs easier. Ideally, contracts are structured with adjustments for inflation and pass-through of essential input costs such as fuel. Aurizon (ASX:AZJ) benefits from such contractual protections. Here are some good examples of these types of companies, which also pay high dividend yields, and are currently trading at reasonable valuations:
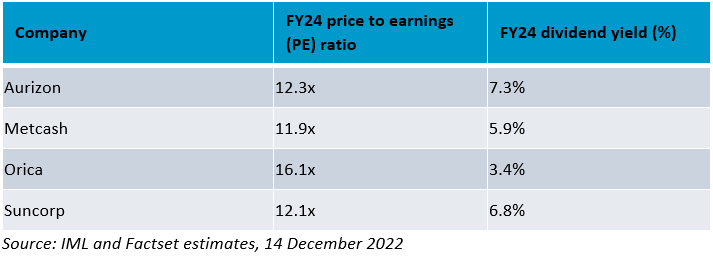
Finally, it’s worth bearing in mind the types of companies that benefit directly from rising rates. Good examples right now are Suncorp through its investment earnings and Aurizon through the return determined by the regulator on its regulated asset base.


Michael O’Neill is a Portfolio Manager at Australian equities fund manager Investors Mutual Limited. This information is general in nature and has been prepared without taking account of your objectives, financial situation or needs. The fact that shares in a particular company may have been mentioned should not be interpreted as a recommendation to buy, sell, or hold that stock. Past performance is not a reliable indicator of future performance.


  •   4 January 2023
  • 11
  •      
  •   
11 Comments
Rob
January 05, 2023

Always interesting that Analysts cannot quite get their heads around recommending the big Commodity names for dividends! Yes of course they can be cyclical but we are talking global giants with extraordinary competitive positions, extremely low debt and massive franking credit balances...

Their yields in recent times have topped 10% fully franked. Personal view, the only reason to avoid them for dividends. is that you believe their world is about to implode. Not so sure!!

Robert
January 05, 2023

And you suggest Rob ....?

Steve
January 09, 2023

Perhaps their record of inept capital management over many years is an issue. One of the first criteria noted when choosing an investment is "management quality". Although there seems to be some recent improvement I suspect many have been burned once too often. Remember high dividends imply an expectation of capital losses at some point.

Rob
January 06, 2023

All I suggest is u look hard at the numbers and do the comparisons accepting that past performance is no gtee (of anything!). BHP/FMG/RIO and others have all paid big dividends + buybacks + in Bhp's case a monster dividend in the WDS deal. They have "form" in paying out a high % of earnings. Beyond that it is always a question of your view of their underlying business.

The central point was that the investment community has always steered clear of recommending cyclical commodity companies for dividend income - always puzzled me as I think it lacks foundation!

Jim Carter
January 06, 2023

Very much appreciated. As seniors we lack the will to chase the growth train with the unrealistic values and volatility, so we are understanding the "value" of dividends, and any reference info that can help would be appreciated. ( if and when you can spare the time) Thank you

John Abernethy
January 08, 2023

One consistent conclusion drawn by analysts, projecting into the future, is that growth will slow and investment returns will be lower.

That cannot be said of the medium to long term outlook for Australia - and probably most of developing Asia.

We have abundant tradable resources and outputs across energy and agriculture. We are close to the fastest growing economies of the world and our population will increase by at least 15% over the next decade. Our growth is assured and will be superior to our western peers. We have abundant capital ( $3.5 trillion of super ) and a franking system that enhances returns. Our government is not highly indebted and our budget outcomes are also superior to our peers.

Economic growth, profit growth and therefore dividend growth is fairly assured over the next decade and the opportunity for patient investors to benefit is greatly enhanced by accessing market and/or price corrections.

I agree with Michael that a focus on the long term is important and there is no rush to invest. Steady accumulation that allows compounding of returns to occur is the key to investment success. Dividend paying companies with quality attributes are the best opportunity.

However, I do note the excessive negativeness that permeates through much mainstream commentary at present. The short term is always difficult to predict but the longer term economic growth is both predictable and assured.

To this point recent analysis has shown that the world economy has grown from $35 trillion GDP in 2000 to about $100 trillion in 2022.

Throughout that period we encountered internet bubbles, a GFC, and a European debt crisis, yet the world GDP has grown about 200%. After a well forecast slowdown in 2023 it would be folly to suggest that growth will not re-emerge and probably sooner than many currently suggest.

Jack
January 09, 2023

It is difficult to understand why more retirees don’t use dividends as the basis of their retirement income. As this article demonstrates, the volatility of income from dividends is very low and retirees need predictable income to meet their ongoing liabilities. Secondly, because retirees often have low or zero marginal tax rates they benefit from the extra income provided by franking credits that come with dividends from Australian companies. For example the before-tax dividend yield from Aurizon may be 7.3%, but the after-tax yield is in excess 10%. Certainly, the market value of a portfolio of shares can be volatile. It may be uncomfortable to watch when everyone else is focused on share prices but, if investing long-term for income, that price volatility has little bearing on the income it produces, but retirees also benefit from long term rise in share prices. But if you want/need to sell, it is much more liquid than property. Shares can be sold in small parcels, rather than the whole property. Even part-age pensioners can use this strategy. With SAPTO, they pay little or no tax. If they are assets-tested their income is deemed and anything above the deemed rate is ignored. So they can receive a part pension and very generous income from their dividends.

Jack
January 08, 2023

It is difficult to understand why more retirees don’t use dividends as the basis of their retirement income. As this article demonstrates, the volatility of income from dividends is very low and retirees need predictable income to meet their ongoing liabilities. Secondly, because retirees often have low or zero marginal tax rates they benefit from the extra income provided by franking credits that come with dividends from Australian companies. For example the before-tax dividend yield from Aurizon may be 7.3%, but the after-tax yield is in excess 10%. Certainly, the market value of a portfolio of shares can be volatile. It may be uncomfortable to watch when everyone else is focused on share prices but, if investing long-term for income, that price volatility has little bearing on the income it produces, but retirees also benefit from long term rise in share prices. But if you want/need to sell, it is much more liquid than property. Shares can be sold in small parcels, rather than the whole property. Even part-age pensioners can use this strategy. With SAPTO, they pay little or no tax. If they are assets-tested their income is deemed and anything above the deemed rate is ignored. So they can receive a part pension and very generous income from their dividends.

Brian
January 08, 2023

In my view retirees like ourselves should have a significant investment in bank hybrids which are currently paying +6% when franking credits are included, even when interest rates were near zero most were paying 3-4% with franking included. Although there is little capital growth there is also little capital loss provided they are traded as they approach their maturity into relatively new issues. This has provided us with a consistent income stream over many years and the GFC indicated how robust they are, losing value over the short term but quickly recovering, indeed providing significant capital gain for those brave enough to buy at that time.
Certainly there is opportunity with some of the companies mentioned and a significant number of others.
As well with the exception of lithium there is clearly opportunity in battery metals viz nickel, graphite, copper etc which havent yet had much investor consideration but they must ultimately gain in value as lithium cant produce batteries on its own!, a little speculative but clear opportunity with the electrification of the world.

Mark
January 24, 2023

I'm about 5 years from retiring and I am slowly looking to move out of some of my growth shares into dividend paying shares to start an income stream from Super paid for from dividends.

I am also waiting to see what happens with the coming, defining the purpose of Superannuation talk that is to occur and the likely follow up with moves on high balance Superannuation accounts. This may well impact my investment retiring strategy as well.

Steve Dodds
February 02, 2023

I recently retired. Until about a few years ago I was a proponent of growth and total return to provide income.

Fortunately at that time I switched my (quite large i guess) portfolio to a dividend focus. And sold all my bonds as part of it.

Yes, my timing was lucky.

And I don’t expect the 9.86% dividend return (thanks to GEAR, which not only multiplies gains and losses but also multiplies dividends, VHY and others) to continue, but even a return to 5-6% means I shouldn’t have to sell a share again except for tax harvesting or fun.

I think Thornhill and co are a bit simplistic, but if I’d needed to sell shares or bonds over the zig zaggy market for income I’b be miffed.

I’ll continue to transfer whatever I can into my super for even better tax treatment of income but I have yet to need to start tapping it.


Leave a Comment:

RELATED ARTICLES

Three reasons why current dividends matter

The role of shareholder yield in a portfolio

The challenges with building a dividend portfolio

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.