Companies that are reliable dividend payers are not just good income providers for investors, they have historically been better at delivering consistent returns and weathering challenging and uncertain market conditions.
As such, a dividend-focused global investing strategy may help investors maintain equity exposure while also managing risk, something which is increasingly important in current market conditions given geopolitical uncertainty and growing concerns about an AI bubble.
The main drivers of equity market returns are dividends, earnings and price-to-earnings (PE) ratios. The below chart shows that PE ratios have historically expanded and contracted over periods of time and do not actually contribute much to total return. Instead, the bulk of returns come from earnings per share (EPS) growth, with dividends also a significant source. While the impact of dividends has declined somewhat since the early 1990s, it has remained positive (unlike valuations).
The reason the contribution from dividends appears to have decreased in recent decades is also due to major regulator changes in the US that made share buybacks a tax-efficient alternative to cash dividends. But share buybacks are still a mechanism for returning cash to shareholders and driving EPS growth.
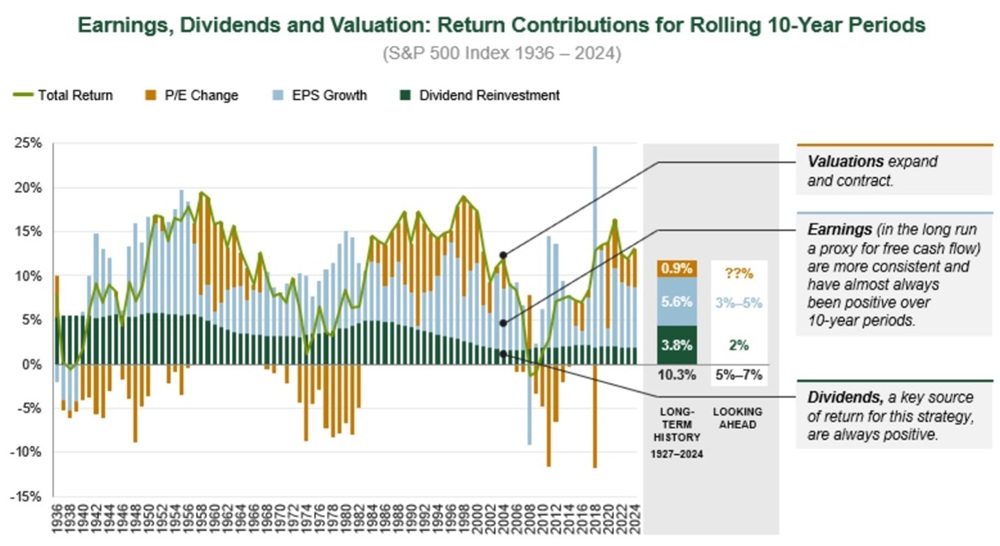
Source: TD Epoch, Standard & Poor’s as of 31 December 2025. US historical data is used as a proxy for global markets because similarly detailed data is not available for non-US markets.
Finding good payers
The question for investors then becomes how to find such reliable income payers. Firstly, investors need to focus on a company's free cash flow. To do so it can be helpful to try and think like a CFO would think. For example, consider questions such as how the company is generating cash flow, is it from reliable sources or one-off injections that are unlikely to repeat. Also, how is the company allocating that cash back to shareholders. These macro questions can be more important than focusing on accounting-based metrics such as price-to-earnings or price-to-book, as those metrics can be manipulated.
In terms of what a company can do with free cash flow, they can of course reinvest it in the business or make acquisitions, and if a company is earning above its cost of capital, it should be pursuing such strategies to grow its value. However, there is not always an unlimited supply of opportunities to do so.
When it cannot find attractive investment opportunities, a company should be returning that cash flow to investors, something it can do via dividends, share buybacks, or debt reductions.
Volatility screen
A positive consequence of building a portfolio focused on shareholder yield can be lower volatility. As the chart above highlights, dividends have consistently been a positive contributor to equity market returns.
To find a company that pays consistent dividends you need to find one that can generate sustainable free cash flow. A good start in identifying such an organisation is finding a company that pays attractive current dividends today. Those dividends also need to be coming from a reoccurring source of cash, and those cash flows should also ideally be growing. There needs to be a commitment from management to consistently returning cash to shareholders through dividends or other means. You don't want to invest in a company in the habit of cancelling dividends or reducing them.
It's also important to look at how a company generates their cash flow and how that capital is allocated. A company with growing revenue has a different outlook to one where cash flow is coming from a cost-cutting story. Both trajectories may be positive for cash flow in the short term but only increasing revenue will see better cash flow in the long term.
Unsurprisingly, these are all characteristics of companies that tend to trade with lower volatility, performing in both good times and bad, which have historically contributed to lower overall volatility in a portfolio. They also make a yield-seeking strategy particularly attractive in the current environment.
The example of Cisco
One company we think embodies all these factors is Cisco Systems (NASDAQ: CSCO). It is in the top 10 holdings in the Epoch Global Equity Shareholder Yield (Unhedged) Fund. It had the second highest portfolio weight of 2.4 per cent in June 2026 and is also providing a dividend yield of 1.4 per cent to the portfolio.
Cisco Systems was established by computer scientists in the early 1980s to build systems and servers that could connect and share information between disparate networks. Today it has a growing stream of recurring service revenues across networking, security and collaboration.
These new revenue streams are supporting cash flow growth and require lower capital expenditure. Returning cash to investors is also a priority. For the twelve months ending April 25, 2026, the company returned $US11.3 billion to stockholders through share buybacks and dividends, from a total $US13.0 billion cash flow from operating activities.
The end game
Equities have endured dynamic and often unpredicted market conditions recently. Companies have had to navigate a landscape defined by tariff uncertainties, volatile interest rates, and geopolitical shocks. Longer-term structural shifts, such as deglobalisation and the realignment of supply chains, have further added to the complexity of the environment.
Against such a backdrop, we believe a shareholder yield strategy can capture the productivity of a growing economy, while remaining defensively positioned for resiliency, if growth were to begin to falter.
Kera van Valen is a portfolio manager at TD Epoch, a fund manager partner of GSFM, a Firstlinks sponsor. The information included in this article is provided for informational purposes only.
For more articles and papers from GSFM and partners, click here.