Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 310

5 flexible features of Managed Accounts

About half of Cuffelinks readers engage the services of financial advisers to help them manage their life savings. Most will meet with their adviser, review their portfolio and then listen to their adviser’s recommended changes to these portfolios. This process of managing client money is old-fashioned, clunky and reactive. There is a better way.

Acceptance of Managed Accounts

Managed Accounts have been around for a while but over the last few years their popularity has soared, not only in Australia, but also in the UK and the US. There is good reason for this as the benefits of using Managed Accounts are significant and varied. According to the 2019 Netwealth Advice Tech Report, 43% of advice firms now use Managed Accounts to run part of their client portfolios, up from 35% in 2017. A recent IMAP/Milliman survey revealed that $62 billion of client funds are now managed via discretionary portfolio methods, double the level of just three years ago.
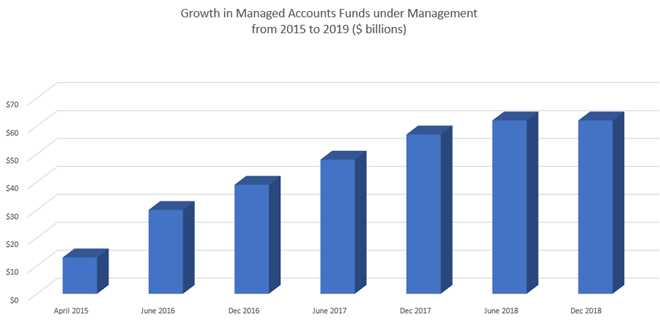
Source: IMAP Milliman

A Managed Account in its simplest form is an auto-rebalance tool. It permits the advice firm discretion to make changes to their clients’ portfolios without requiring their written approval. This is how superannuation monies are managed in industry and retail funds. The manager has strict limits on the amount of risk that can be taken and the type of assets that can be purchased, and must adhere to these limits.

The Managed Account benefits

Managed Accounts offer a range of benefits that offer clients and their advisers increased flexibility.

First, the money is managed by a professional investment committee, rather than by an adviser who occasionally reads the Fin Review and a stock-tipping sheet. While portfolio outperformance is not guaranteed, the likelihood of things going badly wrong are reduced.

Second, the client’s funds are managed in a much more proactive manner as portfolio changes can be made in an instant. Contrast this with the traditional process where changes were generally only made at the client meeting, which may happen just once or twice a year.

Third, Managed Accounts are more progressive and egalitarian than the traditional way of managing money. Currently, if changes need to be made, it’s inevitably the adviser’s larger clients who will be called first. With a Managed Account, all portfolios of the same risk profile are changed at the same time, which also offers scale benefits.

Fourth, Managed Accounts are transparent. Portfolio performance is published each month and is benchmarked against an equivalent risk profile. There is no hiding, obfuscation and evasiveness. “How are we doing?” is now easier to answer. We benchmark our clients' portfolios against their CPI+ targets and against a basket of comparable portfolios every month.

And fifth, with advisers freed from the tyranny of trying fruitlessly to add value by picking BHP over CBA, they can actually get on with the job of providing strategic financial planning advice, focussing on the clients' wealth plan and helping them achieve their important goals in life.

Sounds good so far.

Are there any disadvantages?

Yes. A Managed Account run by a professional investment committee will likely charge a portfolio fee. This is typically in the region of 0.2% - 0.3%, though lower rates are commonly offered for larger portfolios. This is an additional cost. However, most Managed Account providers are able to recoup most, if not all, of this cost in two ways.

First, by negotiating lower management expense ratios (MERs) from fund managers. With scale comes lower fees, and Managed Accounts offer scale. It’s important to check that your provider passes these rebates on to you, the client, in full. And second, many Managed Account providers are now offering lower financial advice fees if client portfolios are run in a discretionary manner, due to the reduced administrative burden.

It might be time to talk to your adviser about Managed Accounts. They are not suitable for everyone, but they are a big part of the future of advice.


Jonathan Hoyle is Chief Executive Officer at Stanford Brown. This article is general information and does not address the circumstances of any individual.


  •   12 June 2019
  • 2
  •      
  •   
banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.