Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

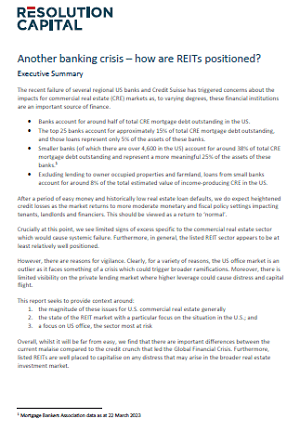
Another banking crisis – how are REITs positioned?

Executive summary

The recent failure of several regional US banks and Credit Suisse has triggered concerns about the impacts for commercial real estate (CRE) markets as, to varying degrees, these financial institutions are an important source of finance.

  • Banks account for around half of total CRE mortgage debt outstanding in the US.
  • The top 25 banks account for approximately 15% of total CRE mortgage debt outstanding, and those loans represent only 5% of the assets of these banks.
  • Smaller banks (of which there are over 4,600 in the US) account for around 38% of total CRE mortgage debt outstanding and represent a more meaningful 25% of the assets of these banks.
  • Excluding lending to owner occupied properties and farmland, loans from small banks account for around 8% of the total estimated value of income-producing CRE in the US.

After a period of easy money and historically low real estate loan defaults, we do expect heightened credit losses as the market returns to more moderate monetary and fiscal policy settings impacting tenants, landlords and financiers. This should be viewed as a return to ‘normal’.

Crucially at this point, we see limited signs of excess specific to the commercial real estate sector which would cause systemic failure. Furthermore, in general, the listed REIT sector appears to be at least relatively well positioned.

However, there are reasons for vigilance. Clearly, for a variety of reasons, the US office market is an outlier as it faces something of a crisis which could trigger broader ramifications. Moreover, there is limited visibility on the private lending market where higher leverage could cause distress and capital flight.

This report seeks to provide context around:

  1. the magnitude of these issues for U.S. commercial real estate generally
  2. the state of the REIT market with a particular focus on the situation in the U.S.; and
  3. a focus on US office, the sector most at risk

Overall, whilst it will be far from easy, we find that there are important differences between the current malaise compared to the credit crunch that led the Global Financial Crisis. Furthermore, listed REITs are well placed to capitalise on any distress that may arise in the broader real estate investment market.

Download the full paper
  •   4 May 2023
  •      
  •   


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.