While Australian super funds typically hold meaningful allocations to real assets, many self-directed investors remain concentrated in listed shares, cash and property.
According to the latest figures, as at December 2025, around 73% of all self-managed super fund (SMSF) assets were held in just five asset classes: listed shares (27%), cash and term deposits (17%), unlisted trusts (12%), non-residential property (10%) and limited recourse borrowing arrangements (7%) (Source: ATO).
While that concentration has worked well through a long bull market in equities, it also means many portfolios are heavily exposed to the same set of risks. Though no asset is entirely immune to the broader economic cycle, real assets introduce differentiated return drivers that can help create portfolio resilience when traditional asset classes face drawdowns.
So, how should investors approach an allocation to real assets?
What are real assets?
Real assets are tangible, physical assets with intrinsic value derived from their utility.
What distinguishes real assets from listed equities and bonds is the source of their returns. While public market prices can be significantly influenced by investor sentiment in the short term, mature real asset valuations are typically linked more closely to the income generated by the underlying asset.
A toll road collects fees, a warehouse collects rent and a water entitlement generates lease income.
In infrastructure and real estate, these cash flows are often secured through long-term contracts and are structured to provide strong inflation protection. Inflation linked leases, for example, are far more common in the real estate market now than they have been historically.
Why the attention now?
Large institutional investors have long allocated to private markets, including real assets, seeking diversification, inflation protection and exposure to sources of return that differ from listed equities and bonds.
One objective of these allocations is to reduce dependence on public equity and bond market returns, although outcomes vary by institution and market cycle.
Retail and wholesale investors, by contrast, have remained heavily concentrated in listed equities and bonds, largely because access to private and real asset markets was historically restricted to large institutional investors that have the scale, patience and governance to invest in these asset classes. Compared with many institutional portfolios, adviser-directed and self-directed portfolios often have less exposure to private markets and real assets, remaining structurally under-diversified.
Real assets help bolster portfolio diversification because their return drivers are genuinely different from those of listed equities and bonds. They allow investors to access a different set of structural premia, such as inflation-linked cash flows, the illiquidity risk premium and others.
Furthermore, because they are operationally intensive physical assets, their performance is highly dependent on manager skill, which can have a significant impact on an asset’s return profile.
These asset classes are also benefiting from powerful structural tailwinds: in 2026, institutional investors have been targeting real assets that benefit from secular themes such as digitalisation, decarbonisation and demographics.
A key example is the surge in investment in renewable energy generation, energy storage and transmission infrastructure to ensure reliability and decarbonisation as the coal fleet exits (Source: Palisade Impact).
The role of real assets in portfolios
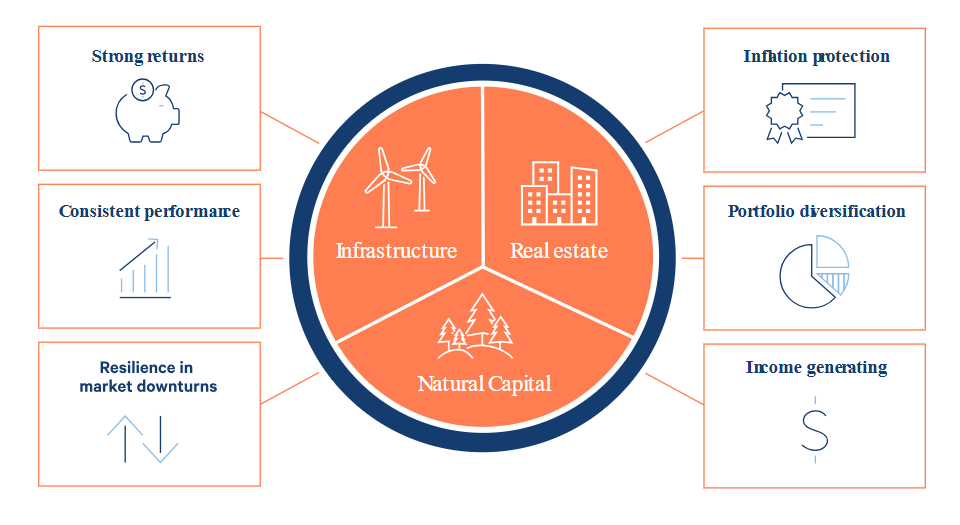
Real assets earn their place by delivering key benefits to a portfolio, as shown in the figure below.
- Income Generation: many strategies generate a reliable yield from rents or usage fees, which can be attractive for investors transitioning towards drawdown or needing a reliable source of income.
- Inflation Protection: many regulated and contracted assets, together with assets under long-term leases frequently embed inflation-linked pricing, so revenues rise with inflation rather than being eroded by it.
- Portfolio Diversification: because returns differ from those of listed equities and bonds, some real asset sectors have historically exhibited lower correlations with public markets.
Figure 1: How can real assets optimise an investor’s portfolio?
Source: Wilson Asset Management
A modest but deliberate allocation to real assets may improve the resilience and durability of an investment portfolio.
The risks
While the benefits of real assets are compelling, investors must be aware of the structural trade-offs involved:
- Liquidity: Unlisted real assets cannot be sold at the click of a button; vehicles typically offer periodic, capped withdrawals, and investors should treat the allocation as long-term capital. This reflects the underlying asset types, such as airports, office buildings, laboratories and farms, which are significantly harder to sell than listed equities and bonds.
- Valuations are less frequent and rely on appraisals rather than live market pricing, which dampens reported volatility, but means values can lag listed markets.
- Gearing can amplify both returns and losses, so the level and structure of borrowing matter (including any duration mismatch between the asset type and debt financing).
- Fees are generally higher than for listed products, and in fund-of-funds structures investors should understand the total cost across both layers. Transparency is therefore critical.
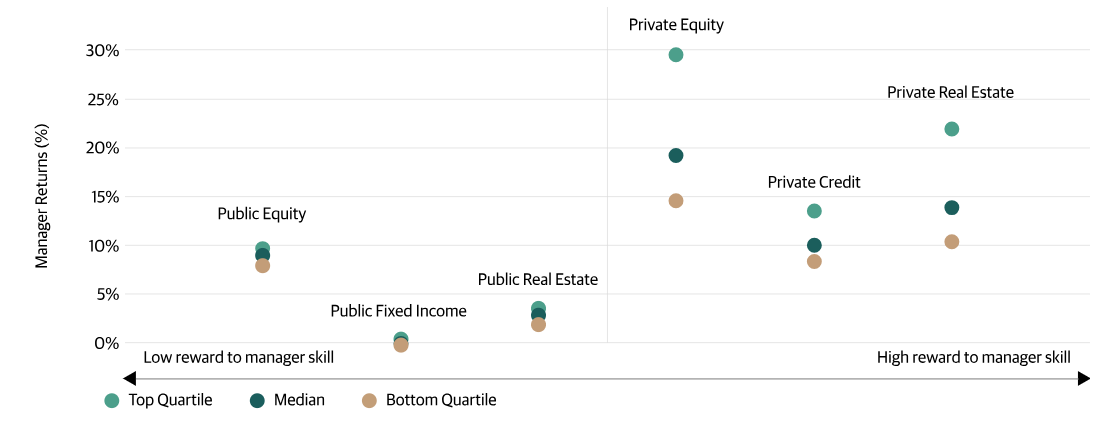
- Manager skill and asset selection drive outcomes far more than in efficient listed markets; as competition has pushed up pricing, choosing skilled value-adding managers who can develop and operate assets is essential to generating returns. Dispersion between strong and weak managers in private markets is significantly wider than in public equities (Source: JP Morgan).
Navigating structural dispersion in private markets
The point about manager skill deserves more than a passing mention, because it is a defining feature of real assets and a key driver of dispersion across the asset class. Figure 2 illustrates the clear dispersion between top and bottom quartile manager returns for private real estate compared with public real estate.
More recently, this dispersion has been driven by a divergence in sector performance. Globally, traditional assets such as standard office towers and high-street retail have struggled under higher interest rates, repricing and structural vacancy, while sectors aligned with durable demographic and digital demand, such as logistics, data centres, student accommodation and healthcare property, have continued to deliver income growth.
Given the dispersion of returns across managers, manager selection can be a significant determinant of long-term outcomes.
Figure 2: Range of outcomes across private managers and public managers
Source: Blackstone
Five questions to ask before allocating
For investors and advisers approaching real assets, we think there are a few questions to ask managers before investing in the asset class. This list is not exhaustive:
- What is the underlying exposure? Which sectors, geographies and asset types does the manager invest in and do they match the diversification you are seeking? Does the investment duplicate existing exposure or fill a gap in the portfolio?
- How is income generated and how durable is it? Is the income contracted, regulated, inflation-linked or market-dependent?
- How often are assets valued, and by whom? Independent, frequent valuations are preferable to infrequent, internally determined valuations.
- What liquidity is available? Understand the fund’s withdrawal terms and assume that you may need to hold the investment through a full cycle.
- How is the manager constructing the portfolio? Asset sizing and deliberate diversification across different asset types with distinct economic drivers, matter far more than any single asset’s individual appeal. For example, within real estate, diversification across office, retail and industrial assets is critical. Office exposure is largely tied to employment and unemployment trends, retail assets provide exposure to discretionary spending and industrial property is supported by structural economic and GDP growth drivers.
Concluding thoughts
Real assets have long played an important role in institutional portfolios and are becoming increasingly accessible to individual investors and SMSFs.
While they are not a substitute for equities or bonds, they can broaden the opportunity set available to investors seeking diversification, income and inflation protection. The challenge is to balance those benefits against the trade-offs of liquidity, fees and manager selection risk.
For long-term investors, real assets deserve serious consideration as a distinct and durable diversifier.
Nick Kelly is a portfolio manager of WAM Alternative Assets (ASX:WMA) and the recently launched Wilson Asset Management Real Assets Fund (ASX:WRAF), which provides exposure to an actively managed portfolio of Australian and global real asset strategies across real estate, infrastructure and natural capital.
This information has been prepared and provided by Wilson Asset Management in good faith. However, no warranty (express or implied) is made as to the accuracy, completeness or reliability of any statements, estimates or opinions or other information contained in these materials (any of which may change without notice). To the extent that it includes any financial product advice, the advice is of a general nature only and does not take into account any individual’s objectives, financial situation or particular needs. Before making an investment decision an individual should assess whether it meets their own needs and consult a financial advisor.