Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 681

Under-retiring: The greatest retirement risk in a generation

Retirement requires a fundamental shift – to our lifestyles, finances, and mindset. After a lifetime of saving, we shift to decades of spending. This is a change that doesn’t come naturally for many of us. As we live longer, with retirement now spanning thirty years for the average Australian, knowing how much money we will need to fund our post-work years has become a mounting challenge.

With 250,000 Australians stepping into retirement every year, it is imperative to understand how spending expectations of Australians change as they approach and enter retirement. To do so, I partnered with retirement income provider, Challenger, to survey more than 1,000 Australians aged 60 to 80 with superannuation balances over $100,000.

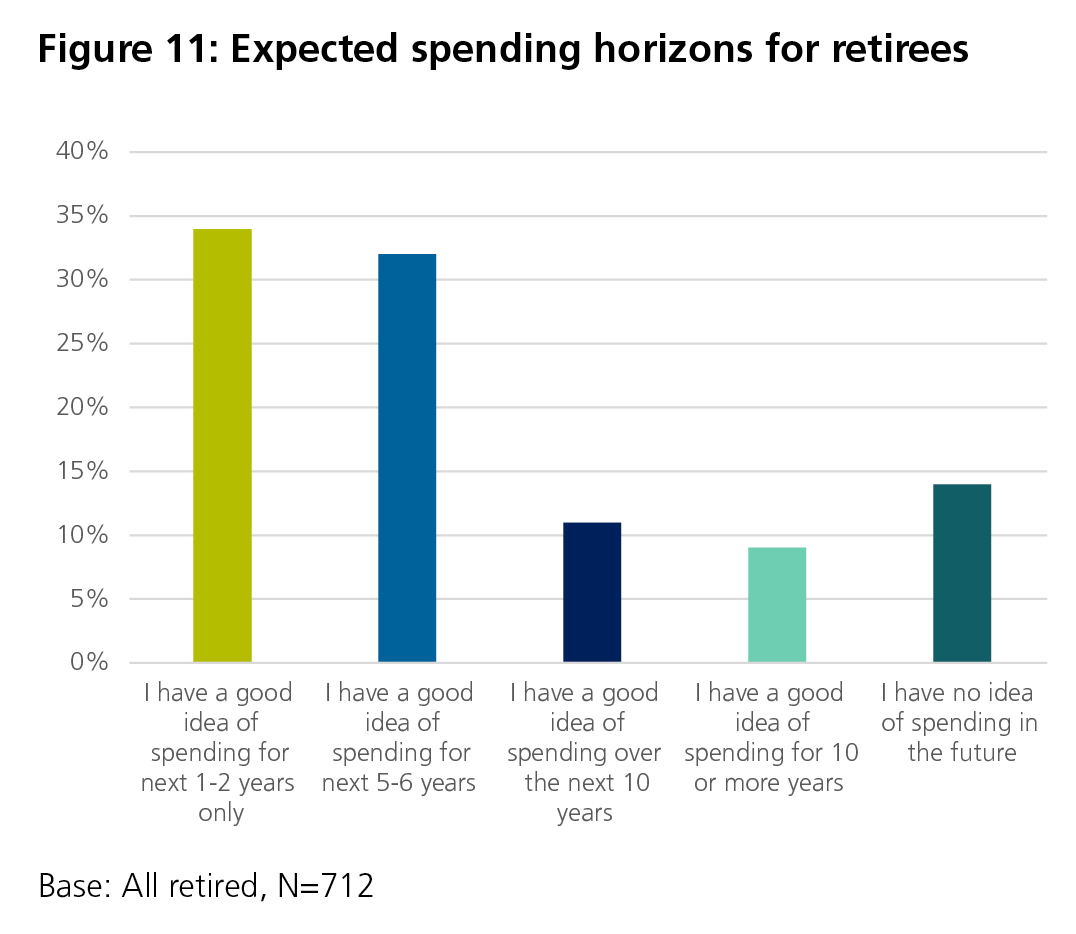
While a third of retirees (34%) were able to confidently predict their spending in the next one to two years, this figure fell to just 1 in 10 (11%) when asked to predict over the next decade. Concerningly, 14% of retirees and 19% of pre-retirees had no idea about future spending over any time horizon.
Fears were more pronounced for pre-retirees, with uncertainty over the future leading to concerns that money would run out (46% pre-retirees v 21% retirees), worries about unexpected health and aged care costs (45% pre-retirees v 26% retirees), and concerns about having enough money for daily living expenses (30% pre-retirees v 12% retirees).

Retirement is a significant stage of life that can last for decades. Understanding our spending habits is critical to informing how much retirement savings we will need.

It has been said for many years that retirees are under-spending to leave an inheritance for their children. Our research found this to very much be an oversimplification. For many, they underspend as they worry they may have no savings left when they get older.

Ultimately, the research revealed that spending came down not to your superannuation balance or the value of your home, but to your retirement mindset. We need to give more Australians the confidence to enjoy retirement.

There is no one uniform lifestyle in retirement

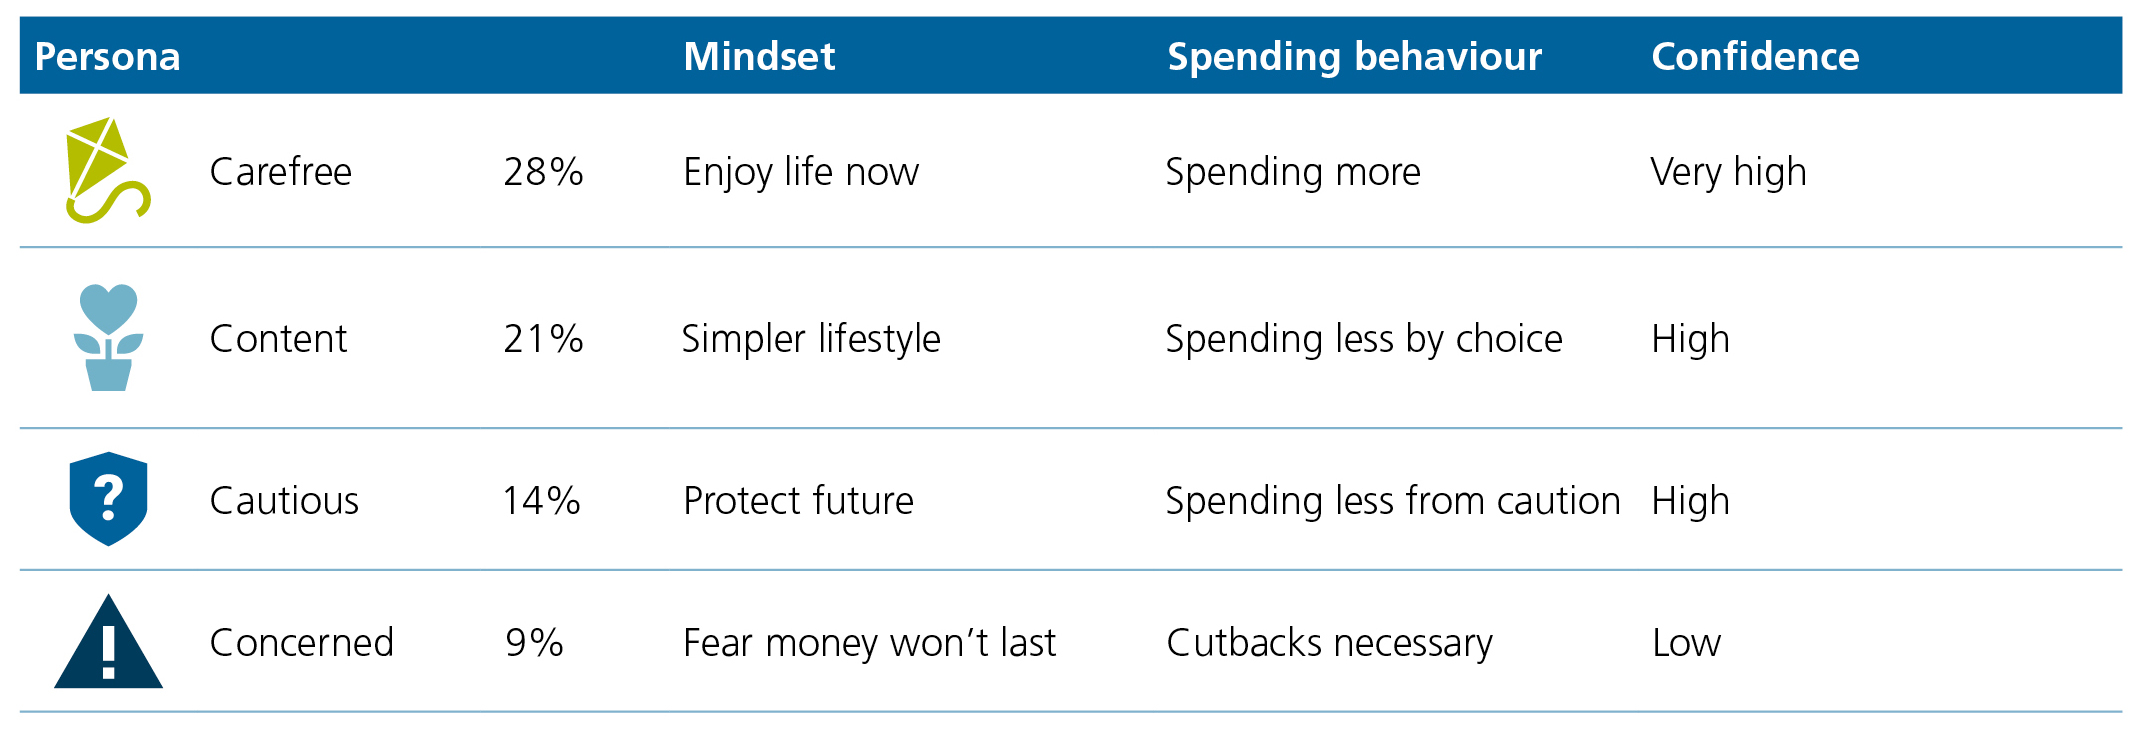
While 82% of retirees are confident they can afford their desired retirement lifestyle, the confidence to spend varies significantly depending on your mindset, with the research uncovering four distinct retirement personas:

Carefree: retirement is a time of freedom. Almost 30% of respondents identified as Carefree, focused on enjoying life – travelling, socialising with friends, and spending time with grandchildren while unburdened by financial concerns.

Content: a lifestyle enjoyed by around 20% of respondents, who chose a simpler retirement and to spend mindfully. Importantly, this group is spending less by choice and remains confident their savings will last for life.

Cautious: these respondents (15%) were careful with their money due to uncertainty it will last. While only half expected to have superannuation left for their estate, three quarters (74%) were confident they could afford their lifestyle. Cutting back on spending helped this group to navigate the unexpected.

Concerned: These retirees had a genuine fear of running out. Approximately 10% of respondents were living on a tight budget out of necessity, surviving on much less income than they used to. Many with this lifestyle are reliant on the Age or Disability Pension, with higher living costs compounding the challenge.

Positively, half of Australian retirees are living a Carefree or Content lifestyle, enjoying retirement on their terms and choosing to spend on the things that matter to them most. However, what we found amongst these cohorts was that people with remarkably similar financial circumstances were often making very different decisions about how they wanted to live in retirement.
Potentially, some may be ‘under-retiring’ in that they may be living a more constrained lifestyle than they need to be. Many Australians with good superannuation balances don’t have the confidence to spend it.

Time to reframe the retirement advice conversation

One of the clear lessons from our research is that retirement is a dynamic life stage, not a time when people set-and-forget. Spending patterns in retirement are not static and retirees can shift between lifestyle personas as priorities change over the retirement lifecycle.

For some retirees, the confidence to spend grows as they settle into this new lifestyle. For others, they report cutting back as circumstances, such as health, change.
And as their mindset shifts from saving to spending, many are still looking for guidance and advice to help navigate the decades of retirement.

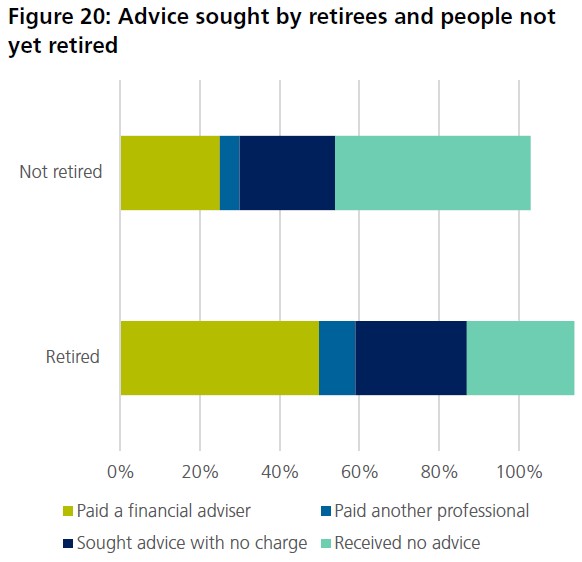
Three quarters of retirees (73%) and more than half of pre-retirees (51%) reported that they had previously received financial advice – paid or unpaid. Of these, 55% of retirees, and a staggering 71% of pre-retirees, felt there were other new topics worth getting advice or guidance on.

For those who had never sought help or advice, 48% of retirees and 78% of pre-retirees could nominate a topic they wanted support with.
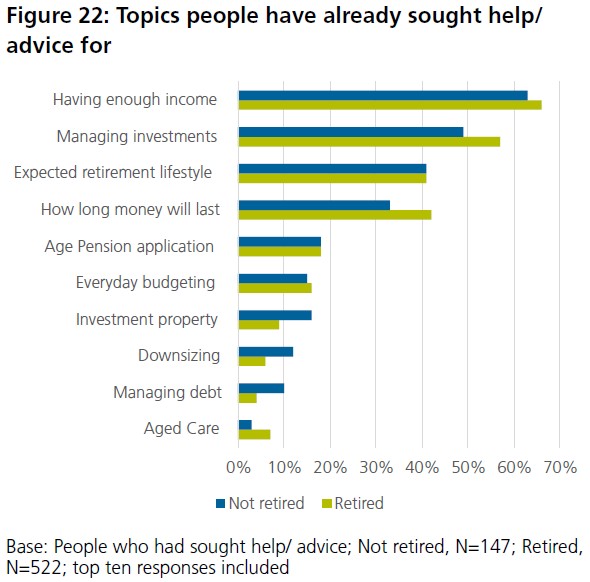
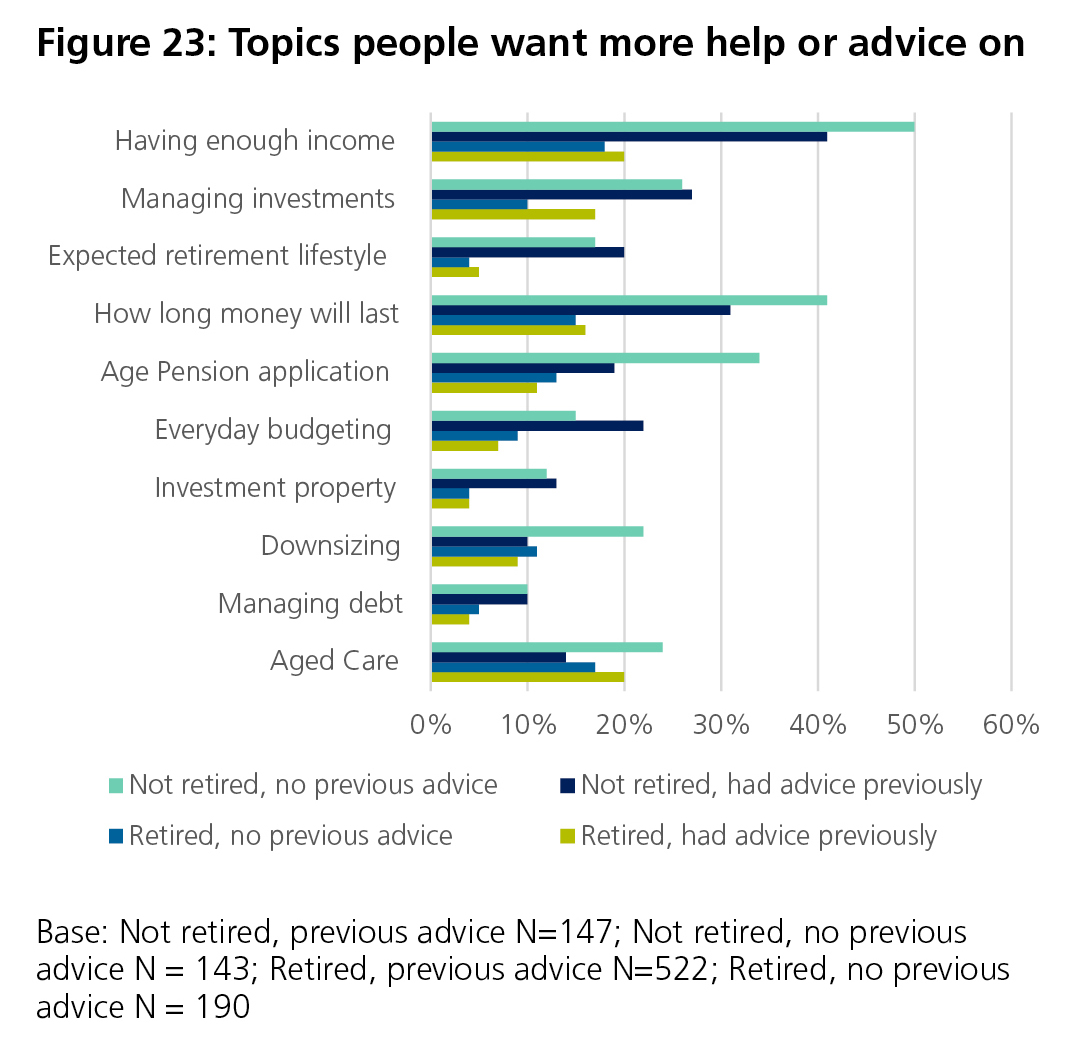
 

The lesson for retirees, and their advisers, is to reframe retirement conversations around lifestyle preferences rather than balances.

Five takeaways for retirees and their advisers

Here are my five key takeaways from my discussions with today’s older Australians:

  1. The right mindset makes all the difference: having the freedom to choose what you spend your money on is what retirement is all about. Spending is the new saving when you are retired.
  2. Avoid the spending guessing game: understand the retirement lifestyle that you want to have, not feel you should have. What persona are you? And your partner?
  3. Control in retirement is not just about how much money you have: it is turning your retirement savings into the lifestyle that you have chosen.
  4. Spending patterns and priorities are not static: they change over the retirement lifecycle, meaning that retirees need to be flexible and adapt to circumstances as they arise.
  5. The need for guidance and advice: this continues as retirees make decisions about how to balance living well today with preparing for tomorrow.

Retirement is not simply a phase of life. It is a dynamic, constantly changing lifecycle that requires consistent care and attention. My hope is that this research will help more Australians realise that confidence, choice, and control are not solely reliant on your superannuation balance. Embracing a positive retirement mindset can have a profound impact, especially for those who may be ‘under-retiring’.


About the research

The research was designed and conducted in partnership with Challenger through an online survey of 1,011 people from 7 April to 24 April 2026. The participants were sourced from Ovation, evenly split by gender and from a nationally representative sample but all:

  • Were aged between 60 and 80
  • Had at least $100,000 in superannuation.

The research was conducted in accordance with ISO 20252 and with the Research Society Code of Professional Behaviour.


Susan Bell is the Founder and Lead Researcher at Susan Bell Research, a corporate partner of the Research Society that specialises in research on the new lives of older Australians - a demographic that's wildly diverse, rapidly evolving and too often misunderstood. Over the last 30 years, the agency has conducted qualitative and survey research for many of Australia's largest financial services organisations and regulators. Susan Bell is a Fellow of the Research Society, and past Board Director.


  •   23 September 2026
  • 19
  •      
  •   
19 Comments
OldbutSane
September 24, 2026

Love that quote Dudley.

3
Jeff O
September 27, 2026

There's "wants" and "needs"....about retiring and enjoying the later season of life.....and then, there are your "estate wishes, plans and outcomes" ...knowing we all die and can not rule from the grave!!

Like most doctors do not self-treat and seek medical advice for their own health and family health; most people/families without the financial capabilities/literacy need "disinterested" financial advice to help manage the volatility, uncertainty, complexity and ambiguity in their financial choices......to be healthy + wealthy = "wellthy"

But what massive behavioural failures and incomplete financial market lacking information & trust with advice, when about 50% of pre-retirees and over 80% of retirees either do not choose to pay for and/or seek "free" (disinterested) financial advice to help to live a "wellthy" long life, rather than "under-retire"...or under-live.

It's similar to physical and mental health...arguably, humans most important capital; again, many people rely on the public government funded service and at times wait in pain without physical freedom for too long for "free" treatments and others choose to exercise, eat well, spend on advice as well as do not self insure or under-insure.

Indeed, this is not just about under-retiring; and for wealthy older Australians is largely self-harm, inertia and other behaviours or lack of financial literacy or self care or advice.

lyn
September 27, 2026

Oldbutsane, me too and his other nuggets, as I suspect (perhaps not alone) that I need a refresher masterclass in Maths for his equations!

1
Dudley
September 28, 2026


"need a refresher masterclass in Maths":

Nope. Just Google search:

For arithmetic result and explanation of inputs;
'Calculate = NPER(((1 + (1 - 0%) * 6.7%) / (1 + 4%) - 1), 4%, -100%, 0%)'

For arithmetic result and explanation of mathematics;
'Evaluate = NPER(((1 + (1 - 0%) * 6.7%) / (1 + 4%) - 1), 4%, -100%, 0%)'

Google Sheets is a free cloud located spreadsheet program similar to Microsoft Excel. Likely don't need.

Martin
September 24, 2026

None of these articles ever discuss the impact of inflation and how it de-values superannuation. At 4% pa the value of super will halve in 18 years. A good reason not to draw super balances down. Actual household expenditure on energy and food, insurance is running much higher than CPI, so wealth is rapidly de-valuing

11
Dudley
September 24, 2026


Tax 0%, nominal return 6.7%, inflation 4%, initial withdrawal 4%, present capital -100% (- = in fund), future capital 0%:
= NPER(((1 + (1 - 0%) * 6.7%) / (1 + 4%) - 1), 4%, -100%, 0%)
= 40.9 years.

1
OldbutSane
September 27, 2026

"At 4% pa the value of super will halve in 18 years." This will only IF there is no growth or income generated by the portfolio, so it is plainly nonsense. There are oodles of articles which suggest that you can safely spend 4% of your portfolio and maintain your capital. And don't say "Oh but I have to draw down more (from super) as I get older", so I won't have any left, well yes, you do have to take it out of super, but you don't have to spend it!

1
Mart
September 24, 2026

Great article, thank you. But changing established mindsets (save to spend) ain't easy !

6
PeteK
September 26, 2026

If you read the earlier article in this First links about house prices and the inevitability of a recession some time in the future (I predict fairly soon) you will become aware, if you're not already, of investment sequencing risk. That in poor economic times the returns on your investment/s may be lower than your drawings from them and the capital value will drop, leaving you with a lower base to recover from and of course less income to draw down.
This scenario has concerned me since we lost a lot of money during the GFC (when we were not retired, but had hoped to soon)
So, although we have sufficient funds for a comfortable retirement, without costing the taxpayer anything (in fact we still pay some tax) we are being very prudent and keeping spending within the budget of our net investment income. I see this attitude changing in 3 or 4 years after the recession's depths have been plumbed.
So the yacht has been sold and I crew on someone else's and no Porsche (which as Dudley correctly states - I don't need!) for now.
BTW, we created our modest wealth post GFC, by starting a business and working 10-12 hour days, 7 days p/w for 14 years.
Cheers - C'mon Freo!

4
lyn
September 27, 2026

PeterK, do love a bit of humorous dry wit, special thanks to you and Dudley for 2 spit out the tea moments. Condolences re yacht and Porsche but fear not, Susan pleasingly said we retirees are not static and can shift persona so you may get your moment in sun with sunroof open, will it be a new one or older classic model??

1
Jim Bonham
September 25, 2026

There is some interesting material in this article, thank you, but the title does concern me.
Sure, some people, to their detriment, are excessively conservative investors and anal about spending; some are irresponsibly reckless.

And sure, many people need good advice and it’s important to understand what they need.

However, there is an enormous gulf between
(a) finding out that someone is frightened of running out of money or, equivalently, of having insufficient for their needs at some point, and
(b) demonstrating that that fear is unfounded.

Yet the latter seems to be the default assumption here.

1
Dudley
September 25, 2026


"frightened of running out of money" ... "demonstrating that that fear is unfounded":

'Impossible' to run out of money. The Commonwealth will just put the Age Pension on the national 'credit card'.

2
Graham W
September 25, 2026

I am more and more of the opinion that retirees firstly find an advisor experienced and enjoying working in the retiree area. The role of annuities in providing regular income that is tax and Centrelink advantaged should be a core area of discussion. Once established they are set and forget. If an annuity and a part pension are able to cover basic living costs, a reasonable exposure to growth assets should be considered from the remaining non -cash funds.

1
Tommy
September 27, 2026

Hi Graham - that's a logical response and what you'd expect to be the case. However - whenever I have looked at annuities for ourselves or relatives, the products offered and return rates given just do not stack up. They seem to want to you to give up capital for a guaranteed return that is too low to justify doing it. The same seems to apply with reverse mortgages, great concept with a huge market of cash poor retirees with large home equity but the products offered and interest rates charged are terrible. Finally, the same disappointment has followed through for me with the financial advisor industry. I'm sure there must be some good ones out there but how do you find one? The regulation of this industry is a joke, advisors caught blatantly ripping off clients are given a slap on the wrist. Even reading the product promotions disguised as friendly and helpful advice on sites like this puts me off (the best impartial advice is in the comments not the articles). I'm retired, self managed, use no investment products or advice and rely on my own wits to navigate around the sharks in the financial services industry and the government. Not because I wanted or expected it to be like this, because the financial services industry does such a poor job, and the products and services it offers are so underwhelming.

4
Graham W
September 29, 2026

I should explain that an annuity works best when someone is Asset Tested for an Age Pension. If, say $100,00 is invested into an annuity, $40k is exempt from the asset test. So the pension increase is $3,120 pa. This is a return of 3.12 % added to the return rate of the annuity, making the decision easier.In years past they were (and should again be) 100% Asset Test exempt. This adds 7.8 % to the return in the form of increased pension.
The Centrelink Home Equity Access Scheme is worth a look, no cost to set up and an interest rate less than 4 %. The patments are very flexible and not income for any circumstance.

lyn
October 02, 2026

Graham W, placed here as no comment facility under your 2nd comment re C/Link Home Equity Access Scheme. Out of interest read about scheme as you commented "flexible and not income for any circumstance". As with anything re C/link it's convoluted, however, is clear if lump sum advance chosen and not spent within 90 days then advance is counted towards both income & asset tests. Re fortnightly payments from loan rather than lump sum, couldn't find anything if treated as income tho I'd highly doubt it is when such loan is access to own capital but the point is, to consider such a move people need to go into very deeply before knowing for sure it's not regarded as income as you said.
If needed, personally wouldn't touch as Govt related & no govt seems to put any value on past 'contractual' agreements eg, changes to Super not grandfathered, they each turn on a sixpence.

john
September 24, 2026

10% over the average working lifetime ahould always be sufficient. As long as one does not invest thru a poor fund manager.

lyn
September 27, 2026

Fig.20. Surprised 50% of retired persons sought financial adviser in retirement, perhaps a bit of over-concern or did the question also include retirees with ongoing advice arrangements as well as one-offs?


Leave a Comment:

RELATED ARTICLES

The three key drivers of a purposeful retirement

Retirement in reality - 6 months in

Retirement in reality - 5 months in

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.