Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 212

Decide if 'fake crises' are worth the worry

'Fake news' has been dominating the media since the Trump Presidential win. Financial markets have a parallel concept we will call 'fake crises'.

A fake crisis is a major sell-off of one or more asset classes brought on by widely-held expectations of an impending disaster, but one that fails to eventuate or has been massively exaggerated.

Unnecessary losses from a fake crisis

A fake crisis can inflict heavy losses on an investor who dumps quality assets at depressed prices during the panic but provides the opportunity for an investor to acquire good assets cheaply.

An outstanding example of a fake crisis in investment markets – the cause célèbre – occurred in the early weeks of 2016. The dominant view then was China’s economy was 'contracting' and would soon cause a global recession. Commodity prices, share markets and the Australian dollar plunged.

As things turned out, retail sales continued at almost double-digit growth, industrial production expanded strongly, and China boosted demand on a scale the doomsayers had not allowed for. Shares, commodities, confidence and the Australian dollar all rebounded.

Other fake crises in investment markets during recent years

Many examples of fake crises have unnecessarily worried investors, including:

  • The initial (but very brief) collapse in share prices following Donald Trump’s win in the US presidential election.
  • The loss in market sentiment following the Brexit vote in June 2016.
  • The 'taper tantrum' in 2013, when bond markets sold off aggressively on the expectation the Fed would mismanage the phasing out of its huge programme of bond purchases.
  • The 'sovereign debt crises' in Europe in 2012 and 2013, which were exaggerated and were followed by record low bond yields.
  • The widely held fears in the second half of 2011 that the US economy was sliding back into recession.

Fake crises generally follow the same pattern. Investors always have a lot of things to watch and to worry about. From time to time, concerns develop, sometimes without justification. A momentum builds up. Many investors come to uncritically accept data or comments that support the majority view while ignoring the countervailing facts. Maybe some hedge funds will 'short' assets or asset classes, expecting to buy them back during the crunch at lower prices. Research reports may be released full of gloom and doom to support the portfolio positions the hedge funds have taken up.

Managing reactions to a fake crisis

The best way I know of working out whether a crisis will create prolonged pain or be short-lived is for the investor (perhaps through his or her adviser) to create two lists on the outlook for the relevant market or markets. One list would show the worries. The other list would set out the positive or counter-balancing influences. The investor can then take an on-balance view appropriate to their risk tolerance.

This approach can be applied to any or all investment markets. Let us try it on the current outlook for the Chinese economy.

List of China negatives and positives

Negatives:

  • The huge build-up in indebtedness by Chinese governments (at the national and regional levels) and by property developers.
  • The potential for bad debts of banks to blow out.
  • The excess capacity in heavy industry.
  • The risk of a surge in capital outflow causing a run on the Renminbi.
  • The slow pace of reform among state-owned enterprises.

Positives:

  • China has a high level of saving.
  • The increased debts are mostly owed domestically and not to lenders abroad.
  • International reserves still stand at US$3 trillion.
  • For many years there will be a high level of building construction for the urbanisation program.
  • To date, the move to a more market-determined exchange rate mechanism is working well.

Buy, sell, do nothing?

A reasonable on-balance assessment is that the pace of expansion in the Chinese economy will slow a little, both cyclically and in trend terms, in the next couple of years. The risks of recession are low but there will be recurring big swings in investors’ confidence in China’s economic conditions and prospects.

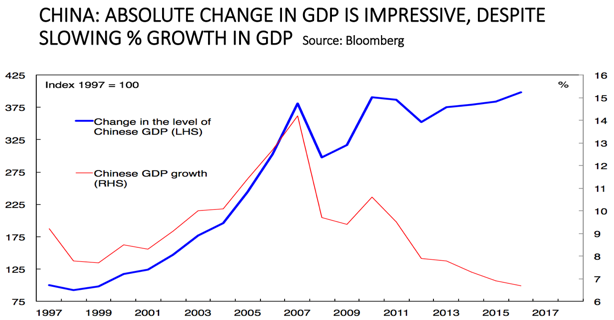
China’s growth has moderated from a rate of 14% in 2007 to 7% in 2016. But in absolute terms, the year-by-year expansion in the Chinese economy has remained impressively large, and that is what matters for both global growth and the Australian economy.
Fake crises can materially impact investor returns if it leads to panic selling, so a calmer and more systematic approach is called for to avoid overreacting to the noise.


Don Stammer has been investing for over 50 years, including long periods with Deutsche Bank and ING. He writes a fortnightly column on investments for The Australian and has advisory roles with Altius Asset Management and Stanford Brown Financial Advisers.


  •   27 July 2017
  • 1
  •      
  •   

RELATED ARTICLES

Lessons from a century of virus plagues

How likely are market crashes?

A world out of sync with inflation

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.