Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 414

Finding sustainable dividend stocks on the ASX

Rio Tinto (ASX:RIO) has been a top dividend payer on the ASX for years. In 2019 the iron ore miner topped the list, paying 47% more in dividends than second placed Macquarie Group (ASX:MQG).

A year later the miner blew up a 46,000-year-old Aboriginal cave site. The fallout from the Juukan Gorge incident took the Chief Executive and the firm’s Head of Iron Ore with it.

With bond yields still anchored to the ocean floor, dividend payers such as Rio Tinto are a crucial portfolio fixture for income investors. But many reliable payers are in the resources sector and carry high environmental, social and governance (ESG) risks. What can income investors do?

To untangle this Gordian knot, I’ve looked through the Morningstar database to find reliable dividend payers who also meet stringent ESG and carbon risk criteria.

ESG risk ratings measure the economic value at risk from unmanaged environmental, social and governance factors. In the case of Rio, this could range from water pollution to legal action from First Nations groups.

Over 1,300 data points are analysed to give a score which classifies companies on a 5-point scale from ‘Negligible’ to ‘Severe’.

The carbon risk rating focuses on the unmanaged risks to a company's value stemming from the transition to a low carbon economy, through the amount of carbon emissions in its operations, products, services and investments.

To begin, I look for companies that are:

  • Low ESG risk: Classify as ‘Negligible’ or ‘Low’ on both ESG risk and carbon risk
  • Reliable payers: Have at least a 3% trailing 12-month (TTM) dividend yield and five year average dividend yield
  • Fairly valued: Trading in a range Morningstar considers fairly valued.

Real estate investment trusts (REITs) and narrow-moat asset manager Pendal (ASX:PDL) top the list for sustainable dividend yields.

Cromwell Property Group (ASX:CMW) is first, with a distribution yield over the TTM and five year horizons north of 7%. The other REITs on the list are near or above the 5% mark.

Of the five REITs, only Dexus (ASX:DXS) qualifies for a Morningstar narrow moat, implying a 10-year competitive advantage.

Sustainable picks based on historic dividend/distribution performance – fairly valued
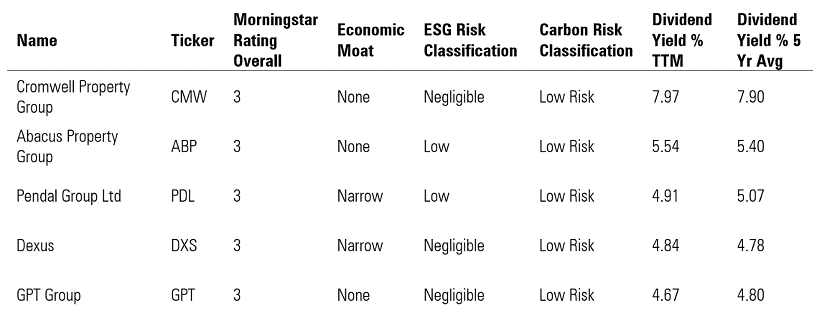
Source: Morningstar Direct. Data as of 22 June. While similar to a dividend, REITs technically pay a distribution.

Beyond the REITs: G8 Education, Sydney Airport, and IRESS

Australia's largest private childcare operator G8 Education (ASX:GEM) and narrow-moat Sydney Airport (ASX:SYD) are options for those looking outside the REIT sector.

G8 Education and Sydney Airport meet the sustainability criteria and have a five year average dividend yield greater than 4%. Neither has paid a dividend since COVID hit, but Morningstar analysts expect both to provide a dividend yield in excess of 4% in 2022. G8 Education is currently trading at a 53% discount to its fair value estimate.

If the net is widened to stocks Morningstar considers somewhat overvalued, investors can consider narrow-moat toll-operator Atlas Arteria (ASX:ALX) or narrow-moat financial software provider IRESS (ASX:IRE). They are trading at an 11% and 19% premium to fair value, respectively.

Sustainable picks based on historic dividend performance - premium to fair value
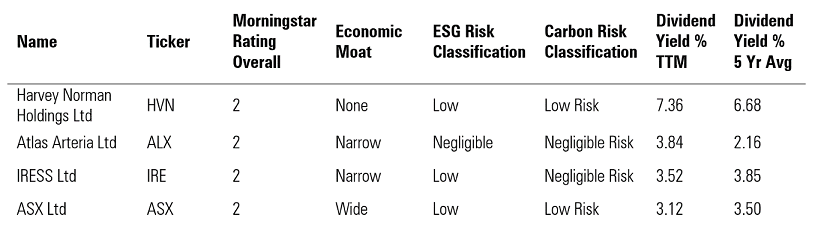
Source: Morningstar Direct. Data as of 22 June.

Future dividend payers

Past performance is no guarantee of future result, so I’ve included those companies that Morningstar analysts estimate will have a dividend/distribution yield greater than 3% in 2022.

The list includes three more REITs, as well as Southern Cross Media (ASX:SXL). The latter has not paid a dividend since September 2019 and closed at a 43% discount to fair value.

Sustainable firms estimated to pay a dividend yield greater than 3% in 2022 - fairly valued
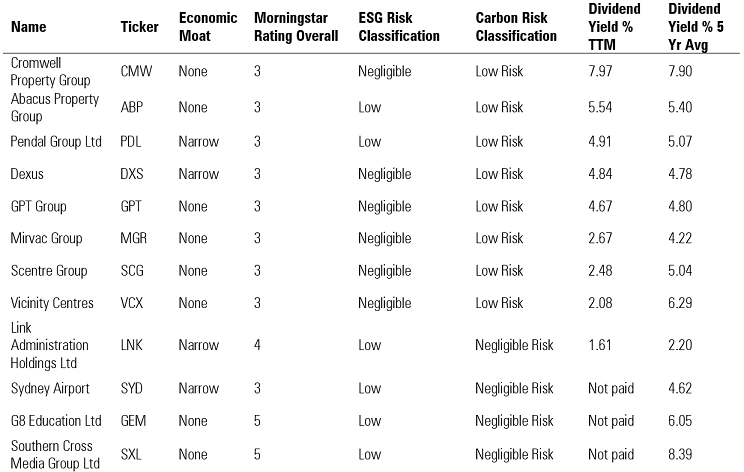
Source: Morningstar Direct. Data as of 22 June. While similar to a dividend, REITs technically pay a distribution.


Lewis Jackson is a reporter/data journalist at Morningstar, owner of Firstlinks. This article is general information and does not consider the circumstances of any investor.

A Morningstar Premium free trial is available on the link below, including access to the portfolio management service, Sharesight.


Try Morningstar Premium for free


  •   30 June 2021
  • 10
  •      
  •   
10 Comments
Niki
June 30, 2021

I don't believe G8 is a good stock.

Ken
June 30, 2021

Why?

Tom Harbrow
June 30, 2021

Downside is it is in an area that can be trashed / elevated by government policy, upside is current price, further upside is that any government trashing this sector wont last long (held) Tom

Warren Bird
June 30, 2021

I'd also ask, in the context of this article, 'so what?' The article wasn't recommending or predicting long term total return performance of these stocks, it was simply outlining how to go about searching for good ESG rated, dividend paying stocks. Whether that's a good enough investment process or not is another matter, but the article is merely one piece of a bigger puzzle.

Graeme
June 30, 2021

Yes, why?

Lorraine Shackell
July 01, 2021

I bought G8 in April 2016 for $3.90 and sold In June this year for $1.036. What I received in dividends in that period certainly didn't cover the difference in those two prices. Definitely not one of my better buys.

bluey
July 02, 2021

Yes, good food for thought. I did think about this dilemma a few years ago, but decided instead to hang on to RIO and buy an electric car with the dividends [truly], some $21.50 per share over the last 3yrs. I'm sure RIO will straighten its ways going forward.

Steve
July 04, 2021

One that slips under the radar is IVE Group (IGL). It has moved out of ASX 300 but dividends have now resumed as per pre-pandemic levels and is still attractive dividend-wise with an increasing share price (recovery and on market buyback).

Trevor
August 09, 2021

Would have thought CLW would be preferable to GPT. I own both and I know which is helping my retirement most!

James
August 09, 2021

CHC is better than both!


Leave a Comment:

RELATED ARTICLES

Can you value a share just using dividends?

What are the key trends in global dividend income?

How to use debt recycling to your advantage

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.