Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 618

Investors might be paying too much for familiarity

In today’s investment landscape, the dominance of the US—especially a handful of mega-cap technology companies—is hard to ignore. These firms have powered a disproportionate share of global equity market returns in recent years, and the US now accounts for around 75% of the MSCI World Index. The so-called ‘Magnificent Seven’ have captured investor imagination and capital alike. But when nearly everyone is crowded around the same trade, it’s worth asking: what if we’re all looking behind the wrong door?

Enter the Monty Hall problem. This classic probability puzzle, loosely based on a 1970s game show, involves a contestant picking one of three doors—behind one is a car, behind the others, goats. After the contestant picks, the host (who knows what’s behind each door) opens one of the remaining doors to reveal a goat. The contestant is then given the option to switch. While most stick with their initial choice, switching actually doubles the contestant’s odds of winning the car!

The puzzle is a compelling metaphor for today’s markets: just because something feels obvious—or has worked recently—that doesn’t make it the right choice in future.

Lesson 1: The obvious choice isn’t always the best one

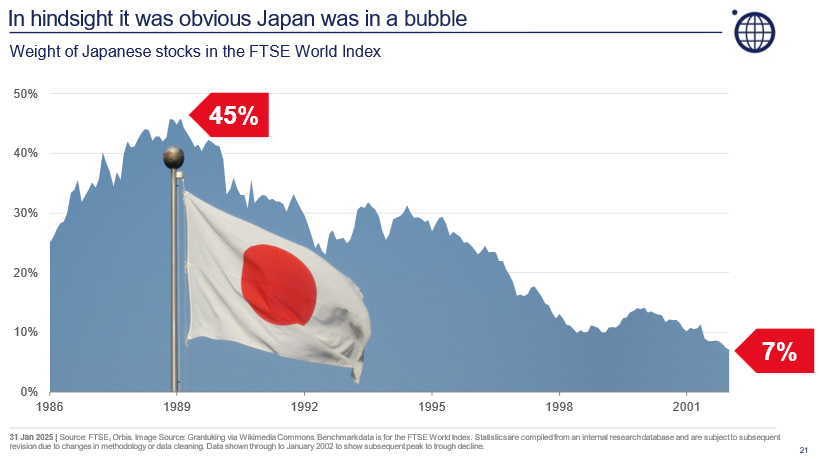
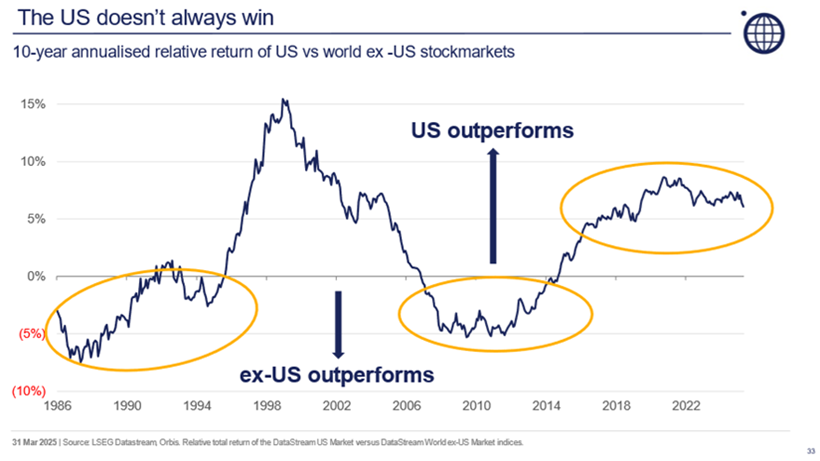
On the surface, staying heavily invested in US equities looks sensible. It’s the world’s largest economy, home to dominant companies, and it has outperformed for over a decade. But history reminds us that market leadership shifts. In the late 1980s, Japan made up more than 40% of the global index—before its bubble burst. Similarly, the dot-com crash of 2000 exposed the perils of speculative excess in the technology, media and telecoms sectors. Both events were obvious in hindsight, but herd mentality and a fear of missing out clouded judgements at the time.
Today’s US equity market shows signs of similar concentration and froth. President Trump’s renewed tariff threats have unsettled markets as well as global supply chains, and fresh US export restrictions on chips to China prompted warnings from NVIDIA about billions in lost revenue. Meanwhile, valuations remain stretched.

For a generation of investors raised on uninterrupted American outperformance, it may be time to reassess where the real risks—and opportunities—now lie.
Lesson 2: Insight matters—but only if you act on it

Spotting market dislocations is one thing, acting on them is another. Investors may sense that sentiment is frothy but going against the crowd is always difficult. It’s particularly hard when the prevailing narrative is that “AI is the tide that will lift all boats” and investors are surrounded by highly speculative activity being wildly profitable.

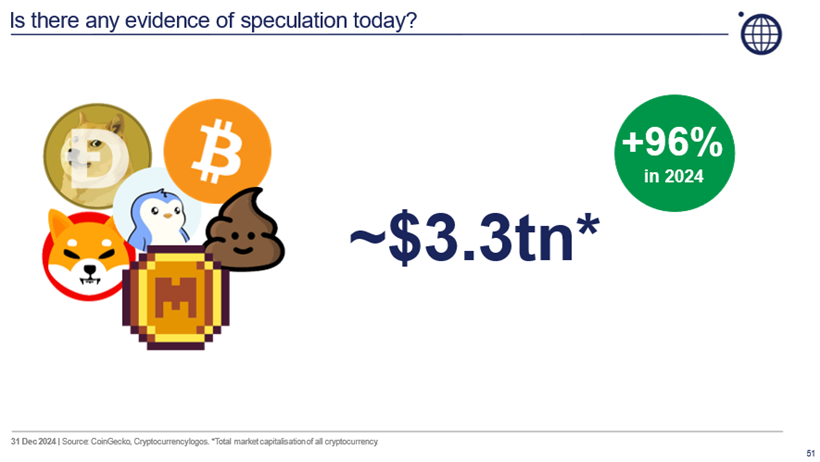
At the end of 2024, cryptocurrencies and digital tokens were valued at $3.3 trillion—up 96% in a year. In a sign of the times, ‘Fartcoin’ which was launched in October ended 2024 with a market cap just shy of $1 billion. That’s more than three times the peak valuation of Pets.com, the dot-com bubble’s poster child, which managed to go public and go bankrupt in the same year back in 2000.
Meanwhile, US hyperscalers have been ramping up capital expenditures to chase AI dreams—with no clear line of sight to monetisation. Their ratios of capex to sales are rising sharply, and it’s not clear that returns will justify the outlays.

And that’s the crux of it: markets aren’t always efficient—especially when investors are chasing hype over substance. As the Monty Hall problem teaches us, knowing the odds isn’t enough. You need to tune out the noise and have the conviction to switch, even when it feels uncomfortable.

Lesson 3: Nothing is certain—apart from death and taxes

Even with the optimal Monty Hall strategy, contestants only win two-thirds of the time. In investing, research shows that even top-tier managers only get it right about 60% of the time. That’s why broad and thoughtful diversification—across sectors, geographies, and styles—is so valuable.

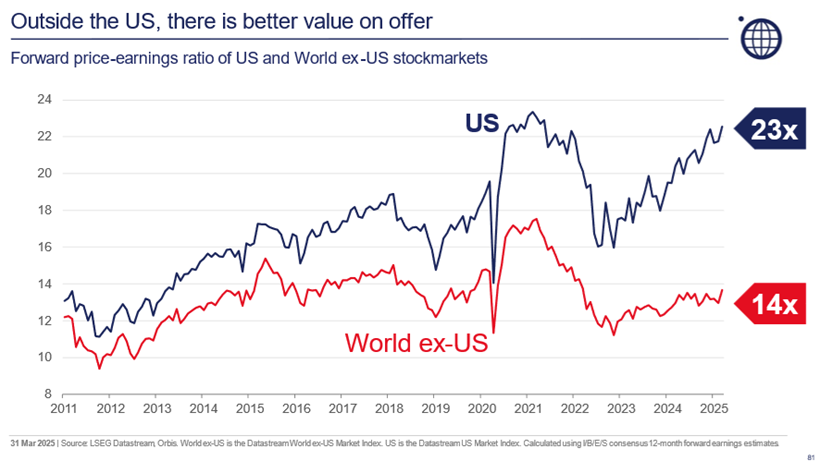
Many investors today believe they’re diversified because they hold global index trackers. But with US stocks now making up nearly 75% of global benchmarks like the MSCI World Index, many portfolios are far more concentrated than they appear. That concentration is made more problematic by valuation levels. The S&P 500 trades at around 23 times forward earnings—well above its historical average and significantly more expensive than global markets, which average closer to 14 times. This discrepancy suggests that investors might be paying too much for the comfort of familiarity.
Meaningful diversification is about holding assets that behave differently—and the benefits are felt most when the prevailing market trends reverse. Investors need to ask whether their portfolios are truly positioned to weather regime changes. And if they aren’t, what’s stopping them from switching?

Reframing comfort zones

The Monty Hall problem teaches us that the obvious answer isn’t always the correct one. The same holds true in investing. Sticking with the US and big tech may have felt safe, until very recently at least, but sticking with what’s familiar can offer false comfort. In today’s environment, defined as it is by extreme market concentration and investor herding, the real edge lies in having the conviction to take a different path.

Ultimately, investors must always be sceptical about simply following the prevailing market consensus, as current prices already reflect those views.  Proper diversification today also requires going beyond simply mirroring global benchmarks.

Just as switching doors improves your chances in the Monty Hall problem, being willing to look beyond the obvious and focus on where value is being overlooked is the key to long-term success in investing.


Werner (Vern) du Preez is an Investment Specialist at Orbis Investments, a sponsor of Firstlinks. This article contains general information at a point in time and not personal financial or investment advice. It should not be used as a guide to invest or trade and does not take into account the specific investment objectives or financial situation of any particular person. The Orbis Funds may take a different view depending on facts and circumstances.

For more articles and papers from Orbis, please click here.


  •   2 July 2025
  • 4
  •      
  •   
4 Comments
Nadal
July 03, 2025

"While most stick with their initial choice, switching actually doubles the contestant’s odds of winning the car!"

This is false. Both doors at this point have a 50% probability of hosting the car.

Jeff
July 04, 2025

It sounds counter-intuitive but the Monty Hall paradox is mathematically proven to be true:

https://en.wikipedia.org/wiki/Monty_Hall_problem

Ian
July 06, 2025

You would be correct if the host opened one door BEFORE you made your original choice, however once you have made your choice (with a 1/3 chance of being correct), he is not opening a random door anymore. The two doors he now has to choose from have a combined probability of 2/3 of hiding the car, and since he must choose a door that doesn't have it, it leaves only the other with that 2/3 chance. Thus doubling your chances of winning if you swap. A key here is that he is always committed to opening one of the doors before you make your selection - if he only offered it sometimes, it could indeed be used to sway you to make the change when you have actually selected the car.

Peter
July 07, 2025

Afraid I don’t get it and can’t see why Nadal is wrong. At the start of the game, the player always knows that the host is going to remove one of the doors with a goat behind it. So the player’s initial selection does not matter. The player knows that with his final choice there will be be only two doors, giving him a 50% chance of choosing the right one by either changing his initial selection or not.


Leave a Comment:

RELATED ARTICLES

The diversification illusion: why 'balanced' portfolios may be exposed

The problem with concentrated funds

Does market concentration really mean more risk for investors?

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.