Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 341

Welcome to Firstlinks Edition 341

  •   22 January 2020
  • 1
  •      
  •   

The majority of investors hold a diversified portfolio no more than half invested in equities. The share exposure often declines with age as retirees seek capital preservation, and even young people place their super in balanced funds. Delight in the noisy 'all-time highs' is far from universal, with millions of Australians missing the big gains. Stockmarket analysts live in a blinkered world of screens focussed on share investments, as one told AAP this week:

"The local bourse is on fire and then some! It's a thing of beauty and local investors are pleased as punch. Australia is historically a bit of a laggard compared to our US counterparts but we're mixing it up with the big boys at the moment."

Better to ignore the bluster and consider the words of Howard Marks in 2013:

"Another mistake that people often make is that they compare themselves with others who are making more money than they are and conclude that they should emulate the others’ actions ... after they’ve worked. This is the source of the herd behaviour that so often gets them into trouble. We're all human and so we’re subject to these influences, but we mustn’t succumb. This is why the best investors are quite cold-blooded in their professional activities ...

Too little scepticism and too much eagerness in an up-market – just like too much resistance and pessimism in a down-market – can be very bad for investment results."

The biggest investment news last week was the world's largest investor, BlackRock, moving away from thermal coal and making sustainable investing a new priority. As a major index provider under the iShares banner, it's a massive issue because the Big 3 index providers (BlackRock, Vanguard and State Street) now own on average 22% of a typical S&P500 company. The table below shows they own 18% of Apple, around 20% of US banks and up to 35% of some companies. Their actions will influence hundreds of companies, often behind closed doors.
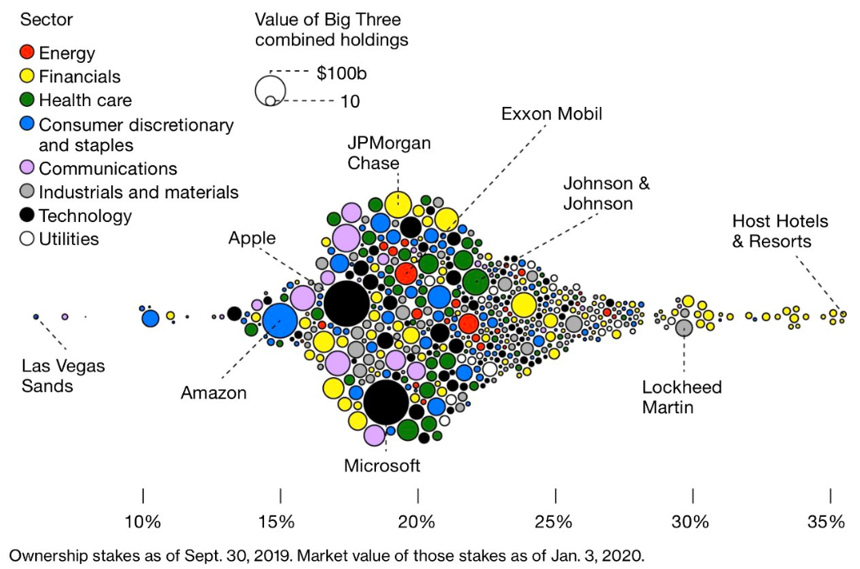

Data compiled by Bloomberg.

Social trends guide investment results, and David James provides a detailed review of Australian demographics. The ageing and composition of our population point to both opportunities and traps. He explores our role in Asia, and on the same tack, Glenn Freeman reports on three large Australian companies whose fortunes depend on China.

Ashley Owen's amazing database demonstrates how much Australian shares have delivered in a diversified portfolio, and he reveals the four components that make up sharemarket returns. What drives your portfolio's performance? Then Richard Dinham shows why investing during retirement differs from saving in the earlier accumulation phase.

The selling fee debate on LICs and LITs shows no signs of abating, with Christopher Joye writing in The Australian Financial Review, " ...conflicted selling fees could determine the fate of the advice industry and the Treasurer's political future." Wow, there are 25,000 financial advisers out there that millions of Australians rely on. In a more sober assessment, Jonathan Rochford identifies three vital points everyone is missing, and I agree with him.

Olivia Long then provides guidance on early access to super for victims of the bushfires and other emergencies, and Dubravka Cecez-Kecmanovic explains that despite enthusiasm for the use of algorithms and AI, they will not lead to the impartial and efficient outcomes most are expecting.

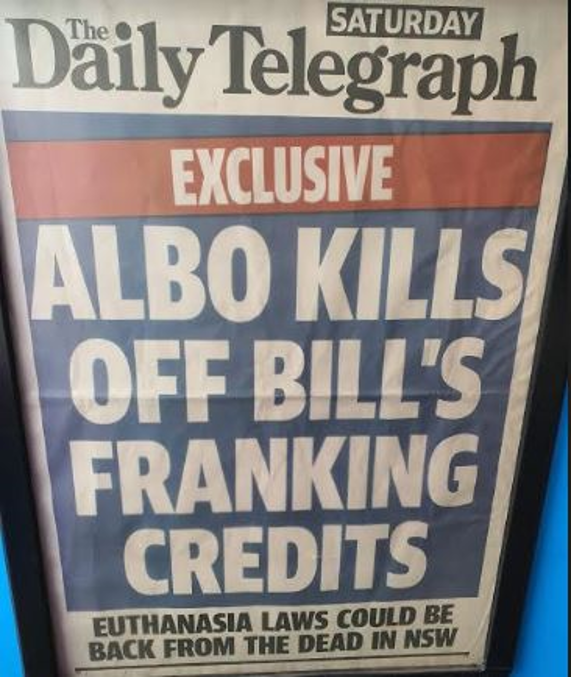
And while the popular press frothed that Labor leader Anthony Albanese has dropped the previous franking credit proposal, all he actually said was: “We won’t be taking the same policy to the next election.” Which means that like the euthanasia laws, it could come back from the dead. 
Graham Hand, Managing Editor

For a PDF version of this week’s newsletter articles, click here.


  •   22 January 2020
  • 1
  •      
  •   
banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.