'You can afford to take more risk.' Every risk-profiling questionnaire leans on the idea, and it sounds like arithmetic: a bigger balance can absorb a bigger fall. Nick Maggiulli argued in Firstlinks that the logic is backwards, because the pain of losing a dollar grows faster than the pleasure of gaining one. He is right, and in Australia he is right in more than one way. His argument is psychology. Whereas ours is legislation. Once a super balance reaches $2.1 million, the ordinary after-tax contribution cap falls to nil, and 'afford' quietly splits into two different words being, (i) surviving a loss, and (ii) replacing one. The headline is blunt. For a retired member with $3 million in super, a 20% fall is $600,000, and the law allows one way to replace it that doesn't involve un-retiring, that is selling the family home. For a working member, its 13 years of maximum contributions — more working years than most 62-year-olds have left.
One caveat before the arithmetic. Money outside super refills the ordinary way, from income and savings, and most portfolio falls repair themselves without a dollar of new money. Both points will be explained below.
The sum Maggiulli ran, and the one Australia adds
Maggiulli's piece contains a calculation, and it is load-bearing. Someone saving $50,000 a year can replace a 20% loss on a $1 million portfolio in under four years; the same loss on $5 million takes more than 14. His conclusion is that risk capacity is bounded not by what you can lose but by what you can put back, and that shrinks as the portfolio outgrows the income feeding it.
Notice the assumption underneath: that you are allowed to put it back. An American brokerage account will take whatever you can save. An Australian super fund will not. The refill pipe has a legislated diameter, it narrows in steps, and past a line it closes.
The steps, from 1 July 2026
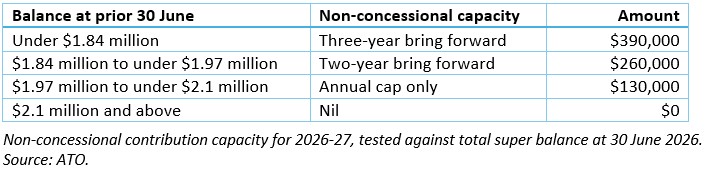
Non-concessional (after-tax) contributions (NCCs) are capped at $130,000 a year, with bring-forward amounts up to $390,000 for lower balances. But the cap is tested against your total super balance at the previous 30 June, and once that balance reaches the general transfer balance cap of $2.1 million, the NCC cap is nil. Concessional contributions (CCs) survive at $32,500 a year, which is $27,625 after the 15% contributions tax, and the cap includes your employer's compulsory contributions, so the true voluntary top-up is smaller again. Between 67 and 74, claiming a deduction for a personal contribution also requires passing a work test.
The remaining doors are limited to, (i) a downsizer contribution of up to $300,000, available once in a lifetime and priced at one family home held for 10 years or, (ii) the small business CGT cap, priced at one business. The $1.84 million and $1.97 million lines below aren't arbitrary, they're the $2.1 million cap minus two, and one, years of the annual non-concessional cap, so both thresholds move whenever the annual cap is indexed.
The $600,000 with one way home
Consider a retired 68-year-old with $3 million in super, no wages, no business to sell, and home owned outright. A 20% market fall removes $600,000. NCC capacity is nil because $2.4 million is still above the line. CC capacity is nil, with no employer and no work test. The full list of refill options that don't involve going back to work is one item long. That is, sell the house and contribute $300,000 once. This halves the loss. Every other dollar of recovery must come from the market itself.
Now let’s look at a 62-year-old still working with $2.75 million built over a career. The same 20% fall takes $550,000 and leaves $2.2 million. This is still over the line, so the only ongoing pipe is concessional. Downsizer is a one-off tap, and it's in the table below too. Even granting the full $27,625 a year, invested and earning 7% will take 13 years to fill the hole. He would need to work to 75, the same year the fund stops accepting his voluntary contributions. That is not a plan; it is the arithmetic’s way of saying it will not happen. If he retires at 67, the refill window is five years, and about $159,000 of the $550,000 comes back. The rest is permanent.
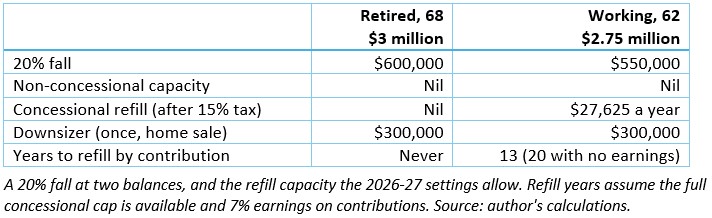
One number worth memorising is $2,625,000. That is the balance at which a 20% fall lands you exactly on $2.1 million. Below that, losing money reopens the door. An investor at $2.5 million who drops to $2 million is rewarded with a fresh $130,000 cap because the system restores your right to contribute only once you have lost enough to qualify. Above $2,625,000, even the fall is not big enough to buy the right back.
The honest objection: markets refill themselves
The strongest counter is that this whole exercise treats the loss as permanent and most aren't. A diversified portfolio that falls 20% has, historically, regained it without a cent of new contributions. The refill pipe is irrelevant if the water comes back on its own. Mostly true, and it is why nothing here is a case against growth assets in super. But the pipe matters precisely for the losses that don't come back, being (i) the concentrated position that roundtrips, (ii) the assets sold near the bottom to fund pension payments, and (iii) the sequencing damage of a bad year in early drawdown. Those are permanent, and above the line they are permanent with no legislative appeal. There is also a fair defence of the caps themselves. Super is a tax shelter, and an unlimited refill right would be a recontribution loophole with a motorway through it. The caps are not the villain. The villain is a questionnaire that says 'afford' without asking which meaning.
What to do about it
Accumulators below $1.84 million can mostly keep trusting the questionnaire. Refill capacity is $390,000 plus decades of earnings and risk-taking is how balances get built. Members between $1.84 million and $2,625,000 should know which tier they occupy and remember the test is the balance at the previous 30 June, not today, so capacity reopens only from the following year. Members above $2,625,000, and any retiree above $2.1 million, should treat every dollar inside super as unreplaceable and weight their derisking, concentration ceilings, and glide paths accordingly. Outside super, a mistake costs money. Inside, it costs money you cannot legally put back.
'You can afford it' is doing two jobs in one sentence: you can survive the loss, and you can replace it. Outside super, the two travel together. Inside, past $2.1 million, the law splits them and keeps only the first. The door does not slam. It narrows with every dollar of success, and by the time you most need to walk back through it, you no longer fit.
Trevor Schmid has more than 20 years' experience across superannuation and financial advice. This article is general information only and does not consider any individual's objectives, financial situation or needs.