What is life sciences real estate?
Life sciences real estate is characterised by facilities largely used for scientific research, diagnostics, healthcare, and innovation — most commonly in biotechnology, pharmaceuticals, medical technology and pathology. These assets are classified within the ‘alternative’ real estate sector, sitting between Office, Retail and Industrial & Logistics sectors, and are distinct from traditional healthcare real estate (e.g. hospitals and aged care).
Life sciences assets are comparatively more complex and sophisticated, with higher upfront capital requirements from the tenant. They can accommodate laboratories (wet and dry), Research and Development (R&D) facilities, biomanufacturing plants, clean rooms, testing facilities, and specialised office-lab hybrid buildings. These uses often require advanced heating, ventilation, and air conditioning (HVAC) control systems, high power capacity with backup infrastructure, and specialised safety features. Assets may also require reinforced floors and be subject to strict regulatory compliance. Typically, they are located within established clusters in close proximity to research institutions, universities, hospitals and skilled labour forces.
While life sciences property encompasses biotechnology and pharmaceutical research, this article focuses primarily on pathology and diagnostic testing facilities, which represent one of Australia’s most established forms of life science infrastructure.
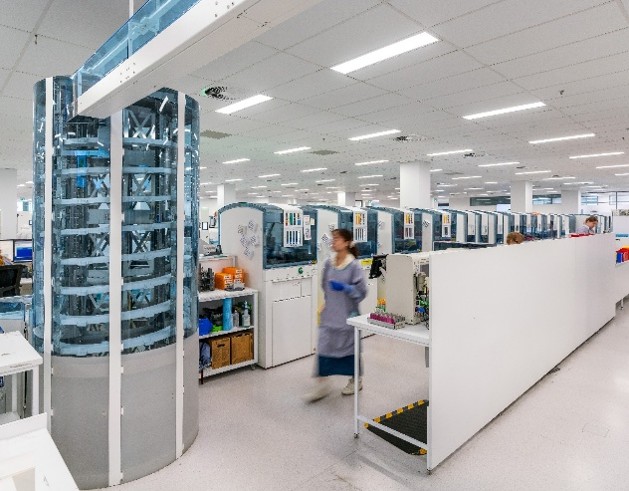
Sullivan Nicolaides Pathology, 24 Markwell Street, Bowen Hills Qld
Structural demand drivers
The sector benefits from several long-term structural trends that may support demand growth. Ageing populations and rising healthcare demand have driven significant increases in healthcare expenditure. In the wake of the pandemic, there has also been an increased focus on longevity trends and a marked expansion in the scale and complexity of medical testing.
Long-term trends supporting demand
- Ageing population: Australia’s population aged 65+ will increase from 1 in 6 today to 1 in 4 Australians by the 2060s, with 85+ the fastest growing cohort.1 This rise in the elderly population is expected to drive structurally higher and recurring demand for pathology and diagnostic testing.
- Leading government healthcare spending and performance: Australia has recorded the highest growth in healthcare spending per capita across the advanced economies, increasing 5.7% compound average growth rate (CAGR) since 2000, above the G12 average of 5%.2 Australia also has an outperforming and productive health system, ranked highly for health outcomes, equity and efficiency.3
- Variety and complexity of testing: Growth in diagnostic testing reflects increasing variety and complexity (e.g. genomic monitoring and biomarkers, multi-panel testing), as well as the expansion of screening programs and early detection initiatives. Preventative healthcare is shifting upstream with an increasing focus on early intervention, which is expected to support testing volumes.
Life sciences real estate as an investment sector
Life sciences real estate is a diverse property sector, and the method of participation for an investor is a key determinant of outcomes. The sector’s specialisation and higher upfront capital requirements create distinct investment implications. Tenant lease terms are generally longer, increasing the importance of tenant financial stability, asset specialisation and location.
- Tenant quality: High-quality tenants reinvest in mission-critical assets, underpinning sustainable rents and long-term cash flow growth. Key indicators of tenant strength include rent-to-EBITDA (earnings before interest, taxes, depreciation and amortisation) and net debt-to-EBITDA ratios. Over time, high-quality tenants with resilient business models tend to deliver EBITDA growth, which may strengthen income security and support rental growth.
- Asset specialisation: The specification, regulation and capital requirements create barriers to entry across the asset class. As a result, well-located, high-quality facilities may be better positioned to command rental premiums and support occupancy over the long term.
- Location: Over time, tenant network effects may strengthen as connections with customers and surrounding business clusters deepen, reinforcing locational dependence and supply chain networks. Immediate proximity to key hospitals, medical research institutions and tertiary health services strengthens operational linkages and increases the strategic importance of the location to tenants.
Conversely, underperforming tenants can materially impair outcomes. In the event of lease expiry, high fit-out costs and asset-specific requirements can result in elevated re-leasing costs. Where assets are in inferior locations or poor condition, these challenges can compound. Tenant concentration and dependence on government reimbursement settings may also represent risks.
Successful investment criteria
Successful investments are typically anchored by tenants with strong and diversified revenue sources. Their cash flows tend to be supported by both public and private funding sources.
Investment risk can be mitigated through careful asset and tenant selection. Greater conviction can be achieved by targeting essential business models with established track records, and by prioritising modern, stabilised assets that reduce development-related risks.
Why pathology facilities may benefit from structural demand
Demand for essential pathology services
- Critical life sciences infrastructure: Australia’s private pathology sector provides essential healthcare infrastructure for illness detection and treatment.
- Non-discretionary demand: Consumption of these services has been resilient through economic cycles, with a strong link to population growth, ageing population, rising life expectancy, and ongoing technological advancements.
- High barriers to entry and limited supply: Significant capital requirements, stringent regulation, specialised facility requirements and scarce suitable real estate constrain new supply, contributing to a highly concentrated market in which the three largest operators account for more than three-quarters of industry revenue.
Healthcare expenditure and service usage
- Ongoing government fiscal commitments: The FY27 Federal Government budget for healthcare increased commitments, with an approximate 17% increase in health expenditure forecast between FY26 and FY30.1
- Rise in service usage: Pathology services provided under Medicare have trended upwards over the past decade. Over the 20 years to FY25, the average annual number of Medicare pathology items claimed per person increased 75%, from 2.6 items to 4.6 items per person.3 In FY25 alone, 175 million services were provided under Medicare.4
- Medicare expenditure: Approximately $3-4 billion per year is spent on Medicare-funded pathology in Australia. This equates to roughly 10-12% of total Medicare expenditure, the joint highest service volumes per capita with GP visits.5
- Growth of market: Australia’s pathology market is worth ~US$11.8 billion in 2025 and is forecast to grow to US$26.2 billion by 2034 (~9% CAGR).6
Public and private funding sources
- Public support: Given the focus on maintaining sustainable healthcare expenditure, governments may increasingly rely on efficient, private providers to deliver healthcare services.
- Medicare support: Pathology has resilient support from government funding through Medicare (~70-90% of volume), with pathology traditionally recording one of the highest bulk-billing rates of any medical service (~91% in FY24, compared with an average of ~76% across other services).1
- Resilient government funding: The government continues to commit to expanding test coverage, adding new reimbursable tests, and supporting access and volumes. Examples include Medicare-funded reproductive carrier screening tests and higher demand for genetic testing. However, reimbursement levels are subject to policy decisions and periodic review.
- Private sector filling the gaps: The private sector is also contributing to service funding, with a growing contribution from private insurance (via hospital diagnostics) and advanced diagnostics.
Together, these factors suggest that pathology facilities may benefit from supportive, long-term demand trends. However, as with any specialised sector, investment outcomes will depend on asset quality, tenant strength, valuation discipline and future supply conditions.
1. Australian Government – Australian Institute of Health & Welfare FY27 Government Budget.
2. Global Health Expenditure WHO, via World Bank 2026.
3. Commonwealth Fund – Healthcare system performance rankings.
4. IbisWorld.
5. Services Australia.
6. Imarc Group.
Steven Bennett is Chief Executive of Direct Property and Sasanka Liyanage is Head of Research at Charter Hall Group, a sponsor of Firstlinks. This article is for general information purposes only and does not consider the circumstances of any person, and investors should take professional investment advice before acting.
For more articles and papers from Charter Hall, please click here.