Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Commodity prices rescue 2019 Budget

It is budget time again in Australia, and the nation is heading for its first Federal Government surplus since 2008, mostly from good luck with China and commodities.

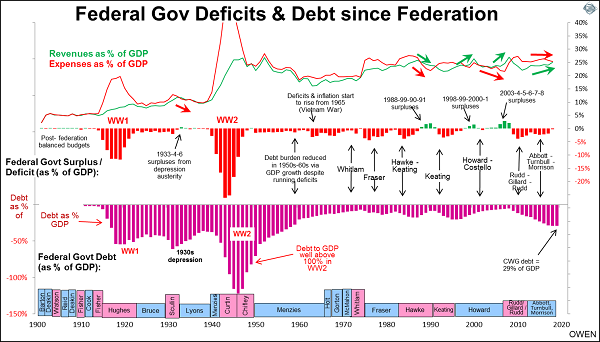
Here is a chart showing the Federal Government’s deficit and debt position since 1901. The upper section shows revenues (green line) and expenses (red). The middle section shows the resultant annual surpluses (green bars – look hard!) or deficits (red bars). The purple bars in the lower section show the level of Federal Government debt. All are expressed relative to total national output (GDP) each year.
Click to enlarge

A brief history of budgets

The Federal Government ran balanced budgets in the early years following Federation but it had very few functions prior to the introduction of Federal Government pensions in 1909. World Wars I & II changed all that, requiring massive war-time deficits and debt build-ups. These were finally brought under control by the 1950s and 1960s booms. The Government still ran small deficits (1-2% of GDP) but rising tax revenues from the booming economy were enough to pay for expanding services and nation-building projects, and still reduce the debt/GDP ratio down to low levels by the 1970s. The current level of debt relative to national output is the highest it has been since the late 1950s.

Producing a government surplus can be done in one of two ways: by cutting costs or increasing tax revenues, or sometimes both. Most of the time the surpluses have been a result of windfall revenue gains, mostly from fortuitous mining booms. The problem is that costs are controllable, but tax revenues depend on mining booms that are based on global commodities price cycles outside our control.

Only rarely have surpluses been achieved by cutting costs. This was the case with the 1930s surpluses. Australia did not follow Roosevelt’s big spending approach in the US. Instead we had to endure harsh ‘austerity’ cost-cutting imposed by London bankers. The government wasn’t able to borrow anyway after it defaulted on its debts in 1931. Arguably the austerity cuts prolonged the depression and stunted the recovery.

The only other period of surpluses produced by cost cutting was the four-year period from 1988 to 1991 by Hawke and Keating. Commodities prices and tax revenues were falling but they were able to produce surpluses by cutting costs by even more, resulting in the deep 1990-91 recession.

The Howard Government had two spells of surpluses – four years from 1998 to 2001, and then another five years from 2003 to 2007 (or six years if you count the 2007-08 year during which Rudd came to office, when boom-time mining revenues were still flowing in prior to the GFC). Both of these surplus spells were driven by windfall tax revenue gains – first from the 1990s ‘dot-com’ boom and the second from the 2003-08 mining boom. Government spending was also reducing during the whole period – from 25% of GDP in 1996 to 21.7% in 2007. But because most of the gains were from boom-time tax revenue rises, the windfall surpluses quickly disappeared when the booms ended.

If the Federal Government achieves a surplus in the current 2018-19 year it will be mainly thanks once again to fortuitous tax revenue gains from the mining boom, not because of cost management. In the past five years the population has grown by just 8%, but government spending has risen by an incredible 21%. By sheer luck the mining boom has increased revenues by 27% but windfall gains like these are not sustainable.


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is for general information purposes only and does not consider the circumstances of any individual.


  •   3 April 2019
  • 4
  •      
  •   
4 Comments
Warren Bird
April 02, 2019

I wouldn't put it quite that way, for a couple of reasons:

1) "rescue" is usually a term I'd use when something unusual takes place, unexpected or last minute. But as the chart shows, Australia has had a cycle that is connected to commodity prices since, well since Arthur Philip arrived. What we're seeing is a typical economic and fiscal cycle at play. And the fact that we've had a strong run in commodity prices is hardly a surprise.

2) the economy and the budget are far from being one pony shows. For example, as Luci Ellis from the RBA pointed out recently, personal income taxes have increased at a faster rate than usual, from a range of factors including increased compliance efforts by the ATO that has effectively increased the average rate of tax collected. Note that the RBA in its monetary policy statement recently mentioned slow "disposable income" growth as a factor, hinting that tax cuts would give a helpful leg up to consumer spending capacity. This increase in budget revenue has nothing to do with commodity prices.

As an aside, I think that the significant improvement in our fiscal position, from whatever source, puts to the sword the argument used by many in the franking credits debate that 'we can't afford to give those refunds'. I've argued before that I think that's wrong and now we have a budget bottom line to support what I've been saying. So let's just focus in the franking credit discussion on the validity of the policy.

Our fiscal position is nowhere near as dire as many folk would make it out to be.

Don Macca
April 03, 2019

Ashley's chart allows us to stand back, forget the trees & look at the whole forest. The impression i get is that Australia's fortune still mostly relies on being a quarry for the world. In particular Iron ore for China.

We need to expand our economy into other areas. We have outstanding companies in medicine, medical research, software .
Can we be reluctant about spending most of largesse on ourselves; instead we should build a future for our children.

Most of us (myself included) have been beating our own drum. We can pick holes in promises made by both Labor & the Coalition. Each one matching the other & then adding a little more. Let's stop beating our own drum.
We need to carefully consider our "Vote".

Warren Bird
April 05, 2019

Don, how do you get that from the chart? Ashley asserts it in his commentary, but the chart shows only government financing information and nothing about commodity prices, exports or anything that would support the contention that we are merely 'the quarry for the world'.

Donald Horne has so much to answer for!

TONY SMITH
April 05, 2019

the Libs are heading toward a real budget surplus, despite all their own goals that make them partially unelectable.
However the Labor budget reply points to more deficits if they are elected. They never raise the revenue anticipated but continue to spend anyway.
Labor only gets into government every decade or so and then want to spend up big to fund all their own priorities.


Leave a Comment:

RELATED ARTICLES

Gold: should you own the metal or the miners?

The red metal's long game

Avoiding destructive M&A and hype cycles in mining

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.