Gold has caught a second wind.
After spending much of the year falling from its January record, the precious metal has climbed back around US$4,500 an ounce. The immediate catalyst was the US Treasury's decision to increase purchases of longer-dated government bonds, which pushed yields lower and weakened the US dollar, both of which are typically supportive for gold.
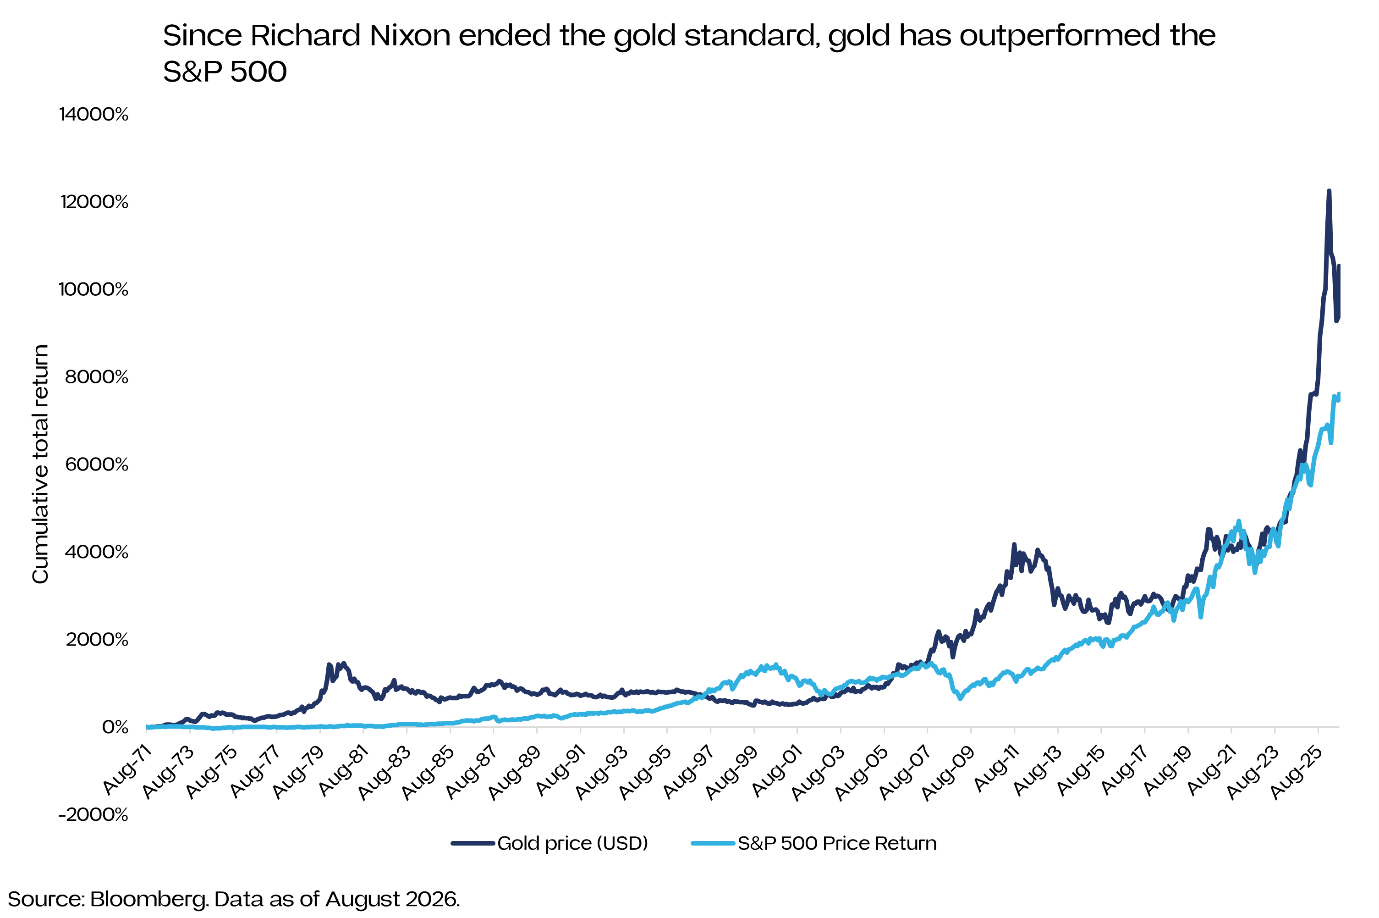
Much of the commentary has understandably focused on where the price is heading next. But another question matters just as much for investors: what is the best way to own it?
Should you buy physical gold, either directly or through a physically backed ETF? Or should you buy the ASX-listed gold miners, such as Northern Star, Evolution and Ramelius?
The answer is unsatisfying but important: it depends on what you want gold to do in your portfolio. Physical gold and gold miners may both benefit from a rising gold price, but they are fundamentally different investments.
Gold: the portfolio diversifier
Gold has been used as money and a store of value for thousands of years. Civilisations from ancient Egypt to imperial China, with little or no contact with one another, independently prized the metal because it was scarce, durable, divisible and difficult to create. While no longer used as money, many investors still view gold as a store of value and portfolio diversifier.
Gold is essentially an asset without an issuer. There is no company whose profits you are relying on, no government promising to repay you and no corporate balance sheet that can go broke. That gives it a quality most financial assets simply do not have: no conventional credit risk.
Today, investors usually describe this benefit in more modern portfolio language: diversification.
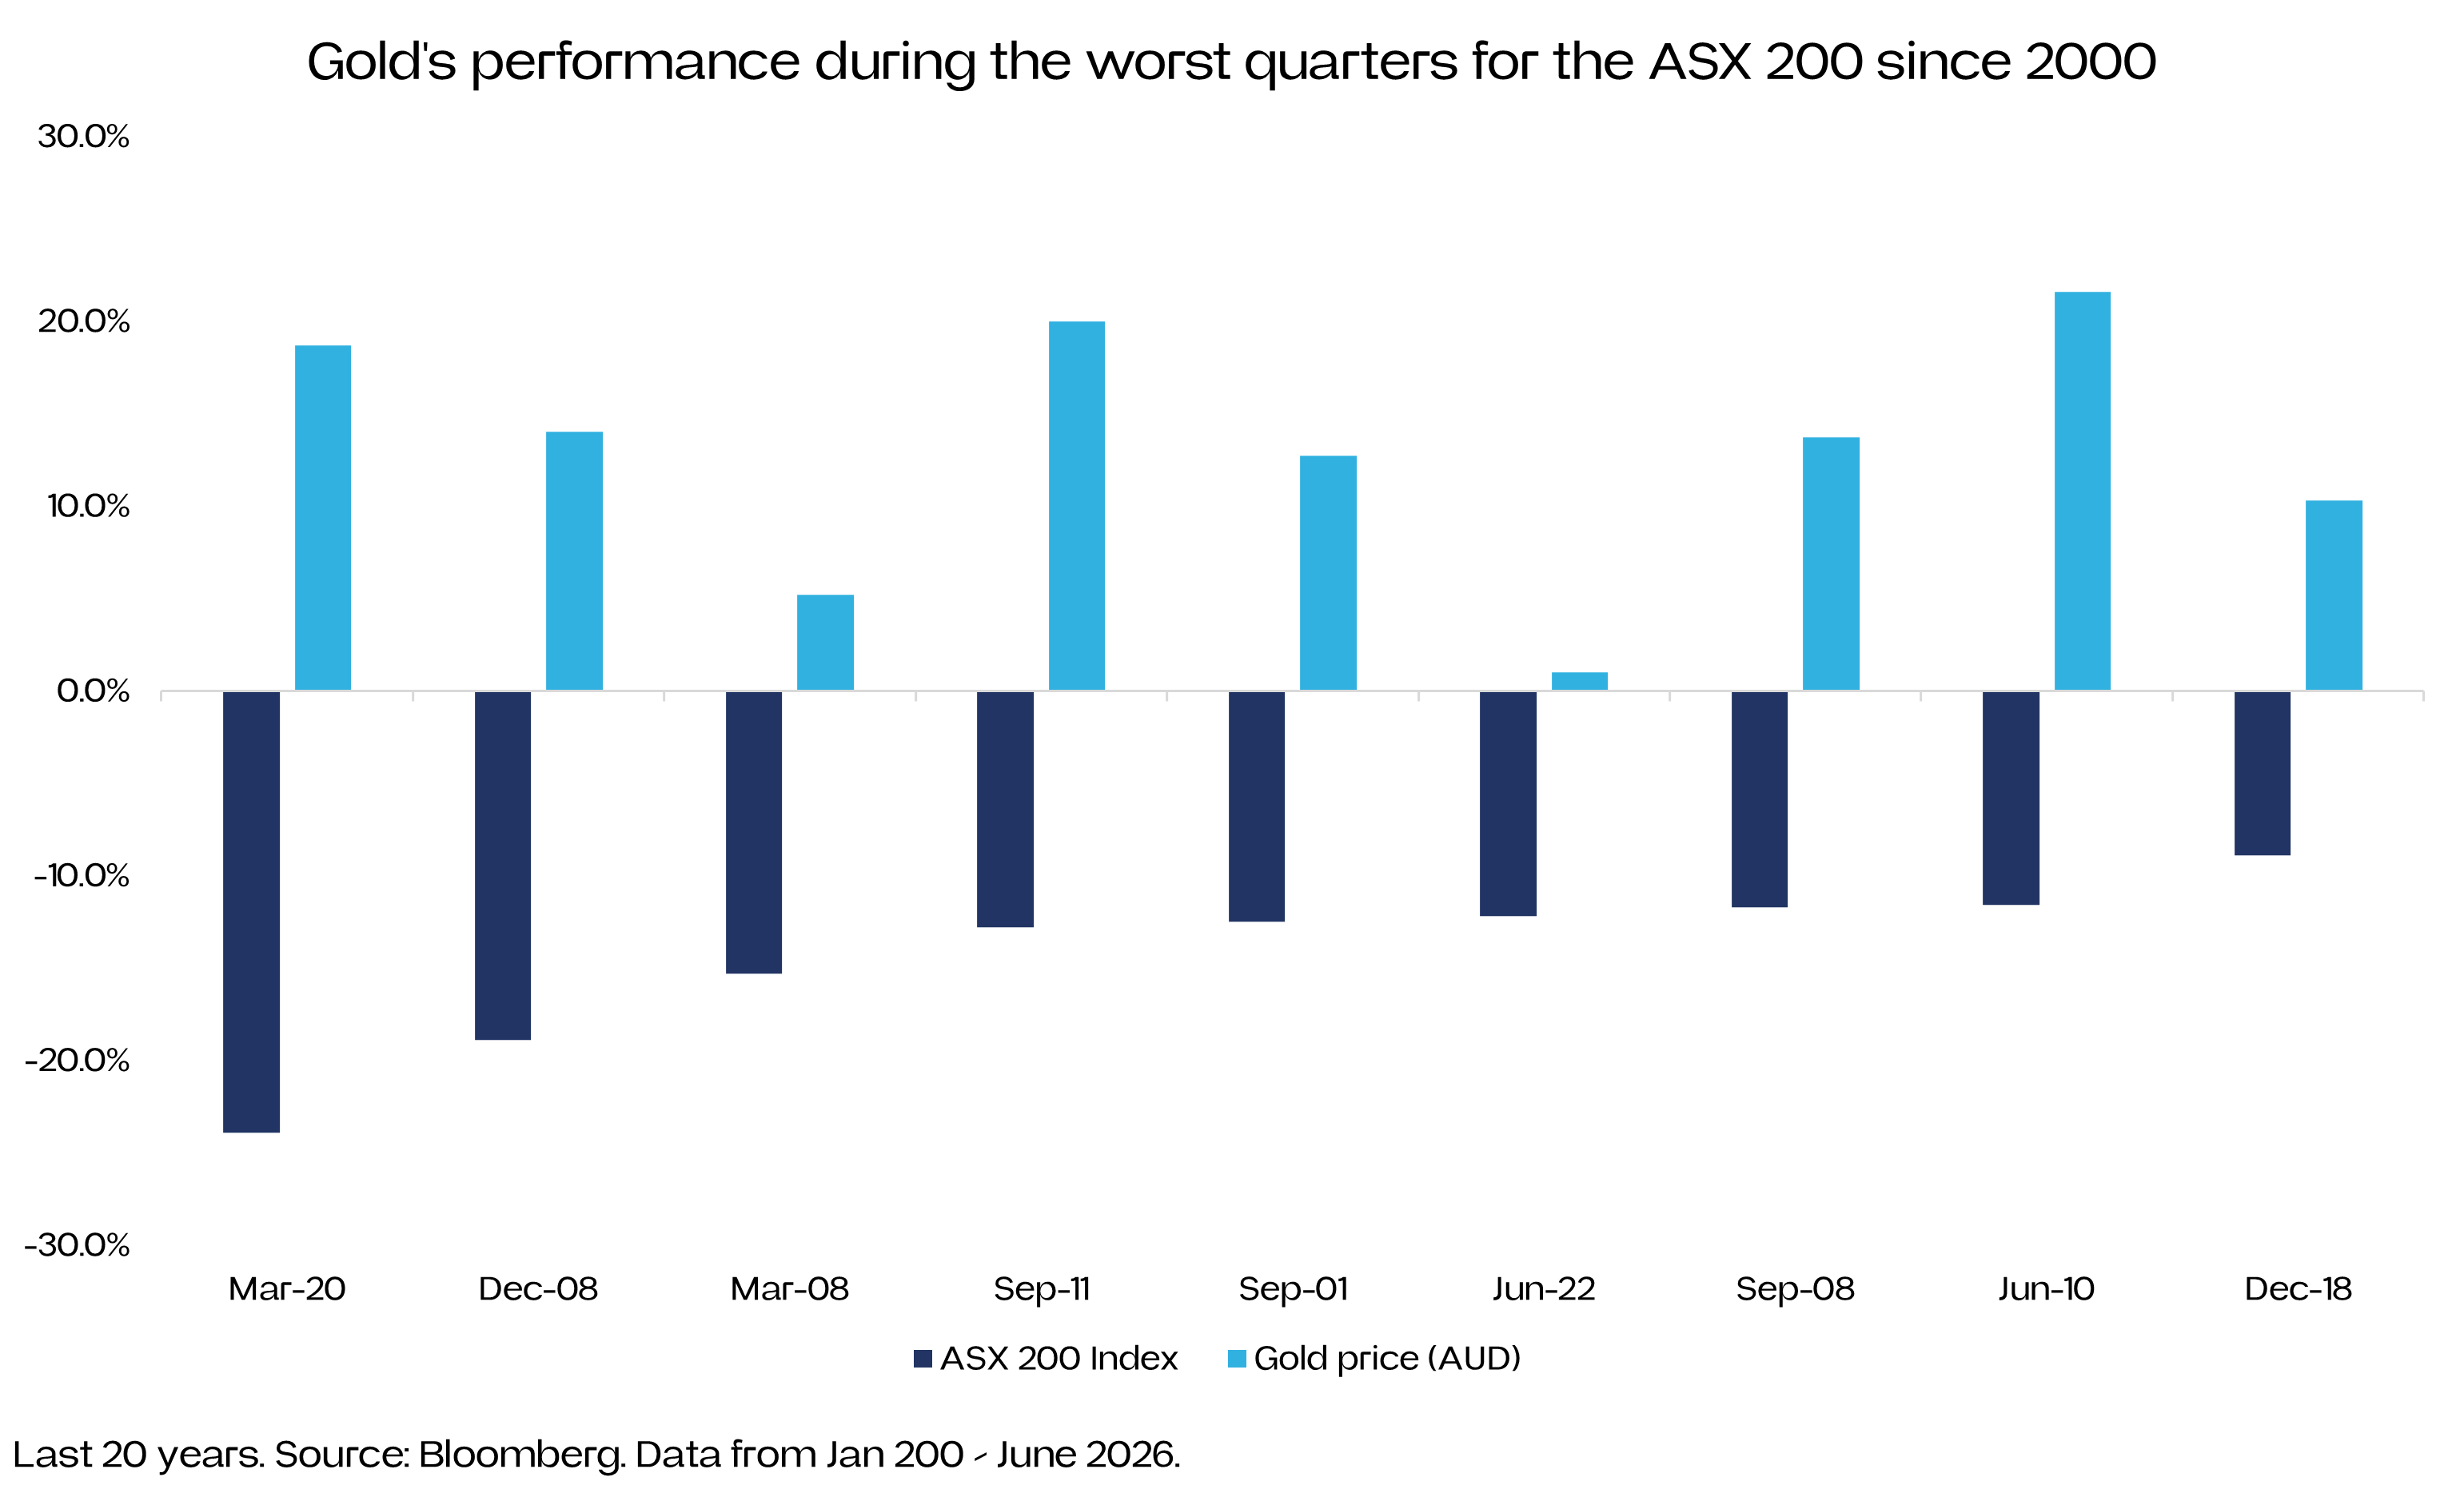
Gold has historically had a relatively low correlation with shares and other risk assets, and at times has performed particularly well when investors are worried about financial markets, inflation, currencies or geopolitics. This is reflected in the chart below, which shows how gold has fared in the worst quarters for the Australian share market over the past 20 years.
That is the crucial distinction between owning gold and owning a gold miner. A gold bar does not have a chief executive. It does not have debt. It does not have a mine that can flood, a processing plant that can break down or a workforce demanding higher wages.
A gold mining company does.
Gold miners are shares, and shares tend to behave like shares. That doesn't mean miners cannot outperform during a stock market sell-off – they certainly can – but they do not provide the same diversification characteristics as physical gold. An investor buying gold primarily to diversify a portfolio of Australian equities gets a purer form of diversification from the metal itself.
Why buy the miners?
None of this means gold miners are inferior. In some circumstances, they are considerably more attractive. The biggest attraction is operating leverage.
Mining companies have large fixed and semi-fixed costs. Once a mine is operating, many of those costs do not rise proportionally with the commodity price. So when gold rises, a much larger proportion of the additional revenue can flow through to profit.
Imagine, very simplistically, a miner producing gold at a total cost of US$2,000 an ounce. If gold is US$3,000, it has a US$1,000 margin. If gold rises to US$4,000, the margin doubles to US$2,000. The gold price has risen by 33%, but the company's operating margin has risen by 100%.
That is the leverage investors gain when they buy a gold miner. In practice, however, realised returns often depend as much on management execution and capital allocation as commodity prices.
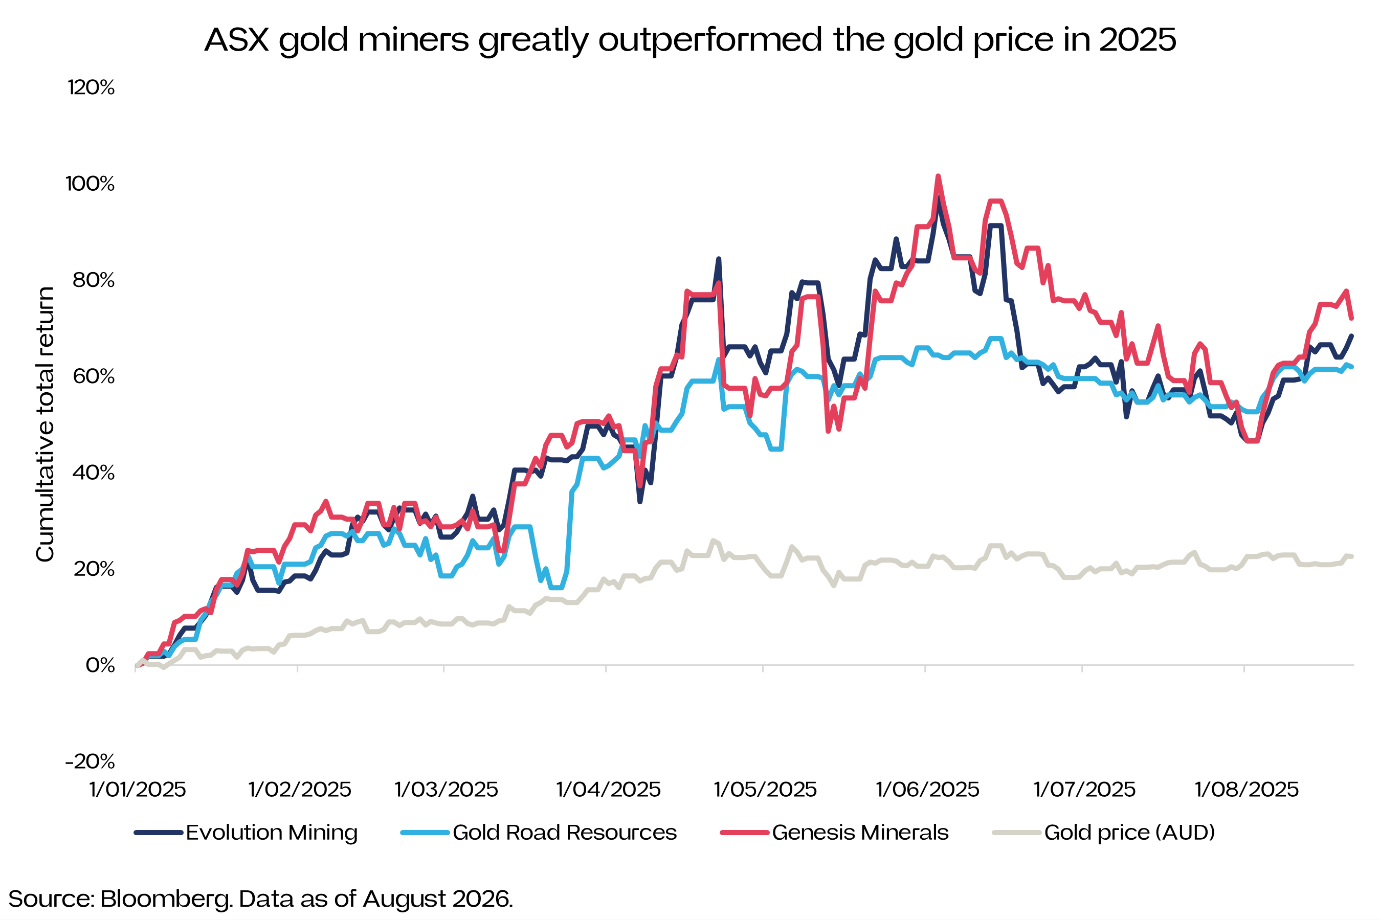
And it was on full display during the gold rally of 2025, when a number of Australian gold stocks dramatically outperformed the metal - Evolution, Genesis and Gold Road among the standout performers.
Of course, leverage works in both directions. If the gold price falls, miners' margins can contract much faster than the underlying commodity price. Investors are taking on operational, cost, management and equity-market risk in exchange for greater upside.
The other advantage: income
Then there is something physical gold cannot provide: cash flow.
A gold bar doesn't pay a dividend. A profitable gold miner can.
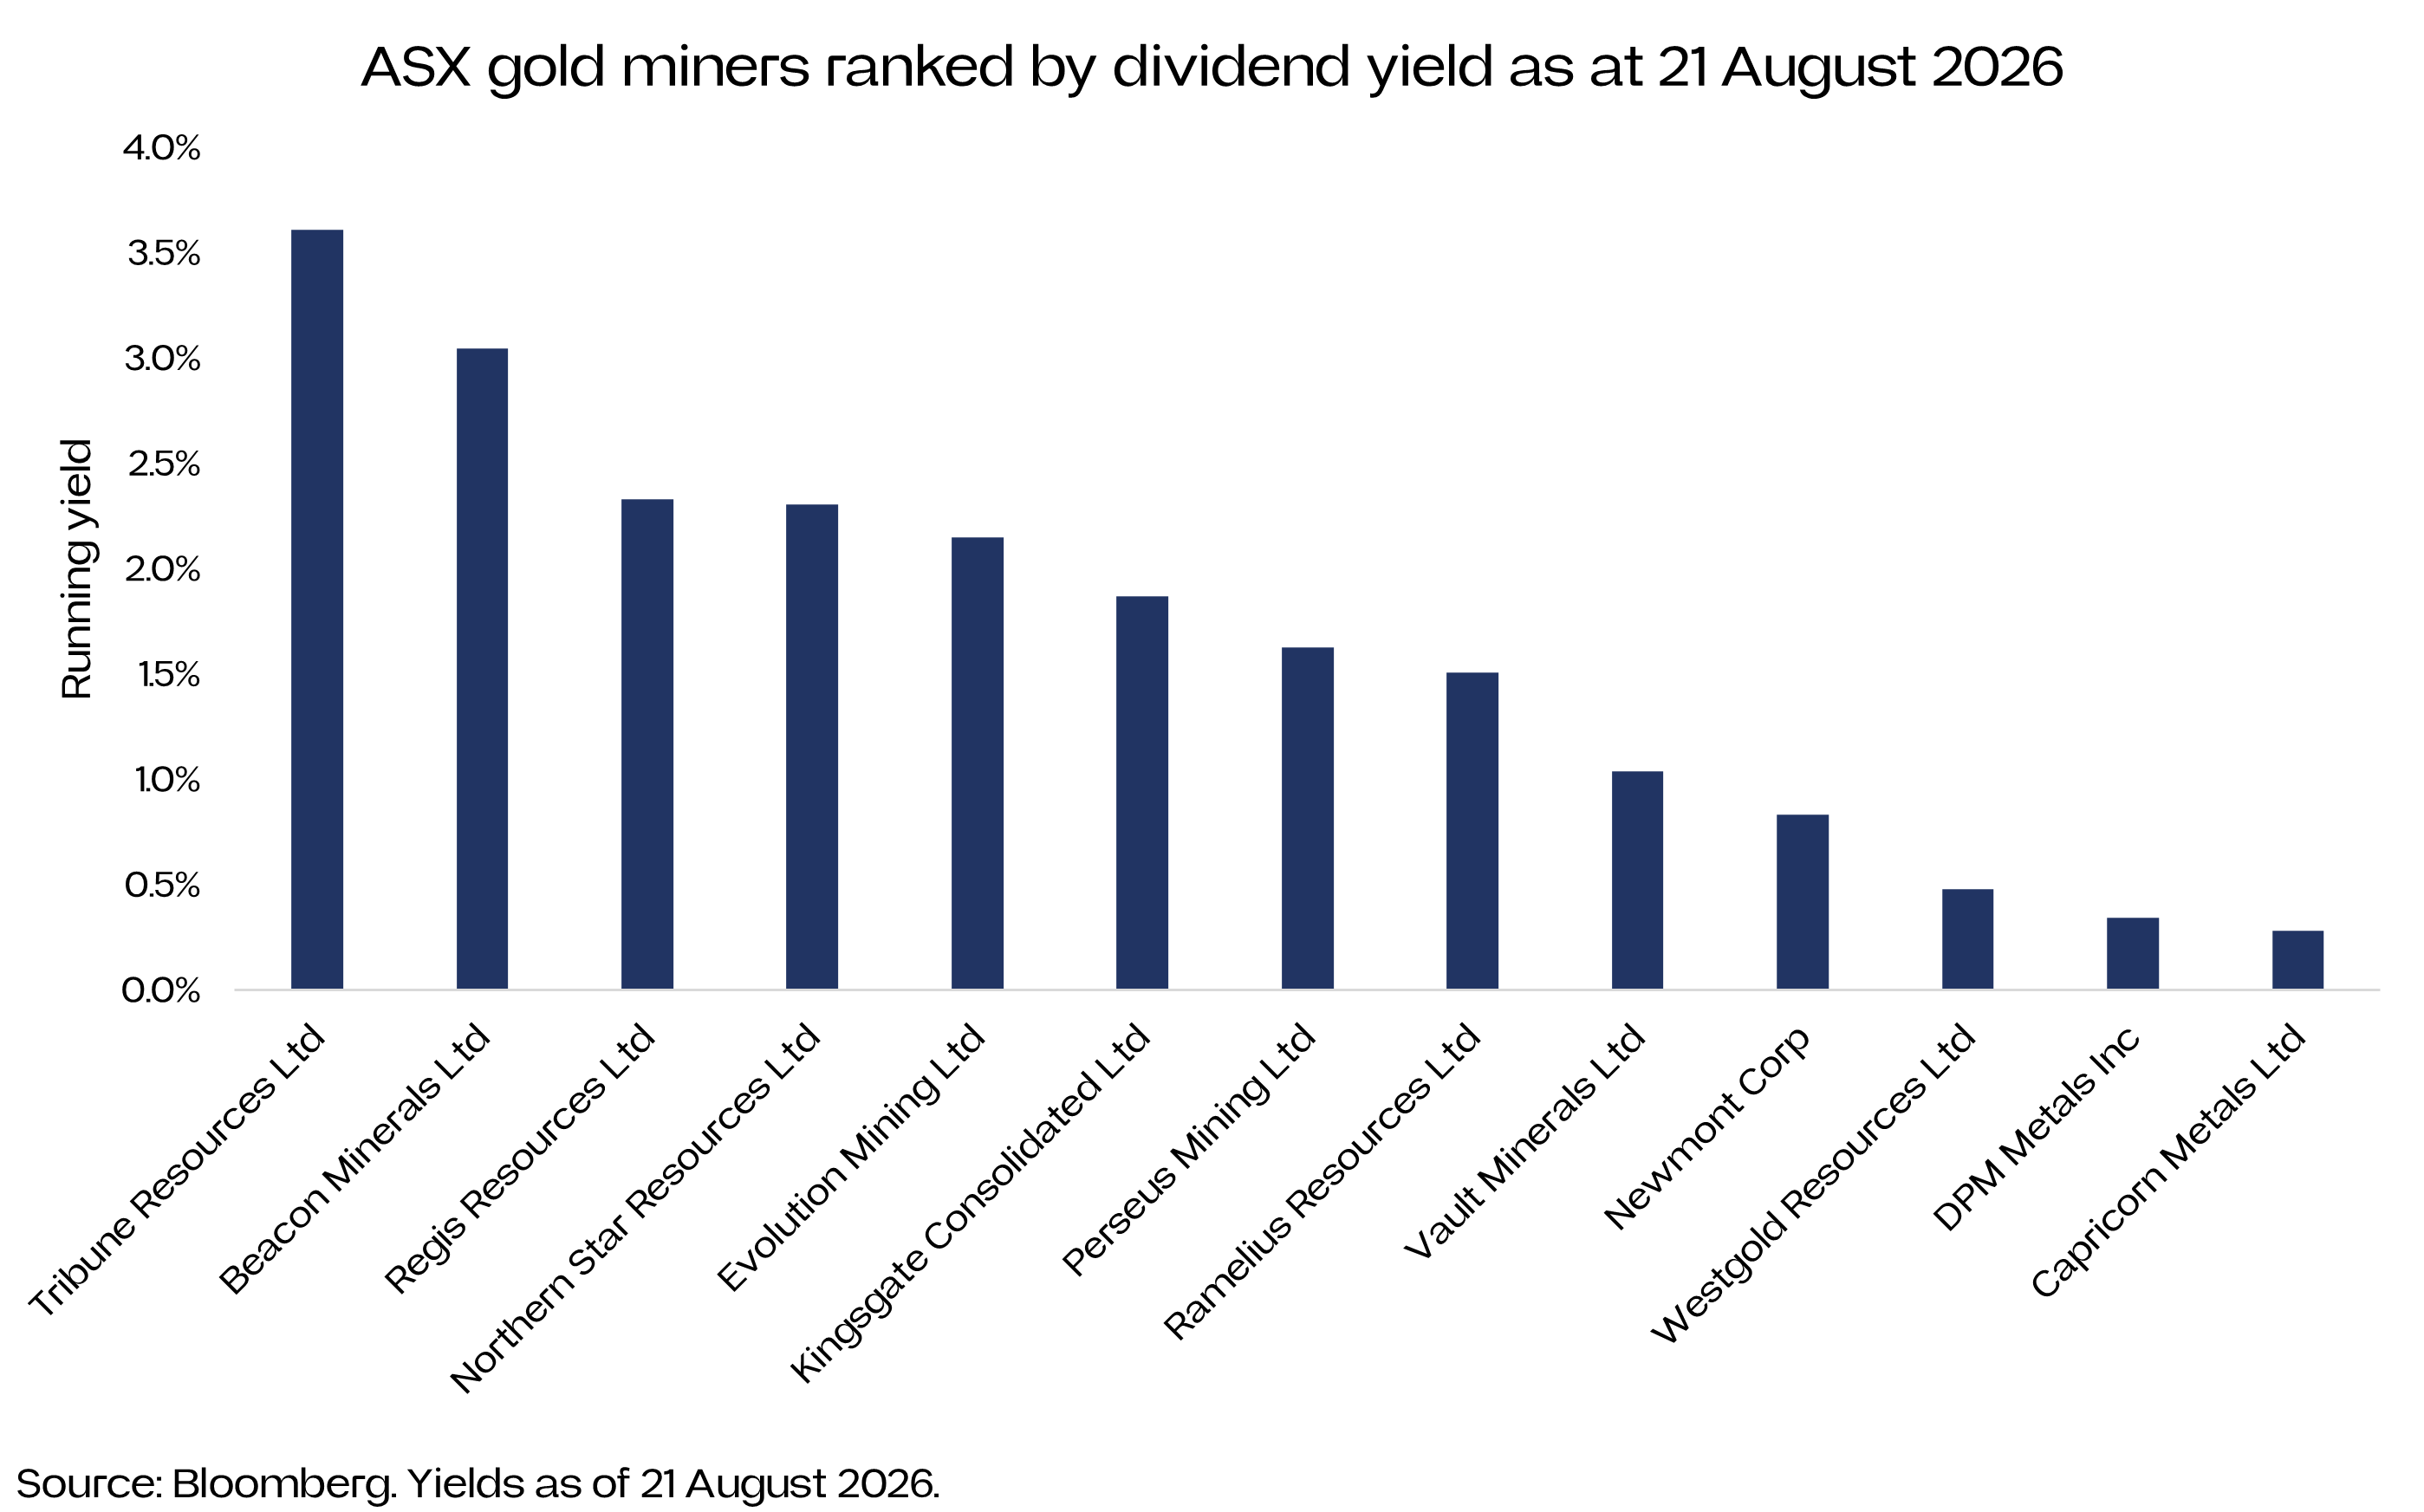
That matters particularly in Australia because many of the country's major miners – Northern Star and Evolution among them – distribute franked dividends while still investing in their businesses.
This creates a different proposition. Physical gold does not generate income, whereas profitable miners may return cash to shareholders through dividends. There is an important caveat, however. Dividends are not guaranteed. A miner can cut its dividend if profits fall, costs rise or management decides capital is better deployed elsewhere. A gold miner should not be thought of as a bond with a gold price attached. It is still an equity.
The curve ball: gold miners are becoming less about gold
There is another complication investors need to consider today. Increasingly, it isn't even clear what constitutes an "ASX gold miner".
The reason is geology. Miners rarely extract one commodity from a mine. Gold mines can contain lots of copper, silver and other metals. Some of the world's biggest mines are valuable because of the combination. BHP's Olympic Dam is the famous example, producing copper, uranium, gold and silver from the same extraordinarily complex South Australian mine.
The same phenomenon is increasingly relevant to the ASX's gold sector. Newmont's Cadia operation in NSW is a major gold mine, but also a substantial copper operation. Evolution Mining's Ernest Henry in Queensland is explicitly a copper-gold-silver operation: Evolution produced 76,261 tonnes of copper alongside 750,512 ounces of gold in FY2025.
This matters more as investors increasingly focus on copper because of its role in electrification, grids and data centre development. It also means buying a "gold miner" is no longer necessarily a pure bet on gold.
That can be either a feature or a bug.
Complements, not substitutes
So, should investors own the metal or the miners? Investors should first decide what role they want gold to play in their portfolio. Those seeking diversification may favour exposure to the metal itself, while those seeking greater upside from a potentially rising gold price may prefer holding the miners. Of course, this recognises the additional risks associated with equities and mining operations.
ETF Shares provides the ETFS Global Pure Play Copper Miners ETF (ASX: CPPR) which began trading on the ASX in April 2026. For more information click here.
David Tuckwell is the Chief Investment Officer at ETF Shares, a sponsor of Firstlinks. He is also a journalist and researcher specialising in finance and international politics. The information provided in this article is general in nature. Before acting on any information in this article, you should consider the appropriateness of the information having regards to your objectives, financial situation or needs and consider seeking independent financial, legal, tax and other relevant advice. Past performance is no guarantee of future performance.
Disclaimer: This article is issued by ETF Shares Management Limited (“ETF Shares”) (ABN 77 680 639 963, AFSL: 562766) and ETF Shares is solely responsible for its issue. Under no circumstances is this article to be used or considered as an offer to sell, or a solicitation of an offer to buy, any securities, investments or other financial instruments. Offers of interests in any retail product will only be made in, or accompanied by, a Product Disclosure Statement (PDS) and target market determination (TMD) available at www.etfshares.com.au.