Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 220

Why the times suit active fixed interest

It is hard to believe, but back in August 1982, the Australian cash rate averaged 17% (the unofficial rate went as high as 19%) and the yield on a 10-year Australian government bond was 16.5%. Some 35 years later, the cash rate is 1.5% and the yield on a 10-year government bond is around 2.6%.

Over this period, the Australian fixed interest sector has been in a structural bull market, propelled by the shift from a high to low inflation environment and demographic factors which lowered real rates. More recently, conventional and unconventional monetary easing has driven yields even lower.

For investors in the sector, the last 35 years have generated handsome returns, even allowing for the 1994 bond bear market. Returns of 9.5% p.a. compare favourably to 12% p.a. from the Australian share market and 7.6% p.a. from cash over this period.
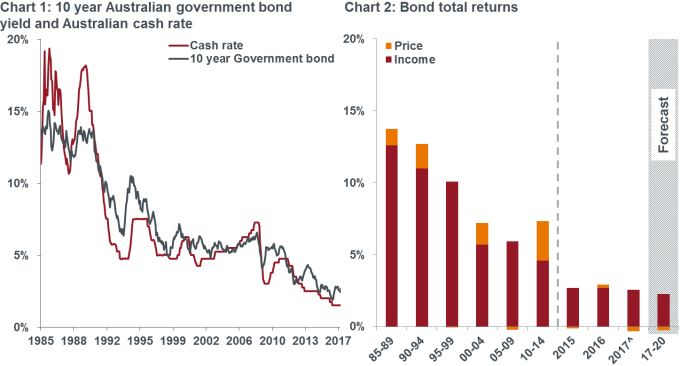

Source: Chart 1: Bloomberg, as at 30 July 2017. Chart 2: Source: Janus Henderson Investors, Bloomberg, Ausbond Indices, UBS, SBC Brinson. Spliced history of Australian Bond market returns. As at 30 June 2017. Forecast numbers are estimated projections only. ^CYTD 2017.

Beware the bull complacency trap

A common trap that investors can fall into is becoming complacent about the risks that may be building up in their sector exposures after a prolonged period of structural change and good returns.

With the global economy enjoying a cyclical recovery and central banks signalling a desire to begin withdrawing high levels of policy accommodation, investors’ attention should focus on two sources of risk embedded in the sector benchmark, the Bloomberg AusBond Composite 0+ Yr Index (benchmark) that have built up progressively since the GFC.

Lengthening benchmark duration = more interest rate risk

Just because the level of interest rates is low by historical standards does not mean that a small rise in rates will have a limited impact on sector returns. Investors need to be aware that since 2009, the duration (a measure of maturity term) of the Australian fixed interest sector has risen from around three years in mid-2009 to around five years currently.

In 2009 when bond market yields averaged around 5.5% and duration was three years, investors’ exposure to interest rate risk was such that a 1% rise in bond yields would have resulted in capital loss of 3%, delivering a total return of around 2.5% (i.e. the income of 5.5% minus the capital loss of 3% from rising bond yields).

Today, with average bond market yields of around 2.5% and the duration of the benchmark around five years, a 1% rise in bond yields would result in capital loss of 5% delivering a total return of -2.5% (i.e. 2.5% income less 5% capital loss). A 0.5% lift in yields would result in flat returns (i.e. 2.5% income less 2.5% capital loss).

Chart 3: Australian average bond market yield and modified duration
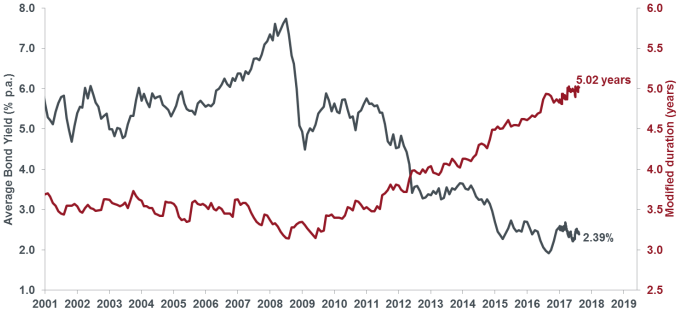

Source: Bloomberg, as at 11 August 2017. Date is monthly to December 2016, daily from January 2017. Australian bond market based on the Bloomberg AusBond Composite 0+ Yr Index.

With the RBA Governor indicating that the next move in rates is likely to be up, investors need to be mindful of the interest rate risk in the sector benchmark. Over the last few years, investors in passive fixed interest products have enjoyed a good run as interest rates fell and the duration of the benchmark lengthened.

Looking ahead, investors in such strategies need to be aware of their exposure to capital loss from even modest rises in rates. By way of example, the yield to maturity on the benchmark lifted from 1.98% at the end of July 2016 to 2.43% at the end of July 2017. With the duration of the benchmark at historically high levels, resultant capital loss more than offset any income, with returns down 0.24% over the period.

We believe active fixed interest strategies or absolute return strategies, where managers are not bound to hold duration at benchmark levels, are better positioned to preserve investors’ capital in a rising rate environment.

Benchmark compositional risk: lower-returning government debt, less diversification

Since the GFC, there has been significant change to the composition of the Australian fixed interest benchmark. The heavy issuance of increasingly longer-dated government debt (federal, state, supra national) combined with corporate deleveraging has hastened the ‘crowding out’ effect in the benchmark. As a result, the market weight of the higher-yielding credit sector in the benchmark has fallen from 36% in 2008 to around 8% in 2017 currently.

Investors in passive index strategies have progressively lost access to both the higher yields available in the credit sector and diversification benefits of broader holdings in the benchmark. Longer-dated government debt has increased the interest rate risk. The past year highlights the importance of active interest rate management in navigating the gradual reversal of the bond bull market.


Jay Sivapalan is Portfolio Manager, Fixed Interest at Janus Henderson Investors.


  •   21 September 2017
  • 1
  •      
  •   
1 Comments
Warren Bird
September 21, 2017

I'm going to sound like a broken record, but the attractive returns have not been because of falling yields or 'a bull market'. Bond market returns have actually declined because of falling yields. The hint is in the article itself - at the start of the 35 year period ten year bonds paid an annual return of 16.5%. That the average return over the 35 years since has been only 9.5% is because yields declined through time. If we hadn't had this alleged "bull market" we'd have had average returns over 35 years of 16.5%.

I do have sympathy with the general premise of the article, because it's unusual for any bond index to align closely with investor risk preferences for term or default risk composition. But the old 'structural bull market' argument is not only not necessary for making the case, it's actually factually incorrect that such a thing has happened.

The flip side is that, though bond yields are now only around 2.5%, if they rise over the next decade or two or three, bond returns will increase. All the fear about how 'bad' it will be for investors if rates go up will be long forgotten then - the short term decline in capital values will be swamped by increased reinvestment income and higher coupons down the track.

Perhaps you need a career that has spanned a 35 year period to be able to take a 35 year view like I do, but I can honestly say looking back over 1982-2017 that all the short term bull and bear markets in bonds are just noise. The driver of the returns from this asset class is income, not capital.

Yes, active managers in theory should "preserve capital" in a rising rate environment - and bravo if you do. But my memory of, say, the 1994 bond sell-off is that the biggest mistake active bond managers made was that they didn't go long duration again at 10% yields in 1995. Looking back, the income foregone by not jumping on board then was far more significant than the short term capital lost by not having been short in 1994.


Leave a Comment:

RELATED ARTICLES

The best opportunities in fixed income right now

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.