The laws of supply and demand have an inevitability to them and recent moves in the uranium market are another reminder of their power. Back in September 2023, uranium was selling at around US$50 a pound. As we write, that price has moved to $US91/lb.1 In this article we look at the supply and demand dynamics underpinning that rise.
Bottomed out
For over a decade, the uranium market has been plagued by excess supply, low prices and negative sentiment around nuclear power. Between 2014 and mid 2021 for example, prices hovered around US$30/lb. For context, it last peaked at US$136/lb in 2007.
On the demand side a number of factors kept the main buyers – utility companies - from paying up for the radioactive metal.
- High levels of global inventory and product availability.
- The progressive retirement of Japan’s nuclear fleet post the Fukushima tsunami. Before 2011, nuclear accounted for 30% of Japan’s energy. By 2019 Japan’s nuclear energy output had fallen by 75%.
- Anti-nuclear sentiment in Europe drove a nuclear phase-out in many countries (notably Germany).
Meanwhile, the supply of uranium was increasing, largely thanks to low-cost production from Kazakhstan. With plentiful supply and cratering demand, energy utilities were able to buy uranium at low ‘spot’ rates rather than contracting for long-term supply. The uranium price fell briefly below US$20/lb.
At sub US$30/lb, many uranium mines became uneconomic and were placed into ‘care and maintenance’.3 That led to a dramatic fall in mined production.
Something changed
In the early 2020s the supply/demand dynamic changed and the uranium price made two dramatic jumps, leaping from $US30/pound to $US50/pound in 2021 and $US50 to $US100/lb in 2023. What’s behind this shift?
- The emergence of uranium ‘trusts’. These vehicles buy physical uranium, thus removing excess global uranium inventory from the system.
- An improving demand outlook driven by a resurgence in nuclear power. China’s annual uranium demand is expected to nearly quadruple to over 40,000 tonnes per year by 2040.
- Japanese reactor restarts, life extensions for ageing plants and development of new technologies (such as small modular reactors). These are all incrementally positive for uranium demand.
- Sustained supply deficits, with long lead times to develop new supply.
- The self-sanctioning of Russian material after its invasion of Ukraine put further strain on an already underprepared nuclear value chain.
Underpinning all these factors is the increasing realisation that nuclear power could be key to decarbonising energy. Nuclear provides reliable baseline power and, unlike fossil-fuel fired power plants, nuclear reactor lifecycle carbon dioxide emissions have a profile on par with renewables.
In essence, there’s been a huge supply/demand switch and for the first time in the history of the uranium market as we know it, we may see a sustained shortfall of available supply – and it’s beginning to be reflected in the price.
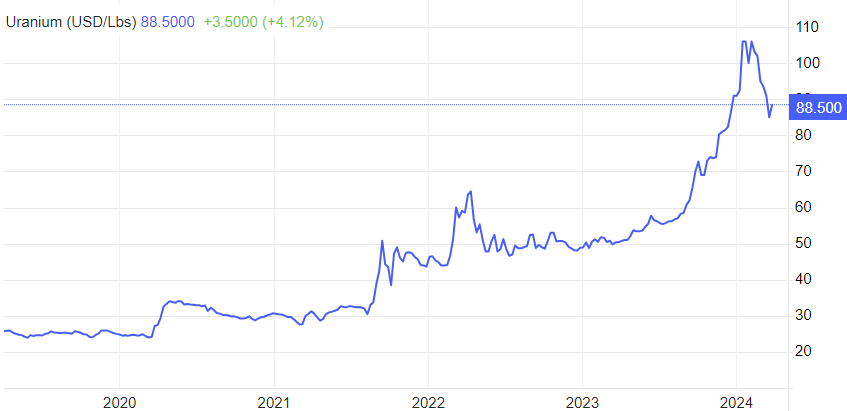
Source: Trading Economics
That’s why uranium is now a key portfolio theme for the Platinum Global Transition Fund2 (Quoted Managed Hedge Fund) (ASX:PGTX) - a fund specifically designed to provide capital growth over the long term by investing in undervalued companies that are seeking to financially benefit from the transition away from fossil-fuel derived energy and goods production and consumption i.e. the carbon transition.
In the midst of this major market shift, PGTX added four uranium stocks to the portfolio - Cameco and the Sprott Physical Uranium Trust (SPUT) from Canada, Kazakhstan’s Kazatomprom and Australian developer Paladin Energy.
These four stocks have very different – and somewhat complementary - characteristics.
- The Sprott Physical Uranium Trust owns physical uranium and gives pure exposure to upside in the uranium price.
- Cameco is a large, high-quality producer that provides exposure across the nuclear fuel cycle.
- Kazatomprom is the largest upstream producer of uranium. It’s a dividend paying stock, valued at a discount to its peers.
- Paladin Energy is a late-stage development company that provides exposure to near-term production and so favourable exposure to market pricing.
Buyers who look past the price
Whilst supply and demand fundamentals drive markets, buyer behaviour is also crucial. Indeed, understanding the behavioural element in markets is core to our investment philosophy.
Tellingly, the prospects for further strength in the uranium market are improved by the buyer behaviour of the big energy utilities. Constrained supply means these buyers can no longer look to source uranium in the spot market. They’re now looking for the supply certainty of long-term contracts.
Utilities are now genuinely concerned about lack of supply and that means they could start looking ‘past the price’.
For them, a US$20/lb move in the uranium price equates to a roughly $1 per megawatt-hour (MWh) increase in fuel cost for their reactor. That won’t change their behaviour given the importance of keeping the reactor running and especially in the context of the huge capital cost of their plants.
Given the depth of the current supply issues – and the fact it could take until 2030 or beyond for meaningful new supply to come on stream - these conditions could last for years.
Today, we’ve got a market driven by price-inelastic buyers who are motivated almost solely by supply worries - literally by fear of running out. That could see very high prices sustained for a number of years. And that’s good news for companies in the uranium sector.
1 Source: Factset Commodities as at 08/03/2024
2 The Platinum Global Transition Fund invests in undervalued companies from around the world that are seeking to financially benefit from the transition away from fossil fuel-derived energy and goods production and consumption i.e. the carbon transition
3 When mines temporarily stop producing but the infrastructure and machinery is maintained and environmental risks managed.
Platinum Asset Management is a sponsor of Firstlinks. This information is commentary only (i.e. our general thoughts). It is not intended to be, nor should it be construed as, investment advice. To the extent permitted by law, no liability is accepted for any loss or damage as a result of any reliance on this information. Before making any investment decision you need to consider (with your financial adviser) your particular investment needs, objectives and circumstances.
For more articles and papers by Platinum click here.