Division 296 has long been framed as a tax on the ultra-wealthy, but new data suggests it is likely to reach far deeper than the headline $3 million threshold implies.
The standout finding from Class's benchmark data is not the number of members already caught by Div 296. It is the sheer stockpile of unrealised gains sitting inside SMSFs. Nearly three-quarters of funds held a positive net unrealised capital gains position at 30 June 2026, averaging around $620,000.
Among funds with a member balance above $3 million, that figure jumps to $2.2 million and rises to almost $8 million for those with balances above $10 million
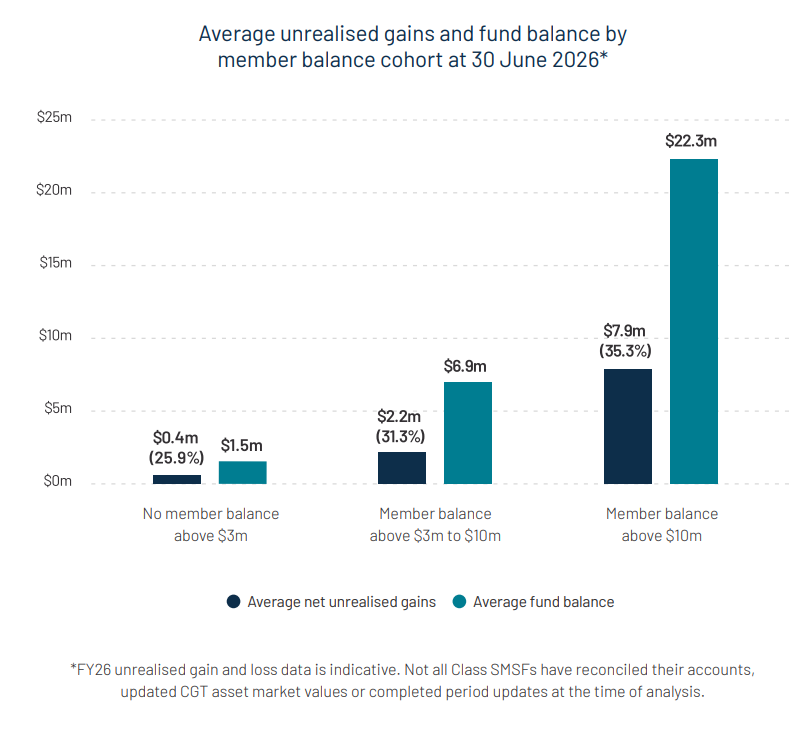
The legislation offers a one-off opportunity to reset the cost base of all CGT assets to market value as at 30 June 2026 for Div 296 purposes. This is an all-or-nothing election. Trustees cannot cherry-pick assets and once the decision is made there is no turning back.
The instinctive assumption is that this is a problem for today's wealthy SMSFs. Yet there are a number of funds standing just outside the spotlight. Only 8.8% of Class SMSFs currently have a member balance above $3 million, but another 9.4% sit in the $2-$3 million range.
Many who consider Div 296 someone else's problem may discover it is only a matter of time before it becomes their own.
Residential LRBA restrictions may have more impact than expected
The debate around borrowing in super has largely fixated on the size of the market. The more important question is whether policymakers underestimated just how embedded residential property leverage had become in the SMSF psyche.
In the year before the restriction on new residential property LRBAs took effect, almost 93% of all LRBA holdings on the platform were tied to residential property. Interestingly, Class identified 3,672 new residential property LRBA holdings in FY25. This points to an estimated 11,500 new arrangements across the broader SMSF sector if extrapolated nationally. It’s hard to argue this is a niche strategy in its twilight years.
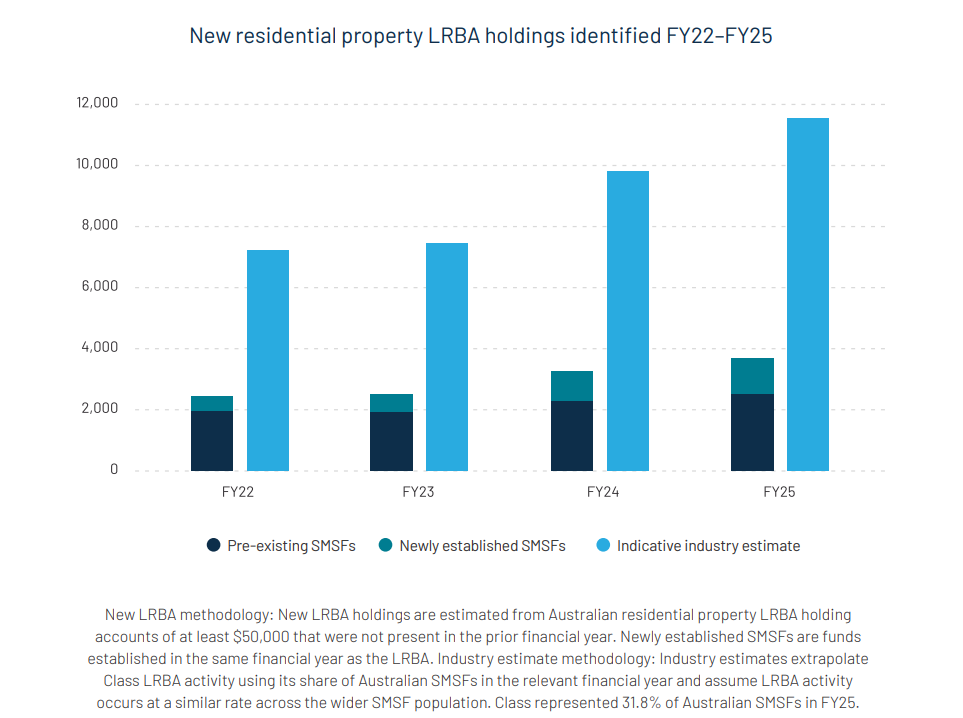
The strongest growth came from newly established SMSFs where residential LRBA activity more than doubled over 2 years. Perhaps that suggests the SMSF proposition was increasingly being built around the national conviction that property financed with debt remains the surest path to long-term wealth.
This partially challenges the notion set by policymakers that may have viewed residential borrowing as a relatively contained feature of the SMSF landscape. There appears to be far broader participation and stronger growth than many expected.
Asset allocation
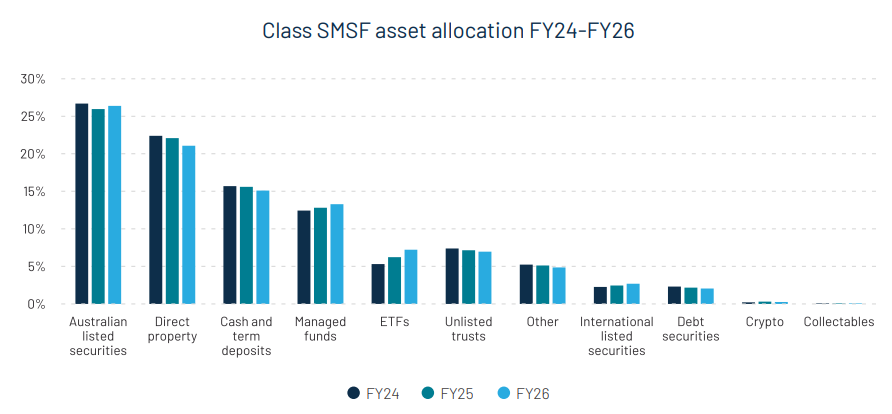
Listed Australian shares and direct property remained the two most popular assets, accounting for 26.4% and 21.1% of assets respectively. The most obvious movement was in ETFs, which increased 1% to reach 7.2% of assets, overtaking unlisted trusts.
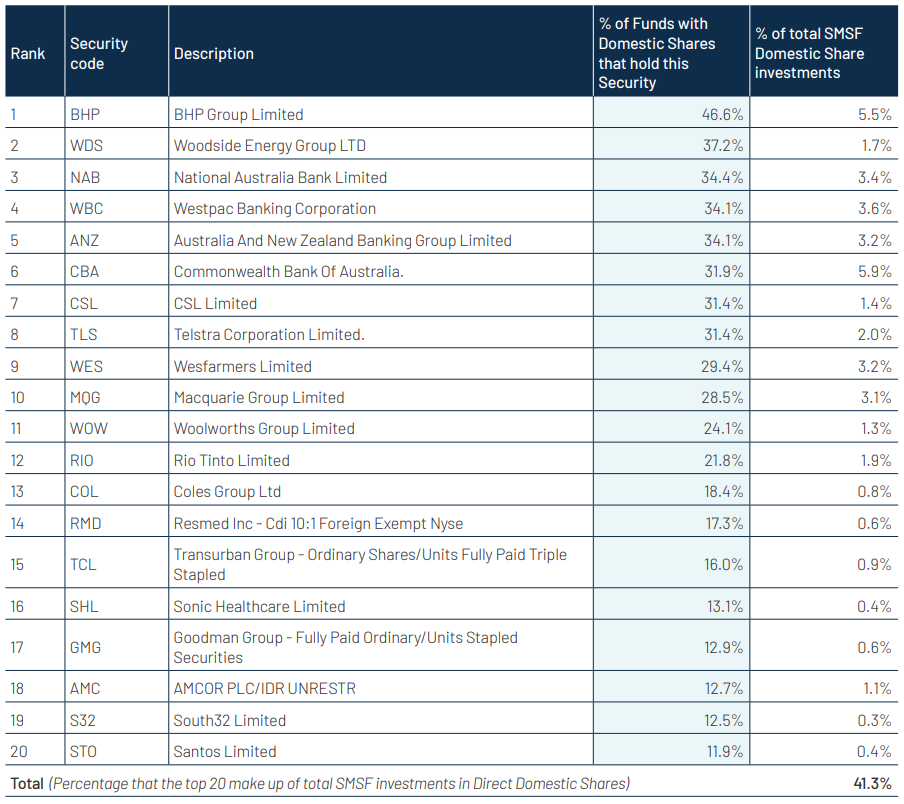
On the ASX side, the old guard firmly maintains control of many SMSF portfolios. BHP and Woodside remain the two most widely held Australian shares but what's perhaps more interesting is that their popularity is declining. Both fell from FY25, when BHP was held by 49.0% and Woodside by 41.8%.
Notably, Amcor returned to the top 20 in FY26, ranking 18th and held by 12.7% of funds with direct domestic shares, while Endeavour Group dropped out.
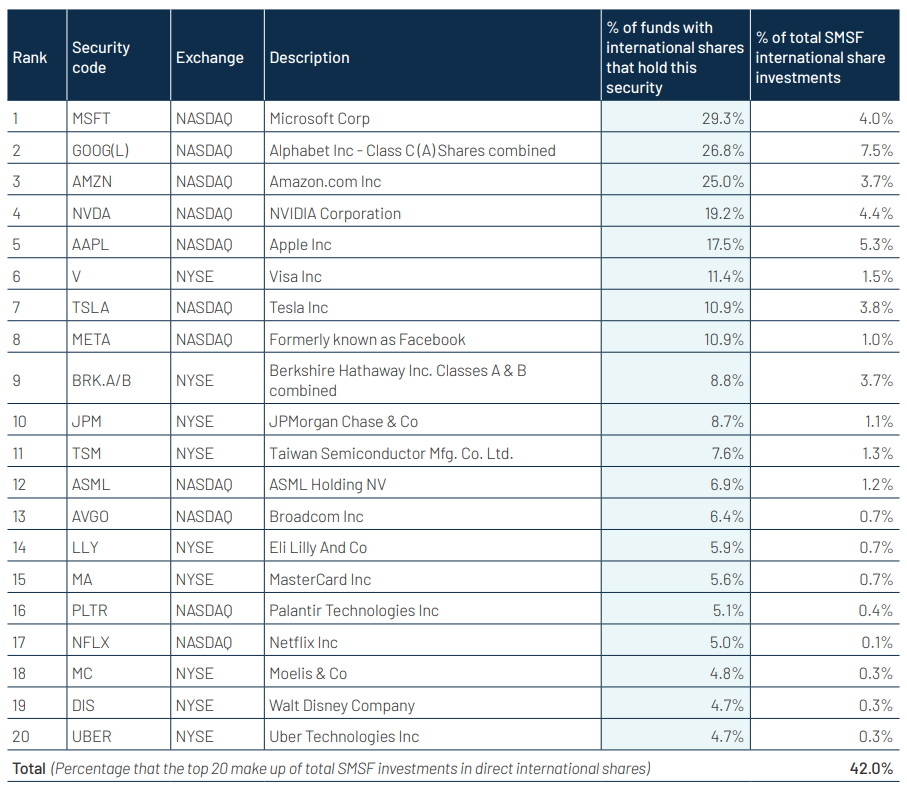
On direct international shares, the technology behemoths continued to dominate. The top three were unchanged from the previous year - Microsoft (29.3%) remaining the most popular holding, followed by Alphabet (26.8%) and Amazon (25.0%).
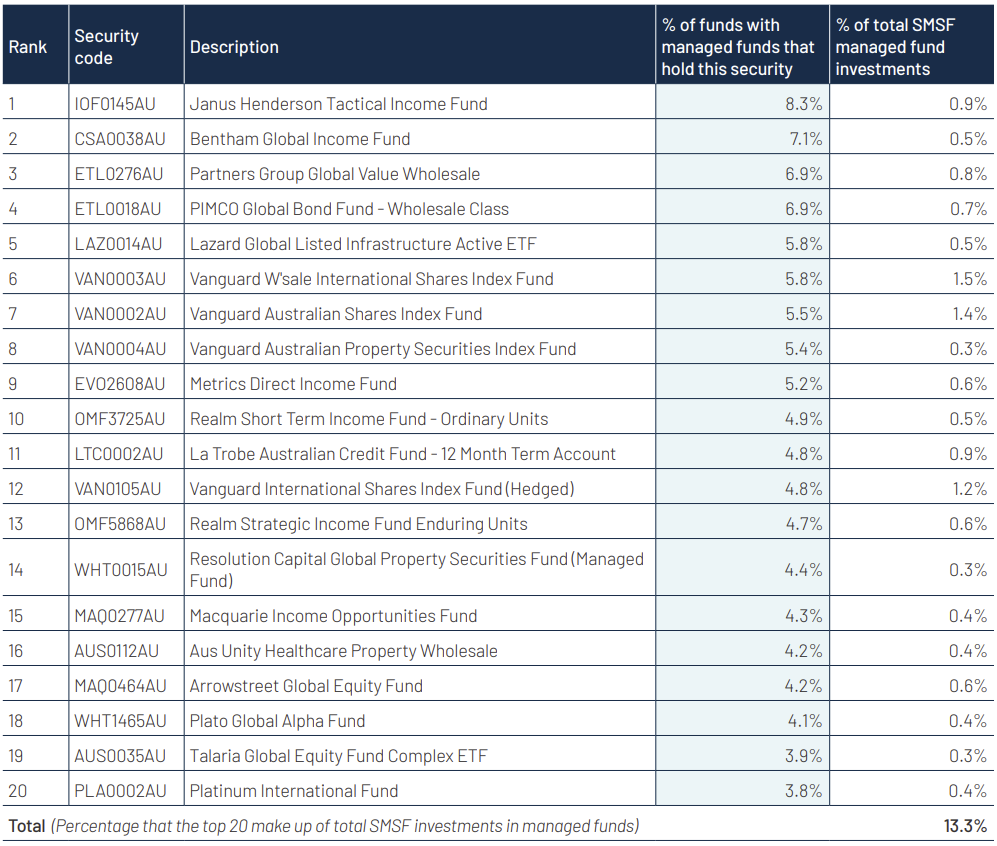
One notable feature of the data is the composition of popular managed funds. Income-focused funds continue to dominate rankings where the Janus Henderson Tactical Income Fund retained the top spot (8.3%), while Bentham Global Income Fund moved from fourth to second, held by 7.1% of funds.
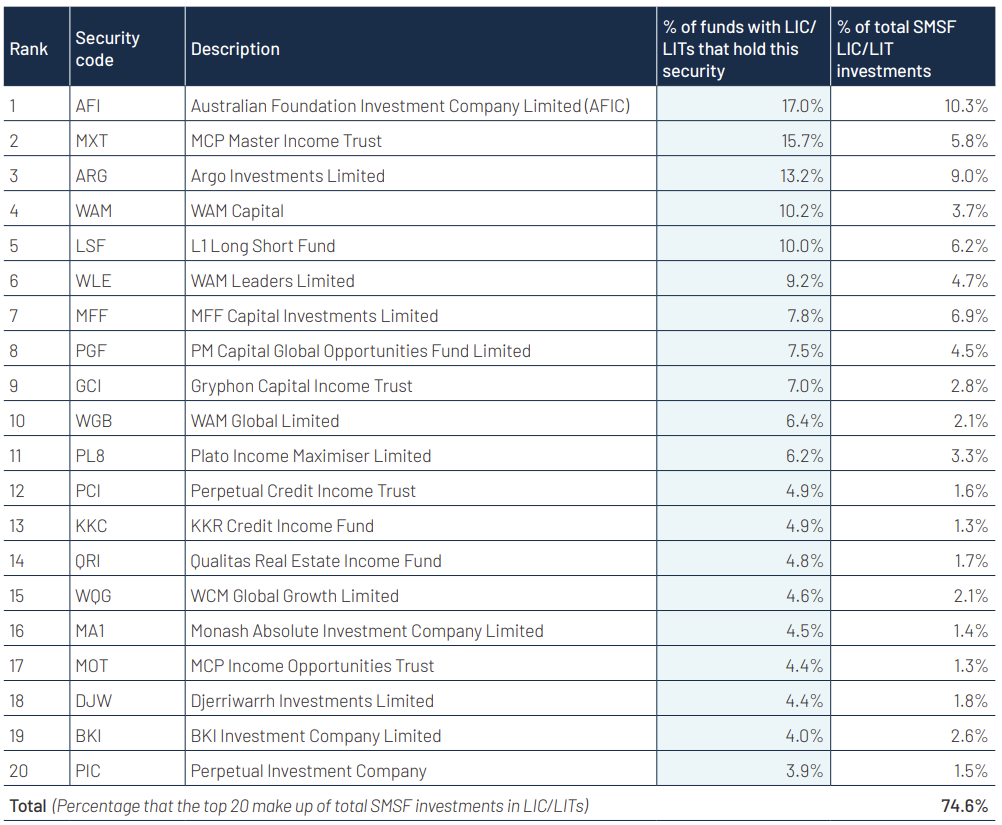
The most popular LICs generally stayed consistent in FY26, though AFIC, Metrics, ARGO and Wilson Asset Management saw some mild attrition.
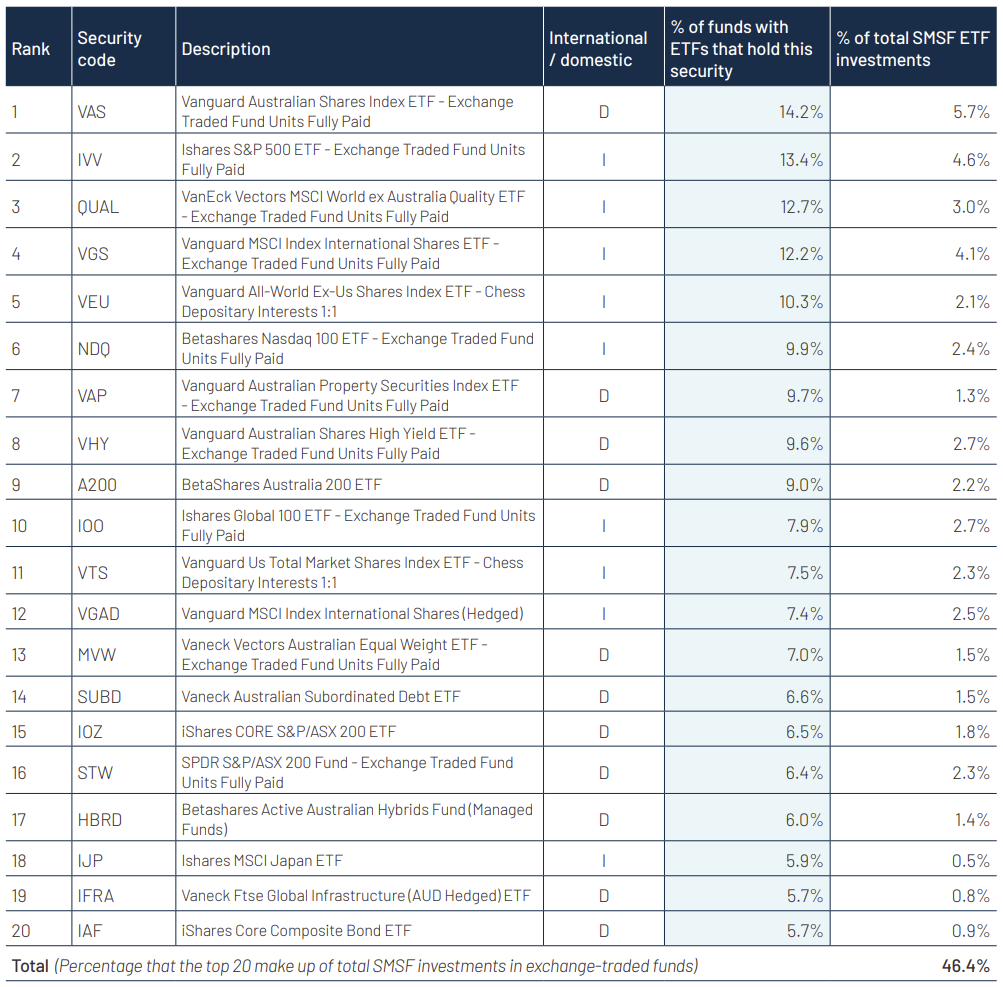
Lastly, the conversation wouldn't be finished without a mention of ETFs, which continued to gain popularity among Class SMSFs with 36% holding at least one in FY26. Vanguard endured as the largest ETF provider by market value, followed by Betashares, BlackRock and VanEck. Together, these four providers accounted for 81% of ETF assets held by Class SMSFs.
Six of the 10 most popular ETFs in FY26 provided international exposure. Vanguard's Australian Shares Index ETF continued to hold top spot, meanwhile VanEck's MSCI Index International Shares ETF was dethroned from second place by the iShares S&P 500 ETF.
Simonelle Mody
Also in this week's edition...
After a high-profile dividend cut and a prominent fund manager’s apology, David Tuckwell argues why he thinks the LIC structure needs to die.
Elyse Dwyer and Nick Garvin model two decades of housing data to determine the winners and losers of the new housing tax reforms.
Proposed trust tax reforms could force families to rethink estate planning. Felipe Araujo details three things to consider before making any changes.
Neil Rogan examines why the biggest investment risk is often disguised as research and sensible risk management.
Active managers largely fell short in 2026 despite the odds stacked in their favour. Russel Chesler explores an alternative strategy that has continued to make its case.
Despite a sharp fall in equity valuations in the past year, investors have largely been spared. Amr Hanafy and Jeff Blazek propose five key drivers behind this.
We worry about AI becoming conscious. But what if consciousness isn't the issue? Tony Dillion asks the question on everyone's mind - has AI gone rogue?
Curated by Simonelle Mody and Leisa Bell
A full PDF version of this week’s newsletter articles will be loaded into this editorial on our website by midday.
Latest updates
*** We have had numerous readers ask what has happened to the ASX Listed Bond and Hybrid Rate Sheet that was published each week. Unfortunately, the NAB Markets team recently decided to discontinue its production, so we can no longer make it available to you. Instead, you might like to access the monthly bond and hybrid reports or prices pages that are published by the ASX (links can be accessed via our Education Centre section). ***
PDF version of Firstlinks Newsletter
LIC (LMI) Monthly Review from Independent Investment Research
Listed Investment Company (LIC) Indicative NTA Report from Bell Potter
Plus updates and announcements on the Sponsor Noticeboard on our website