Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 309

4 reasons why cash is a core portfolio allocation

Cash has often been a source of confusion for investors. Some people do not consider it an investment class in its own right but more as a ‘balancing’ or ‘residual’ item after all other investments have been made. However, there are compelling reasons why cash should be considered a core portfolio allocation item.

Investors who see holding cash as a missed opportunity in other investments may deliberately minimise the allocation. In poor markets, this mentality creates problems, because cash cannot fulfill its role to support the portfolio and act as a bastion of certainty.

To understand cash’s true value, investments should be measured on a risk-adjusted basis, which puts the cash return in a much more favourable light.

There are four interconnected reasons why all investors should consider cash as core.

1. A new dimension of uncertainty and volatility has entered markets

Markets are now more prone to moves that are extremely difficult to anticipate or forecast. Price discontinuity and volatility is partly due to four dynamics at play in markets:

  • Globalisation: Financial markets are now more influenced by the financial and trade interconnections. These markets are continuously being affected by factors operating in other parts of the world. For example, China has evolved quickly in recent years as the number two economy in the world with a profound economic influence in our region. Our economic and financial models need recalibration but we simply have not had enough time to understand China’s influence on global trends or Australian financial markets with much precision.

  • Changes in the political and geopolitical spheres: New forces and trends are emerging with direct flow-through effects to the way markets behave, including the way government finances and central bank monetary settings are managed. Two examples are: first, the emergence of ‘populism’ with new reactive politics from both the left and the right sides; and secondly, demographic and cross-generational trends where baby boomers vie with the millennials in an economic and wealth battle. This will accelerate as the baby boomers move into retirement and the sheer number of millennials and the older Gen X out-vote the baby boomers.

  • Growth of large institutions and their use of algorithms: The use of complex, ‘opaque’, mathematics-based algorithms by large funds means markets can move indiscriminately, quickly, and even violently if certain market price levels are reached. Algorithms can be ‘correlation-based’ whereby price levels in several markets need to be simultaneously breached before trading action is invoked. Price movement may trigger further algorithm-based trading. The volume of trading potentially released can overwhelm markets and cause significant dislocation.

  • Uncertainty and illiquidity: Price volatility increasingly occurs in unpredicted ‘jumps’ and is a major source of illiquidity and even severe dysfunctionality in markets. Illiquidity exacerbates problems for investors looking to exit securities and needs to be assessed in any investment model.

Potential illiquidity and uncertainty can be risk-managed via a designated percentage of portfolio assets in cash, with the percentage in cash increasing if there is a perceived risk to these price jumps. This cash component needs to be considered a core volatility and uncertainty management tool.

2. Cash is both certain and available

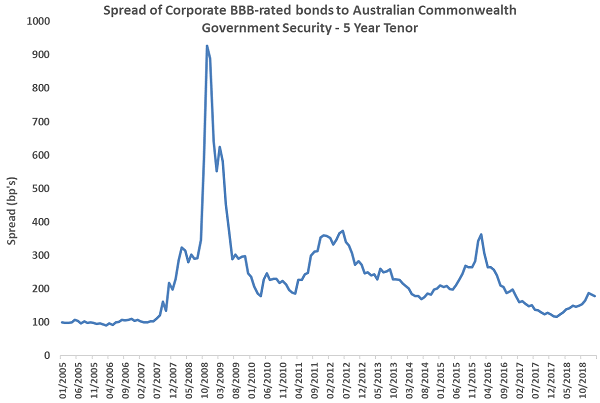
Being certain and available provides real value to a portfolio, yet these attributes are often not measured or given their true importance in risk-adjusted returns. All markets trade essentially as a premium to the risk-free government rate. The premium reflects the extra return required to hold an investment, to compensate for the additional risk. This extra return or premium is seen in capital asset pricing models, which calculate the cost or return on capital deployed, by reference to a premium to the risk-free government rate.

The chart below shows one measure of risk premium, being the premium of five-year bonds issued by BBB-rated companies over the Australian Government bond yield, as compiled by the Reserve Bank of Australia. It shows how the spread was bid very low pre-GFC, spiked violently during GFC, and now has settled back to again to a low level.
core portfolio allocation

core portfolio allocation

Premia are low currently because of the long rally in equities and bonds. While still low in property markets, premia are higher now than in 2018. Premia are also low due to structurally-low inflation and interest rates, which means investors have been prepared to bid up the prices of risk-assets to abnormally high levels.

3. Equity markets can turn quickly

Equity markets are reasonably buoyant at the moment, but can turn quickly, making cash (and liquidity) important. Cash returning only 2.0-2.5% may be considered a lame or even unworthy investment, however if the equity market falls 10%, this cash return will look stupendous. Diversification across different markets may not help a portfolio during a significant market fall, as markets often become more correlated during extreme events.

4. The emergence of cash-plus and cash-enhanced funds

Cash-plus and cash-enhanced funds allow investors to earn a higher return on a risk-adjusted basis compared to traditional cash investments. This means cash holdings can be ‘put to work’ more effectively and earn a decent return. Again, applying the risk-adjusted return methodology, these funds generally contain more risk that traditional cash at bank, hence they may allocate only a portion of their ‘cash’ to the cash-plus fund sector.

Cash can be king

‘Cash is king’ is often the plaintive cry when markets have already moved. While cash may not always be king, it should not be relegated in status to the ‘poor cousin’ especially in today’s markets with new dimensions and sources of price volatility. Cash holdings should be held as a legitimate, wise and prudent form of ballast in a diversified investment portfolio. Cash-plus and cash-enhanced funds provide a ready way for funds to enhance other traditional forms of cash investments.


Matthew Lemke is the Fund Manager of the Prime Value Cash Plus Fund. Matthew has worked in the securities market for over 35 years. This article is for educational purposes and is not a substitute for tailored financial advice.

  •   5 June 2019
  • 4
  •      
  •   
4 Comments
SMSF Trustee
June 11, 2019

In my portfolio, cash is cash, but cash-enhanced is not.

The minute you introduce credit risk or duration risk into a portfolio it stops being cash.

The article makes a reasonable case for true cash in a portfolio, but the case for having cash-enhanced or cash-plus is a different argument. Those arguments are most compelling for institutions that have to hold some cash for regulatory reasons (eg to meet a liquidity target), but don't really need the risk-free return of true cash, so they can take some marginal additional risks and yet can still call it 'cash' for legal purposes.

For individual investors, such as an SMSF, why not just take those risks by investing in a credit fund or a fixed income fund with aggressive alpha seeking ranges, rather than pretending you're still invested in 'cash'? That's what I do.

peter
June 12, 2019

Cash plus and cash enhanced sounds too similar to the reclassification of debt that went on prior to the GFC. As a trustee I have no means I have found to determine risk in these categories and find some solace in investing in shares as at least I know what the companies do!

Warren Bird
June 13, 2019

Peter, I think that's an unnecessary perspective. Cash plus or cash-enhanced funds are simply funds that invest in cash and take a few additional risks, such as holding some corporate bonds, or longer term bonds.

The 'reclassification of debt .... prior to the GFC' that you're talking about actually took investments away from cash plus funds at the time, as structured debt issues promised very high returns and a AAA rating. Many investors, including local councils, were lured by promises of 8% returns when cash was around 5% and cash plus funds were delivering a nice, steady 5.5-6.0%

I have a clear memory of this, from being on a panel at a conference in Sydney in around 2006. I shared my opinion that those AAA rated securities were structurally high risk and that if something did go wrong with them, it would go badly wrong. I said you can't be getting paid an extra 2% per annum for no risk!

Yet from the floor of the conference there were finance people from local councils who responded that I was just hiding my own incompetence, that I wasn't smart enough to get 8% risk free like the folk arranging those deals and that my nice, safe cash plus fund was just letting them down.

Those same council people then had the audacity to say to a judge in court that they were never warned of the risks of the securities that had blown up in their face. They were warned, not by the arrangers of course, but by me and other managing the cash plus funds that they abandoned at the time. They simply chose not to listen.

Of course, some cash plus funds also went into those structured instruments, so I'd never give a carte blanche support for any manager who called their fund 'cash plus'. But the typical fund with that sort of name isn't guilty of the behaviour that you've mentioned.

Philip Carman
June 13, 2019

Warren, you're potentially making the same or a similar mistake to those silly Local Government people you tried to warn back in 2006. "Enhanced cash" is meddled with. It's no longer cash, but a mixture and those longer term bonds and corporate bonds (can we presume you make a distinction? - perhaps government/semi government bonds?) can fall in value substantially and/or become illiquid, so anyone investing in an enhanced cash fund needs to be aware of that.


Leave a Comment:

RELATED ARTICLES

Six guidelines on how to allocate SMSF cash

What is 'cash' and why it matters

How exposed is your portfolio to the AI story?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.