Adam Grotzinger is a Senior Portfolio Manager at Neuberger Berman, the manager of the listed NB Global Corporate Income Fund (ASX:NBI). Neuberger Berman manages almost $500 billion across all asset classes in 35 offices worldwide.
GH: Why do individual Australian investors and SMSFs underallocate to bonds compared with Australian institutions and particularly overseas individuals?
AG: A few reasons. Australia does not have a heavy bond issuance calendar and there’s not a big local bond market that retail investors access. If you're a domestic investor, it's natural to invest in your local market. Yes, there are government bonds, but outside of that, supply is choppy. It’s different overseas. Those are bigger, deeper, more liquid bond markets, particularly in high-yield bonds.
Investors here traditionally achieved a good fixed income return in term deposits but that's eroded now, and it’s likely to get worse. Adding to that, investors had bank capital securities such as shares or hybrids to achieve an income stream. That has worked well in the past but people are now thinking harder and deeper whether that is achieving their goals, and how much concentration risk are they taking.
GH: Indeed. Bank TDs, bank shares, bank hybrids … it’s all an exposure to residential property, the same as their house and perhaps investment property. And people think they’re diversified.
AG: Yes, and with the low level of rates in Australia, investors are looking abroad and saying, “Actually, there are better yield opportunities out there. And some of those give me a different type of exposure than I have here.” And that's powerful because it's further diversifying their portfolios with a yield element to it.
More people are entering retirement and there’s greater desire to reduce the price volatility in portfolios, and prioritising consistency of income. So there’s a demographic argument as well.
GH: Tell me about Neuberger Berman. How does a business with almost $A500 billion under management and 600 investment professionals coordinate its investing? How does an individual Portfolio Manager have a say in the portfolio?
AG: We're comprised of various teams managing money in different parts of the capital markets. One of the larger teams manages corporate credit, comprised of 55 people managing US$60 billion of assets for clients globally. In the context of NBI (Ed, the listed Australian vehicle, ASX:NBI) in the corporate bond market, we have analysts, portfolio managers and traders in the team. The analyst jobs are sector- or industry-specific coverage, and the companies issuing within those industries. They are accountable and compensated and responsible for their views on which companies will outperform. The analysts make formal recommendations to the broader group, and the vetting of the decisions is done by our credit committee.
GH: So the actual investment decision is made by the team?
AG: Yes. It’s highly integrated. The analyst makes the case to credit committee, but the credit committee is comprised of the analysts, the co-heads of research, all the senior Portfolio Managers. The buy decision must be unanimous.
GH: Unanimous is quite a hurdle with so many people involved.
AG: We’ve done this for 20 years and in many cases, we have a lot of documentation and a rich history of these companies that we've covered for many years.
GH: The breakup of your portfolio is about 90% into BB and B rated bonds but there's a 7.5% piece which is CCC. How are you comfortable with these non-investment grades?
AG: When we think about the high-yield corporate bond market, the rating definition is BB to CCC. We anchor the portfolio in BB and B, that's really our operating slot through points in the cycle. When we get more defensive in advance of an expensive market or maybe the economy is slowing, we rotate up a bit higher in quality to triple B, which is technically investment grade.
But we want to stay fully invested, because income is a priority and cash drag is a problem. And after the bottoming of the economic cycle, when the recession bottoms, we can get more aggressive, and buy the CCCs for the price and quality bounce. So in NBI today, we have 7% in CCC, but we’ve been as low as zero percent leading up to the bottom of the economy. Positioning for rebound, we've held as much as 25% in CCC.
So the low 7% weight in NBI today reflects that we’re going through a slowing in growth in the global economy. Our central thesis is a lower but durable level of growth, which can extend the cycle longer here. The 7% in CCC is a much smaller exposure than in an index bond portfolio.
GH: A portfolio with 450 holdings and 300 issuers must have some losses. What default rate would you expect?
AG: Our goal as an active manager is to understand which companies are likely to deteriorate in future, and we've only had one default in 20 years of investing in high-yield bonds.
GH: Really? I thought the default rates for BB and B corporate bonds was about 2% a year and higher in the GFC, and CCC much higher.
AG: Yes, there have been over 1,000 corporate defaults over that period. But as well as understanding the quality of the businesses, liquidity is vital. We want to transact out of the bonds if we feel our original thesis has changed. If you own a bond today, you have a thesis, you have a view on management, you have a view of the business model and how they will service their debt? If in a year's time, that thesis changes, you can sell into the market.
GH: Okay, you don’t have defaults but you might have sold a deteriorated position.
AG: That's right, that's our second bit of protection as a manager. If something doesn't pan out, we can sell the bond at two or three or five points below where we bought it. So we are realising a bit of a loss but it's more prudent risk management than riding that bond for another 60 point loss to wherever the markets will price its recovery value. We want to avoid that tail risk.
GH: In the GFC, regardless of what you owned in the non-government bond space, spreads widened and prices fell. How did the high-yield portfolio go in those years?
AG: Very interesting. For the two-year period, 2008 and 2009, if you bought this asset class passively as an index investor, you would have returned negative 27% in 2008 and plus 58% in 2009.
(Ed. At this point, Adam showed me the slide below).
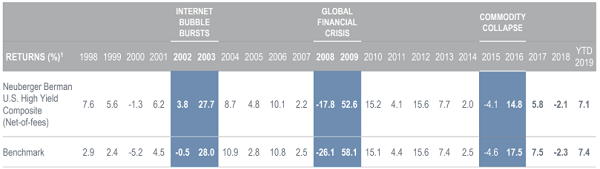
Source: Neuberger Berman as at 31 March 2019, benchmark is BofAML US High Yield Master II Constrained Index.
AG: In our portfolio, the bonds were still marked down, but we invest in more durable businesses and we had no defaults. In 2008, we were marked down 17% versus the index’s 26%. Then at the end of 2008, we started rotating into risk again, we bounced with the market, but not as strong. We were up 52% versus the market up 58%. It was powerful for our clients. We had a better return than the market, but the income throughout that period was not compromised. The coupons were still coming in each morning albeit with a lot of price volatility. And that price volatility was still far superior to shares. Over the last 10 years, global high yield has an annualised volatility of about 7% versus global equities around 12%.
GH: So you need to educate your clients to hang in during tough markets.
AG: And share our view of the underlying businesses and our confidence in them. Bonds are very different from shares. They have legal, mandatory payments through a coupon from a company. The market marks down the bond but it is eventually forced to get its head around whether this company is solvent or not.
GH: The duration of the book is about four years, which means interest rate risk in a very low rate environment. Why are you comfortable with that?
AG: This asset class does well in periods of rising interest rates. If you looked at the first three quarters of last year, the high-yield market outperformed investment grade bonds when interest rates were going up. What's usually driving higher yields is the economy is doing well, and if you translate economic growth into these companies and their businesses, that's improving their revenues, earnings and cash flow. Markets have more confidence that they'll be able to service their bonds, resulting in tighter credit spreads. This fall in spreads absorbs some of the rise in underlying government bond rates and results in a strong price return for high-yield bonds.
If you look at the period from 2000 to 2016 for rising rate environments, the median rise in US Treasury yields was about 90 basis points (0.9%) over a three-month period. And what did high-yield do in that same three-month period? It delivered a positive 2.4% return. And then in the subsequent three months, after interest rates stabilise a bit, you get even stronger returns. The economy's doing well and markets rally. The opposite is true in investment-grade bonds, which have a smaller coupon and longer duration … this is becoming a long-winded answer …
GH: No, it’s an important point.
AG: The other factor is a fat coupon is very powerful. It compensates for some of the default risk we talked about, but it also compensates for the interest rate risk. For example, if the bond has a four-year duration and rates go up 1%, in theory, this will be a 4% loss of capital. But if you’re earning a 5% coupon, it can bring you back fast.
GH: Most closed-end funds listed on the ASX, in the Listed Investment Company space, trade at a discount to their Net Tangible Assets, the NTA. Why will NBI be different?
AG: This product is built for an income objective, which is defined by our target distribution that we broadcast to the market each year. It’s different to a LIC where the underlying assets are shares as we own less-volatile bonds. The objective is more transparent in a way because people are buying into the target distribution for their portfolio. And to the extent we're achieving that target, seen on a high frequency basis, every month, it should create the right community of investors. They should not have a reason to sell it.
The community that owns a share LIC could have vastly different expectations about why they invested in that LIC and what they want from a return or income perspective. And that creates greater volatility in terms of buyers and sellers.
GH: So you want to see it trade at NTA.
AG: Yes, the proposition is straightforward about income. After our IPO, it did trade at about a 3% premium, so the way we can reduce that premium is by issuing new shares. That's what we're doing this new offer, after feedback from existing and potential investors that they would like to build more exposure to NBI at NTA.
GH: How does your portfolio differ from the high-yield index?
AG: Substantially. There are about 1,500 companies issuing bonds in our defined market, and we own about 300. We're not taking undue idiosyncratic or individual name risk but we're not owning the whole market. We can be selective on issuers, on credit quality, on industries, on relative value. Today, the portfolio is more heavily skewed toward defensive industries than cyclical types of businesses. That's a reflection of market valuations.
Graham Hand is Managing Editor of Cuffelinks. Neuberger Berman is a sponsor of Cuffelinks. This article is general information and does not consider the circumstances of any investor.
Neuberger Berman is currently undertaking an Entitlements and Shortfall Offer for the NB Global Corporate Income Trust (ASX:NBI). For further details, see www.nb.com/nbi. Nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security.
For more articles and papers by Neuberger Berman, please click here.