Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 524

Aged care and the Intergenerational Report

The Federal Government's 2023 Intergenerational Report features an ageing population and rising demand for aged care as key themes impacting our economy and society over the next 40 years. These trends reinforce the need for Australians to consider their aged care needs rather than wait for a crisis before becoming aware of their aged care options, how to access care, and the financial decisions that need to be made.

What the report says about aged care

The report singles out the care and support sector as one of the major growth sectors over the next 40 years. It estimates that those aged 85 years or older will triple during this time, and the care sector will need to accommodate the needs of these people.

The Government predicts that ongoing budget deficits will limit its ability to fully fund the increasing cost pressures of aged care. These increasing costs are likely to see people fund a greater portion of their care needs where they have the financial means to do so. Australians need to plan ahead for their aged care needs and consider the costs and financial decisions associated with accessing aged care support. Aged care considerations should be a key part of their retirement planning.

Australia’s population is projected to grow from 26.5 million in 2022–23 to 40.5 million in 2062–63. The number of people aged 65 and over is expected to increase substantially and represent 23% of the population (around 1 in 4 people).

Longer life expectancies should result in Australians spending more years in full health. But on the flip side, we will also have an increased number of years in ill-health, which will accelerate government spending in health and aged care as well as the demand for aged care services and advice.
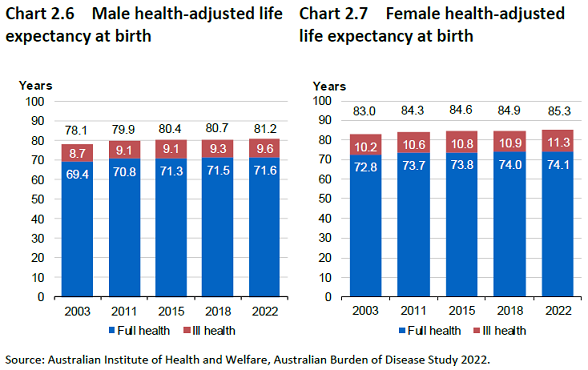
The average number of years that a person lives in ill-health has been steadily increasing in the last decades and this trend is expected to continue.

Funding for aged care

Most Australians who reach old age will need aged care services. The Australian Government provides funding for residential aged care and a range of community care – including home care – services.

The major aged care services subsidised by the Australian Government include:

  • Home support services through the Commonwealth Home Support Programme and Home Care Packages, and
  • Residential aged care services that provide 24-hour care and accommodation for older people who are unable to continue living in their own home.

Currently, people aged 65 or older currently account for around 40 per cent of total Australian health expenditure, despite being about 16 per cent of the population.

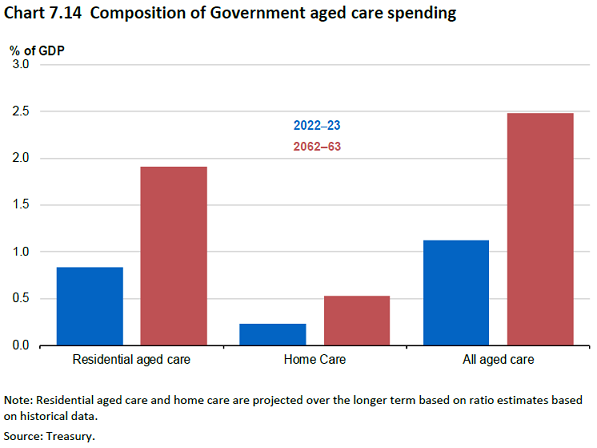
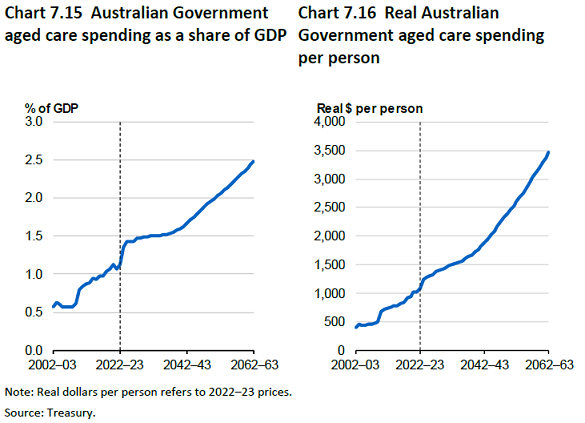
Australian Government spending on aged care is projected to grow from 1.1% of GDP to 2.5% in 2062-63 with the older population accounting for around 70% of the projected increase in real spending on aged care per person.

Spending on residential aged care will increase the most although spending on community care should also rise significantly. Aged care spending per person will also increase.
Australians need to consider the aged care options and strategies for themselves as well as their family members, particularly where they have caring responsibilities for an older family member. People who hold enduring powers of attorney for an older family member and are responsible for making financial and health decisions for them need to ensure that they have the resources and support to make informed decisions.


Assyat David is a Director of Aged Care Steps. This article is based on the author’s understanding of the relevant legislation at the time of writing. This information is of a general nature only. The author has not taken into account the goals, objectives, or personal circumstances of any person.


  •   30 August 2023
  • 2
  •      
  •   
2 Comments
David Williams
September 05, 2023

Very timely comments thanks Assyat. The latest Intergenerational Report approaches increasing personal longevity as an economic challenge rather than an opportunity. Yet healthy life expectancies are still rising, and by achieving longer lifespans the remaining period of personal dependency tends to decrease. The bonus of increasing longevity is clear, but the available personal and community benefits are not being achieved.
Healthier people can remain productive and contributing (whether paid or unpaid) well beyond ‘retirement age’, itself a major barrier to a positive view of longevity. Through better education, personal longevity planning and harmonized incentives, many can continue to benefit personally and contribute to sustaining those who cannot. This can make a significant difference personally and to the overall economic impact.
Longevity education is relatively simple because we all ‘speak’ time, one of the most common nouns used in everyday life. We also make time tradeoffs daily, so the concept is easy to apply to other issues like health and finances. The common language and ubiquitous nature of ‘time’ makes it an ideal basis for trust-building. Longevity education covers ‘the rest of my life’. ‘Retirement’ is then just one aspect of longevity.
Aged care is one key longer term element of longevity planning, which reviews immediate key health issues and then addresses six other key longer-term issues – who will speak for me when I can’t, what will I do, where will I live, who gets what (and who doesn’t), my dependency, and end of life. This process underpins a genuinely holistic response from professional advisers in health, finances and estate planning. Without compliance complications, it can also be promoted by superannuation funds as part of preparing members (and their partners) for their later life.
Proper support for longevity education and planning requires better co-ordination of the dominant government silos (Treasury, Social Services, Health and Aged Care, and Employment). A national longevity strategy would harmonize government incentives for staying healthier and participating in productive activities. This would promote community confidence in making the best of increasing longevity, and in dealing with its opportunities and challenges in the most effective way.

Justin Hockley
September 08, 2023

I agree David.
Look at Medicine 3.0, its all about looking after "ourselves" ,now as the future...our longevity...is growing and we need to look after the shell that we have.

That requires planning and input from ourselves as the "owners" and each of the agencies you have listed.


Leave a Comment:

RELATED ARTICLES

10 things I learned about dementia and care homes from close range

10 ways to fix Australia’s broken retirement income system

Australia needs to transform how it cares for older people

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.