Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 284

Beyond financial solutions for longevity

I appreciated Jeremy Cooper’s recent excellent article on meeting the challenges of longevity risk. Erudite actuaries and investment gurus have long sought investment products which guarantee income for the life of each investor.

While I support efforts to craft better financial products and solutions, we must also make more effort to educate our rapidly-growing older population. There is much they can do to reduce longevity risk themselves. The focus on financial literacy seems to have been most effective at younger ages but not as much beyond midlife. Reallocation of resources into greater longevity awareness is required.

What could be the key elements?

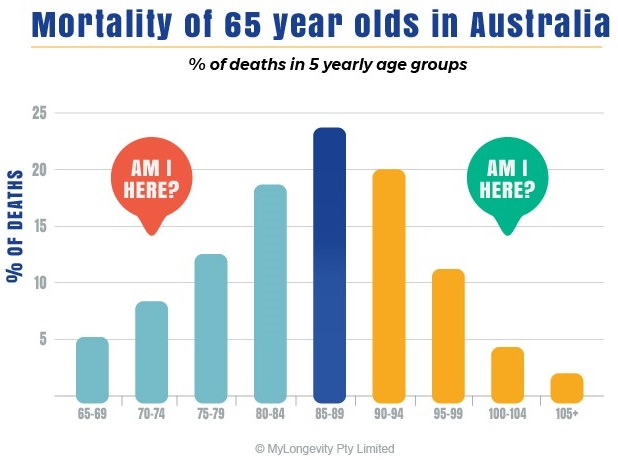
1. Realising that at age 65 (‘retirement age’), over 75% of people are not within three years of the number of years nominated in Life Table expectancies. As shown in the diagram below, there is an enormous range of mortality outcomes, making estimates of how long money will last much less realistic than most people appreciate.

2. Recognising that the rest of their life is likely to play out in three stages: 1) able, 2) less able but still independent, and 3) dependent. Life will be materially different in each stage. For a majority of people at age 65, for example, the able stage is over 10 years, prompting serious consideration of alternatives to stopping paid work too early. This may not be viable as dependency rises.

3. Understanding that the longer they live, the longer they are likely to live, but much of this extra life is likely to be independent. If their prospective lifespan increases, so their dependent phase is likely to reduce.

4. Appreciating that successful ageing is likely to reflect their personal focus on four main issues: 1) exercise, 2) effective social engagement, 3) diet and weight control and 4) appropriate mental challenges.

5. Knowing that indefinite extension of lifespans seems unlikely, but the cost of staying alive will rise to reflect increasingly expensive medical solutions.

6. Accepting that home-based aged care is inevitable for most, and that preparing family and dwellings for this eventuality should be a priority in the able stages of longevity, not when the need becomes evident.

7. Contributing to the debate on assisted dying, recognising the ethical, emotional and financial considerations and expressing a personal view in a way people close to you understand.

8. Factoring in that cognitive issues such as Alzheimer’s disease (now a major factor in the death of older people) appear to reflect earlier life behaviours which many people can address with the hope of deferring the onset.

Averages disguise significant variability

Only 200 years ago, the average baby would not live beyond 40 years old. Babies born today are on average expected to live beyond age 80. Society has made use of this - through better education, communications, infrastructure, laws and governance and greater wealth to invest in living standards. While most people realise this remarkable change is ongoing, few realise what it can mean for them personally.

If we look at a very large group of 65-year-olds in Australia, we know on average how long they will survive. This diagram below shows the percentage of deaths expected in groups of five years. The average survival is 21 years for a 65-year-old. It sits inside the blue column, which represents less than a quarter of the total age group, so the average is not very helpful. At this age, men live about three years less than women.
Success in dealing with longevity risk is more likely to reflect management of the elements outlined above rather than hanging out for financial products which may be a partial solution but will not address the broader opportunities and risks in our longevity for the rest of our lives. People should be empowered to take more control of their personal circumstances, and better education is the key.


David Williams is Founder and CEO of My Longevity. Try the SHAPE Analyser to focus on your own longevity.


  •   12 December 2018
  • 2
  •      
  •   

RELATED ARTICLES

Love them or hate them, it's worth understanding annuities

Are lifetime income streams the answer or just the easy way out?

Will you run out of money in retirement?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.