Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 548

Clock is ticking on a super free kick

The early part of each year is often a good time to review your investing strategy for the calendar year ahead and beyond.

And, with less than six months to go before 30 June, it’s also a good time to consider shorter-term opportunities. Sometimes it can be a case of use them or lose them.

Take this financial year, for example. For some Australians, there’s a concessionally taxed superannuation investment opportunity specifically hinged to the 2018-19 financial year that will expire on 30 June this year. By 1 July it will be gone.

The catch-up opportunity

Working Australians are allowed to contribute a maximum of $27,500 into their super each financial year at a concessionally taxed rate of 15%.

It’s a capped amount that includes the mandated super payments made by your employer plus any additional personal super contributions you choose to make to your super fund. However, in any given financial year, many people are unable to take advantage of the full $27,500 concessionally taxed contributions limit.

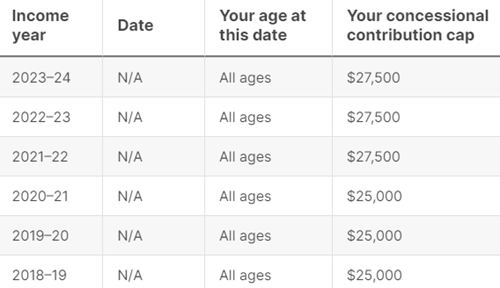
Back in 2016-17 the then federal government announced that from the start of the 2018-19 financial year it would allow eligible Australians to carry forward any unused annual concessional contribution amounts they have for up to five financial years.

Source: ATO

As such, the deadline for taking advantage of any unused concessionally taxed entitlements from the 2018-19 financial year is the end of 2023-24.

In many respects it’s a super free kick that’s there for the taking, at least for those Australians who are legally and financially able to do so.

Eligibility requirements

There are eligibility requirements for being able to take advantage of carry forward contributions from previous financial years.

To be eligible, you must:

  • have a total super balance of less than $500,000 at 30 June of the previous financial year.
  • have unused concessional contributions cap amounts available.

The good news is that if you are eligible, there’s nothing you really need to do. If you have the ability to make extra super contributions this financial year above the concessionally taxed $27,500 annual limit, any carry forward concessional cap amounts from previous financial years will be automatically applied by the Australian Tax Office (ATO).

If you haven’t used them already, the ATO will first apply any amounts from the 2018-19 financial year. It will then progressively apply any unused amounts from subsequent financial years.

A carry forward example

Let’s say you are still under the $500,000 total super balance and have some accumulated savings you’re willing to put into your super fund. Maybe you’ve recently sold an asset and now have some extra cash in the bank.

In the 2018-19 financial year you made $15,000 in concessional super contributions. Because the annual concessional contributions limit back then was $25,000, you would therefore have a $10,000 unused amount from that financial year. The annual concessional contributions limit wasn’t lifted to $27,500 until the start of 2021-22.

In each subsequent financial year you made $20,000 in concessional contributions, so you also have $10,000 from both 2019-20 and 2020-21, and $7,500 from both 2021-22 and 2022-23.

That gives you a grand total of $45,000 in unused concessionally taxed contributions spanning five financial years plus this financial year’s $27,500 limit.

If you were to exceed this financial year’s $27,500 by between $1 and $10,000, the extra contributions would be deducted from your 2018-19 carry forward amount. Any amounts over $10,000 would be deducted from 2019-20, and so on.

How do I find out if I have unused amounts?

You can easily check if you have unused concessional contribution amounts online via your myGov account by linking to the ATO.

After logging in, select Super - Information - Carry forward concessional contributions, and your unused balances by financial year should be viewable.

The caveats are that you must not have made concessional contributions in the financial year that exceeded your general concessional contributions cap and, as noted, your total super balance must be below $500,000 as at 30 June of the previous financial year.

Even though we’re now only around midway through the current financial year, it’s worth considering whether you can use this super free kick before 30 June 2024.

Consider an adviser

Super and retirement planning is a complex area. Take care to understand the contribution types and limits carefully as there are significant tax penalties for exceeding the applicable contributions caps. If you’re unsure about your super options before 30 June and need some advice, consider consulting a licensed financial adviser.


Tony Kaye is a Senior Personal Finance Writer at Vanguard Australia, a sponsor of Firstlinks. This article is for general information purposes only and does not consider the circumstances of any individual.

For more articles and papers from Vanguard Investments Australia, please click here.


  •   21 February 2024
  • 7
  •      
  •   
7 Comments
Alistair Mailer
February 22, 2024

Thanks for the article; Probable error in the 'carry forward' example :
In each of the 2019-2020 & 2020-2021 years there is only $5,000 available as unused carryover amount available ($25,000 limit less $20,000 contribution), not the $10,000 in each of these years as stated in your example. Hence grand total of only $35,000 in unused concessionally taxed contributions, not the $45,000 stated.

Tony Kaye
February 24, 2024

Alistair, apologies for my convoluted example. Here's my arithmetic:
2018-19 - Contribution of $15k left $10k to carry forward under previous cap (will roll off this financial year);
2019-20 - Contribution of $15k left $10k to carry forward under previous cap;
2020-21 - Contribution of $15k left $10k to carry forward under previous cap;
2021-22 - Contribution of $20k left $7,500 to carry forward under the current cap
2022-23 - Contribution of $20k left $7,500 to carry forward under the current cap
Total: $45k

Alistair Mailer
February 29, 2024

Hi Tony,
... But your article specifies a $20,00 contribution in the two years mentioned (2019-20 & 2020-21); quote from the article:
" In each subsequent financial year you made $20,000 in concessional contributions, so you also have $10,000 from both 2019-20 and 2020-21, and $7,500 from both 2021-22 and 2022-23."

Alistair Mailer

Jack McCartney
February 23, 2024

An interesting article. I followed your instructions regarding logging in to the myGov account and couldn’t find any details regarding the c/fwd concessional contributions for prior years per your steps above.
Could you advise how I can derive please.

Tony Kaye
February 24, 2024

Hi Jack, here's a step by step guide to see if you have any unused concessional contributions:
1 Login into the my.gov.au website
2 Click through to the Australian Tax Office (linked to your my.gov.au account)
3 Click Super in the menu
4 Click Information
5 Click Carry-forward concessional contributions
6 Scroll down the page to see any unused concessional contributions cap amounts available by financial year.

Jason mc
February 23, 2024

Who made Super so complex

Lee
February 25, 2024

Thank you, this was a great article Tony. I followed your steps, found I had an unused balance and adjusted my super contributions accordingly. Thanks again. :)


Leave a Comment:

RELATED ARTICLES

2024/25 super thresholds – key changes and implications

When losses in super become irreplaceable

Overcoming the fear of running out of money in retirement

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.