Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 622

Investing at market peaks: The surprising truth

After crashing hard in April, the US stock market rebounded even harder, recently hitting a new all-time high. This has left many investors feeling nervous about the potential for a fall.

Many others have parked savings in cash, attracted by the high rates on offer. The thought of investing that cash-on-the-sidelines when the stock market is at an all-time high feels uncomfortable. But should it?

The conclusion from our analysis of stock market returns since 1926 is unequivocal: no.

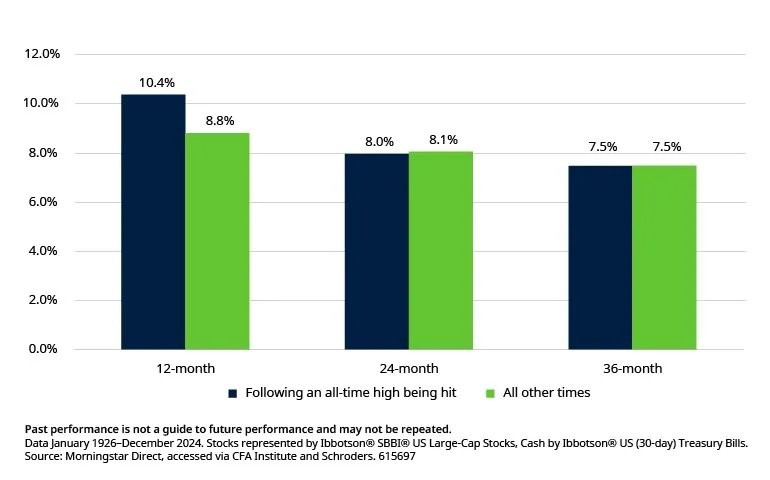
The market is actually at an all-time high more often than you might think. Of the 1,187 months since January 1926, the market was at an all-time high in 363 of them, 31% of the time.

And, on average, 12-month returns following an all-time high being hit have been better than at other times: 10.4% ahead of inflation compared with 8.8% when the market wasn’t at a high. Returns on a two or three-year horizon have been similar regardless of whether the market was at an all-time high or not (see chart below).

Figure 1: Returns have been higher if you invested when the stock market was at an all-time high than when it wasn’t
Average inflation-adjusted returns for US large cap equities, p.a.
Differences compound over time

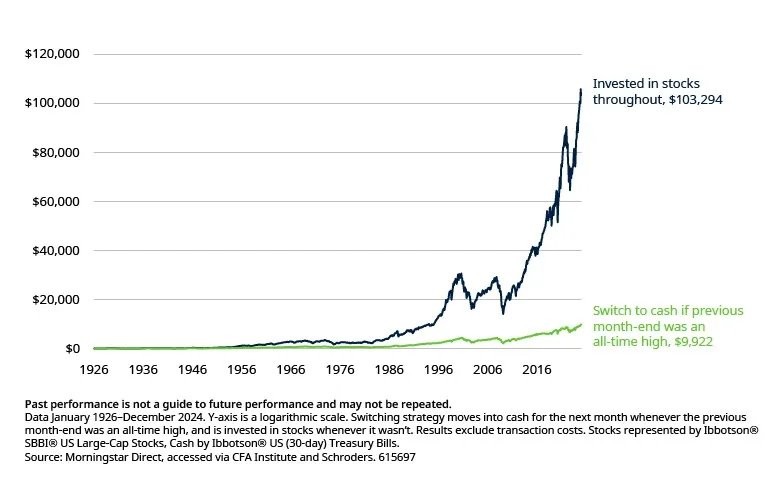
$100 invested in the US stock market in January 1926 would be worth $103,294 at the end of 2024 in inflation-adjusted terms, growth of 7.3% a year. In contrast, a strategy which switched out of the market and into cash for the next month whenever the market hit an all-time high (and went back in again whenever it wasn’t at one) would only be worth $9,922 (Figure 2). This is 90% lower! The return on this portfolio would have been 4.8% in inflation-adjusted terms. Over long time horizons, differences in returns can seriously add up.

Figure 2: Selling stocks whenever the market was at an all-time high would have destroyed 90% of your wealth in the very long-run
Growth of $100, inflation-adjusted terms
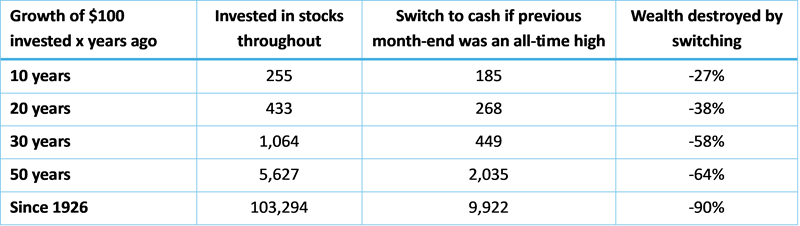
This analysis covers a nearly 100-year time horizon, longer than most people plan for. But, even over shorter horizons, investors would have missed out on a lot of potential wealth if they had taken fright whenever the market was riding high (Figure 3).

Figure 3: Selling stocks whenever the market was at an all-time high would have destroyed 90% of your wealth in the very long-run
Growth of $100, inflation-adjusted terms
Past performance is not a guide to future performance and may not be repeated.
Data January 1926-December 2024. Y-axis is a logarithmic scale. Switching strategy moves into cash for the next month whenever the previous month-end was an all-time high, and is invested in stocks whenever it wasn’t. Results exclude transaction costs. Stocks represented by Ibbotson® SBBI® US Large-Cap Stocks, Cash by Ibbotson® US (30-day) Treasury Bills. Source: Morningstar Direct, accessed via CFA Institute and Schroders.

Conclusion? Don’t fret over all-time highs

It is normal to feel nervous about investing when the stock market is at an all-time high, but history suggests that giving in to that feeling would have been very damaging for your wealth. There may be valid reasons for you to dislike stocks. But the market being at an all-time high should not be one of them.


Duncan Lamont, CFA is Head of Strategic Research at Schroder Investment Management Australia. This material is general information only and does not take into account your objectives, financial situation or needs. Schroders does not give any warranty as to the accuracy, reliability or completeness of information which is contained in this material. Read the full report and important disclaimers here.

For more articles and papers from Schroders, click here.


  •   30 July 2025
  • 11
  •      
  •   
11 Comments
John Derry
July 31, 2025

What about in the context of highest percentile valuations? That usually paints a different picture.

Z Nut
July 31, 2025

Thank you for this insightful analysis.
I’m curious how the findings might apply in a scenario like this:
Suppose someone has been consistently investing a fixed monthly amount into ASX:VTS over the past few years. Now, without selling their existing VTS holdings, they continue investing the same monthly amount into ASX:VEQ instead (based on the view that European equities appear less overvalued than U.S. ones).
Has anyone explored how this kind of regional rotation strategy performs over time?

Steve
August 01, 2025

Very much doubt it. All these scenarios tend to presume a one off investment and what happens subsequently. To my knowledge there are no indexes that cover the return of a fixed amount each month over any time frame. Which is what 90% of people actually do when saving. There are quite a few gaps in most of the indexes.

Go for it
July 31, 2025

Great article.
Put money in when you have the money
Take money out when you need the money.
Feel you don’t know what you’re doing? Use ETF’s. And take the stocking out of it.

Jeremy Campbell
August 01, 2025

Rubbish. The old old lies damn lies and statistics approach. Not so funny how these articles appear at market highs as the bubble blowers seek to pull in the last of the dumb money while cashing out themselves. My view (which is worthless) is that the market will push higher from here, but there will be a major correction down the track which will hurt those who pour money in now without regard to value. When? If I (or anyone) could accurately time that they would be on a beach somewhere enjoying life, not writing pieces,or comments, like this.

Ian Radbone
August 01, 2025

What's your evidence that the article is rubbish?

Richie H
August 02, 2025

I agree, investing fresh money now would be interesting to say the least. How much more upside does this market have? 10-20%.. I understand DCA would change your average purchase price a little and thats fine. But fresh bulk cash, wait for the 30-40% down. There's only a couple of days a year where most of your returns are made and it's not when the market frothing more than a fat kid in a cake shop. And TRUMP, wow, just wow!

Mark
August 04, 2025

I would really be interested if the same applies to the Australian market given that we haven't run so hard after the last few years. Is there some analysis on this?

James Gruber
August 04, 2025

Hi Mark,

I'd love to have the data but don't.

I will pass it on to a few of our quant-focused sponsors and see if they would like to do it.

James

allan
August 04, 2025

What I miss in all this analysis is the retiree who is drawing down from these assets at both highs and lows of the market. This analysis is based on leaving the funds untouched for long periods of time.

Harry
August 05, 2025

Should’ve started investing when you got your first job pumping gas at the local Esso station!


Leave a Comment:

RELATED ARTICLES

Where to hide in the ‘everything bubble’

What do 11 stock market crises over 148 years tell us?

Redefining risk for income investors

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.