Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 506

French fight pension age rise while Aussies work on

There is a fascinating contrast in age pensions in Australia and France. In a few months from now, the eligibility age in Australia rises to 67 years. There is no marching in the streets in protest. In France, there are violent objections against increasing the age from 62 to 64 years. Wild mobs set fire to Bordeaux’s town hall, invaded the stock exchange building in Paris and constructed brick walls across major roads. Tons of garbage are piling up on the streets of Paris as workers campaign against plans to increase their retirement age from 57 to 59, lower than the national average due to the physical effort. Yet in April 2014, the Federal Liberal Treasurer Joe Hockey announced an intention to increase Australia’s eligibility age to 70, although this was scrapped in 2018.

Australia, as high as 70 years (but not for now), France as low as 57 years. What’s going on?

French police fight protesters as roads blocked during pension violence
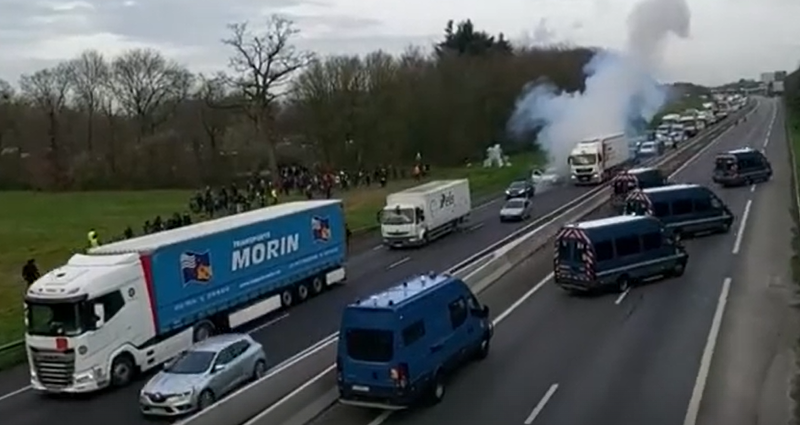
Source: Twitter

Australia at 67 years on 1 July 2023

The age pension was first introduced in Australia in 1909 with an eligibility age of 65, and it was not until 100 years later in 2009 that the Rudd Government introduced a schedule for a gradual increase.
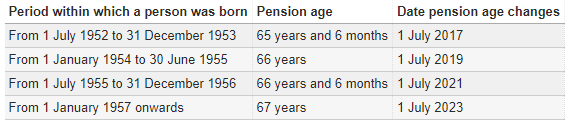
The background to the 1909 introduction was that life expectancy at birth was 55 for males and 59 for females, so few people were expected to receive the age pension for long. According to the Australian Bureau of Statistics (ABS), life expectancy at birth in 2021 was 81 years for males and 85 years for females. So Australians expect to live 26 years longer than in 1909 but the eligibility age has increased by only two years. The majority of Australians will receive a full or part pension, even out to 2060, despite the maturing of the superannuation system.

French are retired the longest

According to the OECD, in 2020, the French had the longest life expectancy at their average age of retirement of any OECD country, with Australia a few years behind.
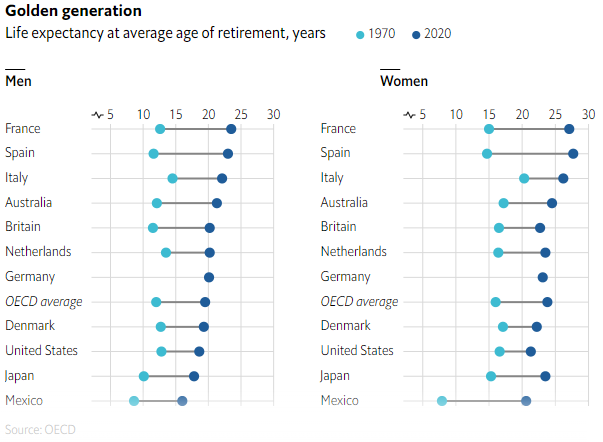
Source: The Economist

What did the Government say in 2009?

Prime Minister Kevin Rudd gave Australians plenty of notice of the coming increases, announcing them eight years before their effective date. He said in 2009:

"With the aging of the Australian population, unless we make these changes for the long-term, then its capacity to undermine the overall financial integrity of budgets in the long term ... is a serious problem. To make this fair is to give people lots and lots of warning. This does not start to be phased in until 2017; it doesn't obtain full effect until the year 2023, and therefore in terms of preparing for it we think it's the right thing to do."

The reaction was mooted, maybe because it was so far ahead. In fact, there were arguments at the time that if the age pension age increases, so should the age for drawing down superannuation pensions. It would be reasonable to expect people already retired not to object, because they benefit the most. Budget improvements due to delayed pensions for other people increase the likelihood that existing pensions can be sustained. Rudd effectively told Australians to 'suck it up', and we did.
Why are Australians passive when government policies change?

Even if we accept that the French have a long history of protest and working fewer hours, Australians rarely take to the streets to force policy change. Perhaps the closest examples were the campaigns against franking credit changes at the 2009 Federal Election, but it was civilised, with no burning of buildings and blocking of roads. There were some lively arguments in local meetings, then it was off for a cup of tea and a biscuit.

In fact, in Australia, violence may be interpreted as negative to the cause.

A recent Tweet asked ‘Anyone know why?” in response to this posting.
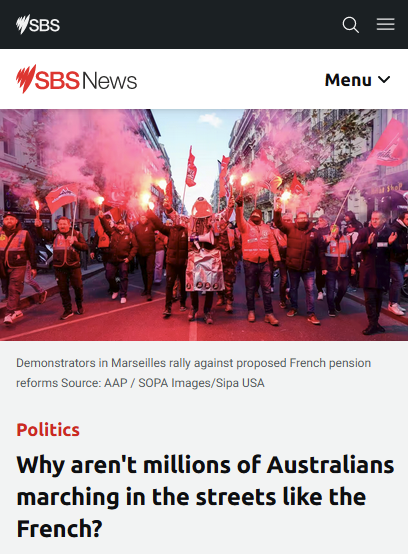
Given the Firstlinks audience is usually heavily engaged on pension issues, we are running a Survey to ask the same question. We will publish a range of replies next week, but please keep the comments civil and non-racist.

Here are a few examples in response to the tweet, but we will not include many others here is their tone is bigoted and discriminatory. We want to engage in meaningful insights into the Australia response to government policies, such as on the pension eligibility age. The Twitter responses include:

"I think this question is fascinating! Look at how each country took to masking and lockdowns, and injection uptakes, which citizens trust their government and media, I think has a lot to do with it! It’s like a huge sociological experiment we are witnessing in real time!"

“We are too busy having fun, don't listen to real news, arrogant but don't understand what is happening or its consequences.”

“It must be about more than the retirement age being 64! Australian baby boomers are working into their 70’s to support their children and grandchildren doing it tough and getting tougher!”

“We have been programmed to believe that we are the lucky country - she'll be right mate - so we never get upset, we just blindly accept whatever is dished out.”

“Are we supposed to be protesting our government not bankrupting the economy with retirement at 62?”

“Because the French still maintain a bond amongst proletariat. A bond of unity that the government have been unable to destroy. Unlike the U.K. and Australia."

"French value their work life balance. In France the mealtimes are very long, it includes groups of people and a lot of conversations. There is no rush to pay the cheque and go. On weekends cafes open towards lunch and fill with people having long lunches with fam & friends.”

Fill in this survey and tell us what you think.
 

Graham Hand is Editor-at-Large for Firstlinks.


  •   26 April 2023
  • 13
  •      
  •   
13 Comments
Survey response
April 27, 2023

Because (sadly) overall Australians are too busy enjoying themselves to worry about tomorrow/next week/next year. You only have to looks at clubs and pubs to see the grand Australian motto "She'll be right, Mate!" in full swing in this country.

Survey reponse
April 27, 2023

The French are entitled and they don’t understand that their government can’t afford to keep pension ages stagnant they need to increase as we live longer and we can’t have younger workers burdened by paying more taxes for retired people. Aussies understand this because we understand superannuation many young people I talk to know that their will be no age pension when they go to retire.

Survey response
April 27, 2023

work ethics, french value life wk balance more than australians do, french are more reliant on pension, our super system is better , can retire earlier

Survey response
April 27, 2023

It is bizarre to me that the French don't accept an increase in age eligibility as life expectancy increases.

Survey reponse
April 27, 2023

I think that we do not often think about the impact of a change until it actually starts and we see the impact. There are some of the population who look at the future impact of a policy, such as the discussion in Firstlinks on the recent superannuation changes, but this is probably an engaged minority of the population.

Survey reponse
April 27, 2023

Our political system of compulsory voting and proportional representation ensures politicians remain sensitive to the views of the electorate. of voters

Andrew Smith
April 28, 2023

Spoke recently to a former financial/wealth consultant (British) about France and the action we see opposing pension reform.

Mainstream media have not explained the why and how of the changes while focusing on the now, especially the demographic change i.e. ageing and also decline in working age.

Australia has been better at marketing super and pension age increases over generations, simply by explaining why and how ahead of time.

Meanwhile one is not aware if French working age (esp. younger end) understand that retaining present pension age means they may have to pay higher taxes for older generations who have worked fewer years.

Survey comment
April 28, 2023

Australians are mostly happy to keep working. Having worked for a company that had offices in Paris I recall the French complaining about pay relativities when they worked far fewer hours and had far more holidays

Ian Lange
April 28, 2023

French culture places a premium on leisure and family time. Australian’s have, in recent decades, adopted a more American capitalist approach to life. Neither country is right or wrong, just different. Go live in France for a few years, you may find yourself enjoying cafe life a little more.

S2H
April 29, 2023

France has got many wonderful things: fantastic food and wine, beautiful cities, a rich cultural history. But I don't envy their propensity to take to the pickets over literally anything (ie. also see the Yellow Vest movement). At some point in a liberal democracy you've just got to accept that you won't always get your way and to get on with it. I think Australians would absolutely hit the streets if we had a situation that called for it (ie. what's happening in Israel).

Survey response (one of hundreds)
April 29, 2023

It is no coincidence the three top countries in your chart are latin cultures. Having lived in Spain for many years, it took me some time to learn that you work to live, not live to work. Our Australian culture of long work weeks is not healthy and possibly explains why many European countries (including the so-called 'more industrious' northern ones) with shorter work weeks often top the 'happiness' index. Before I retired as a financial planner I often met wealthy clients whose main concern in retirement was how not to pay tax rather than how to enjoy their money.

Survey response
April 30, 2023

Australians are a people who will do what they are told. Despite the fact we think we are free, we will doff the cap and tug on the forelock when push comes to shove. Whereas the French have a history of revolution, similar to the United States.

Mark
April 30, 2023

Knee jerk policy creation here that affects the many because of the actions of the few, or even 1 in some cases. It's getting to the point where freedoms are being impacted..


Leave a Comment:

RELATED ARTICLES

Should access to super and pensions depend on life expectancy?

Longevity awareness and the three pillars

Status, longevity and the age pension

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.