Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 111

Longevity awareness and the three pillars

The latest Intergenerational Report (IGR) postulates the three pillars of the Australian retirement income system as the age pension, compulsory superannuation and voluntary saving. All three are looking increasingly shaky for the task ahead, as policy struggles to cope with changes, especially in life expectancy. The failure to increase the eligible age for the age pension has been one of many flaws in retirement income policy, caused by changes that accelerated in the 1970s.

Life expectancy at time of pension eligibility

The IGR graphs life expectancy against pension age eligibility (page 70). Unfortunately it uses the life expectancy of a baby. A better insight comes from using the life expectancy at the age of eligibility for the age pension, which for males has stood at 65 for more than 100 years. It is belatedly being increased from 2017 so that by 2035 it will have reached 70 for both genders.
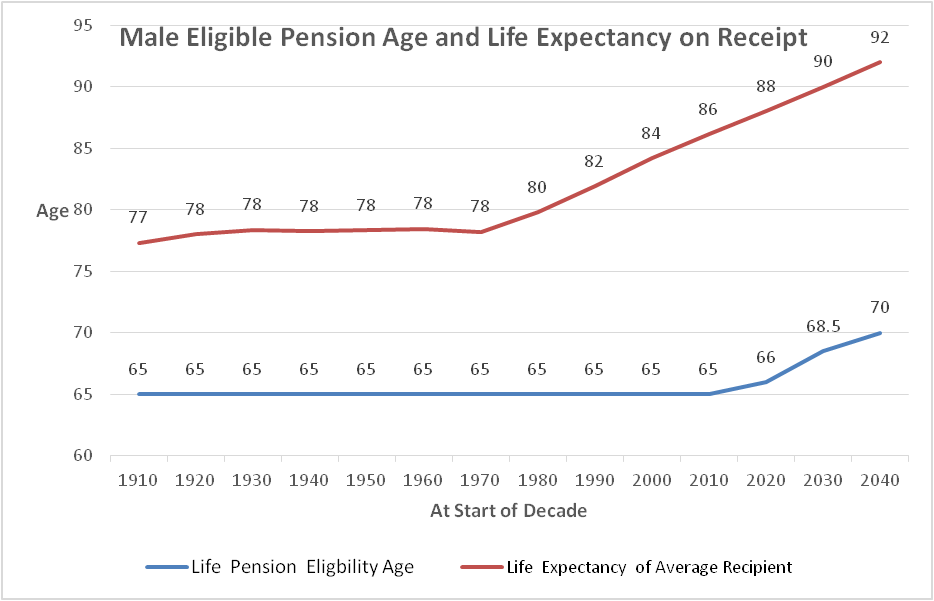
The increase in eligibility is too little too late. From the inception of the age pension, male life expectancy at age 65 rose only slowly until the 1970s (ABS numbers rounded to the nearest year). From then it increased by roughly two years per decade until today and this is expected to continue, as shown.

The last two federal governments have initiated increases in the eligible pension age which top out at 70 in 2035. The chart shows that the gap between eligibility age and average life expectancy for males is likely to have increased from 12 years in the 1970s to 22 years by the decade starting 2040. For female life expectancy, add about four years at age 65, resulting in an even greater gap.

On the face of it, the chart shows just how badly successive governments have failed to respond to the ongoing increase in longevity. The shift towards an older population has further compounded the problem of funding the age pension.

Lower returns and compromised expectations

In earlier Cuffelinks articles (such as this), David Bell neatly defined the many issues in attempting to reform an age pension system that has for so long failed to adapt to the reality of ongoing longevity increases.

Failure to adapt the superannuation system to increasing longevity is likewise building in a gap between expectation and reality. Lower economic growth and low interest rates (in real terms, negative returns in many countries) feed through to entrenched lower returns, leading to a widening gap between perceived need and funds availability. Policy should determine whether the age of access needs to be increased as well as contribution levels.

Financial adequacy is only part of the problem. Financial literacy programs are improving as well as financial awareness at the individual level. People should increasingly be able to conduct an effective financial conversation and contribute to decisions about their savings.

Longevity awareness crucial for retirement planning

The foundations of retirement planning need to be deeper. Few people are aware of their personal time frame that the three pillars need to support. Failure to increase the age of access to the age pension and superannuation has fostered an expectation that it is reasonable to expect access at much younger age than is realistic, other than for those in genuine need. This also has an impact on willingness to add to voluntary savings, the important third pillar.

There is an urgent need to improve longevity awareness across the community, especially at times of tight budget funding.

Since people become more different as they age, using averages such as from the Life Tables is unhelpful. Averages are misleading for individuals and actions that people can undertake need to be personally framed, not generic.

Once people start to recognise what influences their personal longevity, they can take personal ownership of the financial consequences. As a first step, they can begin to address any unrealistic expectations of maintaining living standards with increasing age in the absence of better personal planning such as increasing savings and working longer.

Longevity awareness can underpin weaknesses in the increasingly shaky three pillars. Collective action to boost longevity awareness by governments needs to be complemented by individuals who are well enough informed to commit to making the best of their opportunities to secure their future.


David Williams began longevity research in 1986 and was a Director with RetireInvest and CEO of Bridges. He chaired the Standards Australia Committee on Personal Financial Planning. David founded My Longevity Pty Limited in 2008.


  •   28 May 2015
  • 1
  •      
  •   

RELATED ARTICLES

Should access to super and pensions depend on life expectancy?

SMSF trustees have longer lives and more certainty

Will you run out of money in retirement?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.