For the past few decades, being in shape was the ultimate ‘proof of work’. You couldn’t buy it. You had to earn it. Unless you had top 5% genetics, you had to build your physique through diet and exercise.
But then something incredible happened. GLP-1 agonists (like Ozempic) hit the market and, overnight, a better body was only a weekly injection away. As a result, the old signal (being fit) became less valuable as it could now be acquired without the physical exertion.
The same thing is happening with writing. Writing used to be a craft where someone toiled for hours thinking through a set of ideas before putting them out into the world. Today, that’s no longer necessary. You can have an LLM generate seemingly infinite text at will.
This explains why I saw more books published in 2025 than I can remember in recent years, especially by people who don’t write regularly. Funny, huh?
Of course, if you rely too heavily on AI, your ‘writing’ won’t be all that good. Either way, the written word is far less useful as a signal of thought or effort than it used to be.
I call this signal collapse and it’s happening again and again across different domains. For example, writing code used to be a reliable signal of skill and dedication. But with OpenAI’s Codex and Anthropic’s ClaudeCode, today that seems less true.
AI doomer articles over the past few weeks haven’t helped the situation either. On February 9, Matt Schumer released Something Big is Happening, and on February 22, Citrini released The 2028 Global Intelligence Crisis, which both went viral.
There’s a lot I don’t agree with in both articles, yet both seem directionally accurate. We are moving toward a future more reliant on LLM-intelligence, not less. And in that future, many signals that used to demonstrate value will be easier to fake.
So, how do we display value going forward? What’s the new proof of work?
The new proof of work
In a world increasingly dominated by low-effort, here are a few ways to signal the opposite:
- Leverage your history: If you had a particular skill before it became commoditized, demonstrate that. Lean into it. By showing people that you did something before it was easy, it proves that you are willing to put in the work to master something. More importantly, it showcases that you have an actual interest in the field. If I had to pick between hiring a programmer who’s been doing it for 20 years or one who started with AI a few years ago, I’d take the veteran every time. Though knowledge is becoming commoditized via LLMs, experience, taste, and judgement are still at a premium. This explains why top lawyer fees have skyrocketed even as AI usage explodes.
- Unfortunately, leveraging your history won’t be helpful for those just starting out, but it showcases how you can go about building your career.
- Do deep work: Focus is a superpower and, increasingly, a signal. In an age of distraction, those who can spend weeks, months, or years on a single project will separate themselves from the pack. Cal Newport calls this idea Deep Work. You can demonstrate deep work by completing things that require sustained attention—like complex projects, novel content, or differentiated research. Most people can’t work for an hour straight without checking their phone or logging into social media. But, if you can, then you’ll have a huge edge over others in everything you do. In a world where our attention is being pulled in 100 different directions, the ability to focus on one at a time is an unfair advantage.
- Command attention: Speaking of attention, if you want to stand out, command the attention of others. Because our world is so easily distracted, having people’s attention is proof that you have created something valuable. That attention doesn’t have to come from social media either. Having the attention of a local community or a niche group can be just as powerful as having it within a popular online space. You don’t need to be a content creator, but if you can keep attention and build a community, you will undoubtedly be rewarded for it. I believe this will be especially true for in-person communities in 2026 and beyond.
- Embrace the machine: If you can’t beat ’em, join ’em. Instead of looking at AI as a foe to be avoided, treat it as a partner to help you level up. As I’m sure you’ve heard before, “AI isn’t going to take your job—someone using AI is going to take your job.” There’s no better way to counteract this than to become the person who knows how to use AI. I’m not saying you need to become an AI expert, but you should know enough to expand your capabilities and keep up with the latest tools. Not only will this demonstrate that you take this seriously, but it also highlights that you can be adaptable.
Don’t just take it from me though. In Deep Work, Cal Newport highlighted the people that he thought would have an advantage in an increasingly digital economy (and this was from 2016!):
“In this new economy, three groups will have a particular advantage: those who can work well and creatively with intelligent machines, those who are the best at what they do, and those with access to capital.”
Newport’s categories map well onto the ones above:
- Those who work well with intelligent machines = Embrace the Machine
- Those who are the best at what they do = Leverage Your History + Do Deep Work
- Those with access to capital = Command Attention
I swapped capital with attention because, in many ways, attention is the new capital.
Whatever you decide to do, there’s a structural shift happening in the economy that’s going to take some time to play out. Some believe that this transformation will make labor obsolete. I’m skeptical, but some of the signs are there.
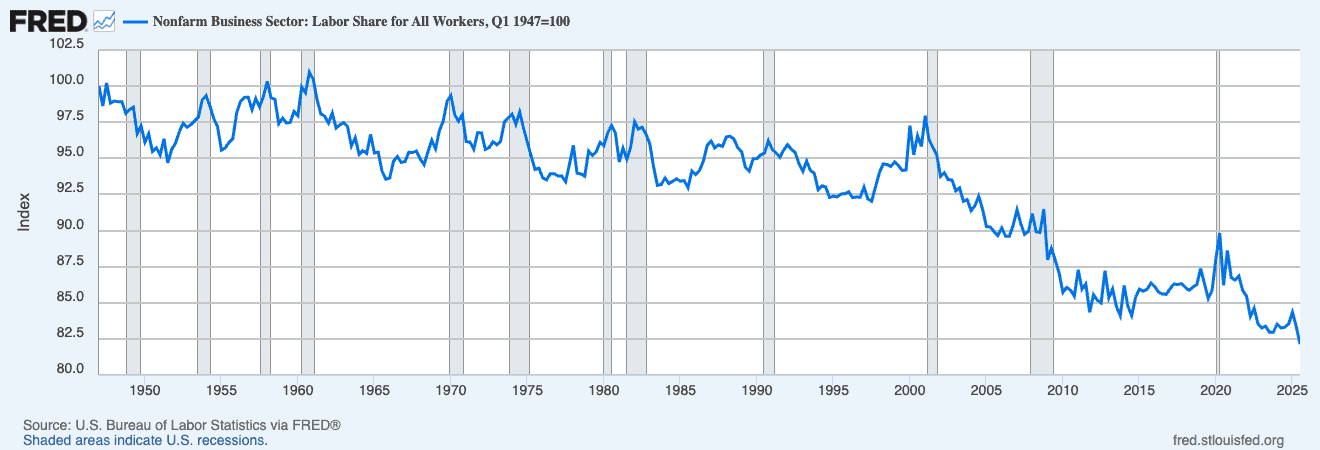
For example, the labor share of the non-farm business sector in the U.S. has declined about 15% since the turn of the century. As you can see in the chart below, labor’s share (of the non-farm business sector) was basically flat from 1947 to 2001. But it’s been on a gradual decline ever since:
We are also seeing economic trends that rarely occur. Kelly Evans recently wrote about how there’s a jobless boom - where the economy surges even as the labor market remains weak. This isn’t normal. Historically, growth and hiring typically moved together. But today, that doesn’t seem to be the case.
For the past few weeks I’ve written a bit more about AI than you might expect from a personal finance/investing blogger. But there’s a reason for it. Though I’d love to ‘stay on message’ and write more posts validating Just Keep Buying, this would be doing you a disservice.
Because, the truth is, your finances will be impacted more by your career than what the market does.
Of course, the market matters, but your income matters more. How AI transforms your industry matters more. How you rise above signal collapse matters more.
If I want to continue to be helpful, I must periodically address these issues. Though the signals of the future will continue to evolve, if we continue to evolve with them, we’ll do just fine.
Nick Maggiulli is the creator of personal finance blog Of Dollars And Data and the Chief Operating Officer at Ritholtz Wealth Management. For disclosure information please see here. If you liked this article, consider signing up for Nick’s newsletter.