Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 110

SMSF trustees have longer lives and more certainty

One of the greatest risks facing retirees today is the uncertainty over how long they might live. How do you plan your retirement when you don’t know how long you need your savings to last? Whilst an individual’s lifespan can never be known with complete certainty, the more information retirees have on how long they are likely to live, the easier it will be to make sustainable retirement plans.

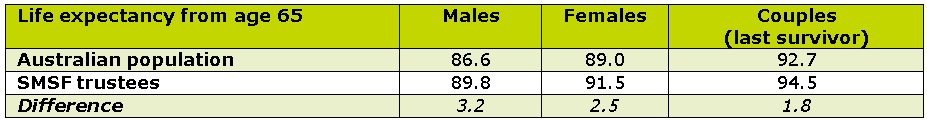
The most commonly quoted life expectancy figures are from the Australian Life Tables and are based on the whole population. If we allow for recent trends in improving mortality to continue, these tables show that 65 year-old Australian men have a life expectancy of 87 and women, a life expectancy of 89. However, different cohorts of the population will live longer than others.

Wealth and education lead to longer lives

Research from around the world has shown that wealth and higher levels of education are strongly correlated with longer life expectancy. SMSF trustees are, on average, both wealthier and better educated than the average Australian so they are one such cohort that might be expected to live longer than the average.

In the first research of its kind in Australia, Accurium’s SMSF Retirement Insights paper, SMSF Trustees - healthier, wealthier and living longer, carried out a mortality investigation on the 65,000 SMSFs in its database to test this hypothesis and calculate how much longer SMSF trustees might live. The results showed that SMSF trustees can expect to live around three years longer in retirement than average.

The table below shows the life expectancies of SMSF trustees in retirement compared to the population as a whole:
Half will live even longer

While life expectancies are helpful for retirement planning, few people will live to their exact life expectancy. Even amongst SMSF trustees, only one in six will live to within a year either side of the life expectancies shown above. Life expectancy is just an average. In fact over half of SMSF trustees will live beyond this.

Many retirees want greater certainty that their savings will last for life so it can be useful to look at the probabilities of living to older ages. Accurium’s research predicts the proportion of trustees who will survive to each age in retirement. These figures can be used as confidence levels for retirees when setting their retirement planning horizons. The table below shows the age trustees retiring at age 65 should plan for with differing levels of confidence:
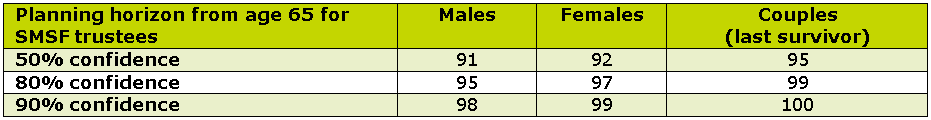
For example, one in five 65 year-old women with an SMSF is expected to live to age 97, therefore those wanting 80% confidence in their retirement plans should be planning for their savings to last around 32 years. A couple wanting 90% certainty should be planning for living for a further 35 years to age 100.

The price of long lifespans is a high cost of retirement and requires trade-offs between how much an SMSF couple spend each year in retirement and how much risk they are willing to accept around outliving their capital.

‘Typical’ couples may need $1.3 million to $2.5 million

Accurium estimates that a 65 year-old couple wanting to spend $70,000 each year and willing to accept an 80% probability of a successful outcome would need $1.3 million as an SMSF starting balance; those wanting to spend $100,000 a year would need a starting balance at 65 of $2.1 million. To achieve 95% certainty that they won’t outlive their capital, that same couple would need $2.5 million if they wished to spend $100,000 per year.

Exactly how long an individual is expected to live has been found to be affected by a number of different factors as well as age and gender. Factors that are known to influence individual life expectancy include smoking, genetics (e.g. family history of certain diseases), current health problems (such as diabetes), occupation and geographic location. SMSF trustees retiring in good health are likely to fall into the higher percentiles for life expectancy and should be planning accordingly.

An important conclusion is that, while fewer SMSF trustees will pass away in the early years of their retirement compared with the population as a whole, a greater proportion will live to their mid-nineties. SMSF trustees can have greater certainty over how long they will live.

Longevity risk for a retiree isn’t the risk that they will live a long time; it is the risk that they will live longer than they have planned for. As long as trustees set their retirement plans using appropriate time horizons, this research shows that SMSF trustees really can have their cake and eat it. Not only will they live longer than the average Australian, but they actually have less longevity risk too.


Doug McBirnie is a Consulting Actuary at Accurium. This information is factual and is not intended to be financial product advice or legal advice and should not be relied upon as such. You should seek appropriate professional advice before making any financial decisions.


  •   22 May 2015
  • 2
  •      
  •   
2 Comments
SMSF Trustee
May 24, 2015

I'm so relieved to realise that my decision to start an SMSF and become a trustee a couple of years ago has added to my life expectancy.

I think, actually, that this study suffers from one of the fallacies I learnt about in high school commerce: arguing that because B follows A, then B must have been caused by A. It's just as likely that both A and B were caused by X, Y and Z.

Perhaps it's got nothing to do with being an SMSF trustee and is really just saying that wealthy, well educated people live longer than poor people with less education. The fact that this cohort also happens to tend to start SMSF's rather than just relying on an off the shelf product is most likely to be coincidental with their extra life expectancy.

But I'm open to being shown otherwise. If I'm wrong, then every GP in the country should immediately prescribe 'open an SMSF' to all their patients.

Alun Stevens
May 25, 2015

I don't believe that the paper suffers from the fallacy of misinterpreting correlation for causality. It is simply comparing outcomes for SMSF trustees with those of the general public.

The causality is undoubtedly the beneficial outcomes from the socio-economic standing of the average SMSF trustee when compared to the total population. The results are entirely consistent with many studies over many years that have considered the mortality experience of different socio-economic cohorts. Even with those studies, however, it is worth remembering that it is not the money that causes the better outcomes - although it helps.

The GPs, however, might have been misled by the statistical inference. They pretty much all have SMSFs.


Leave a Comment:

RELATED ARTICLES

Will you run out of money in retirement?

Longevity awareness and the three pillars

How not to run out of money in retirement

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.