Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 642

What if Trump is right?

On two big trends, President Donald Trump may well be right:

  1. Nations must rebalance from aspirational wants towards foundational needs.
  2. Nations can no longer depend on global support, so they must rebuild self-reliance. Trump’s own policies have accelerated these trends and made them more visible, but the seeds of both shifts predate his presidency by years.

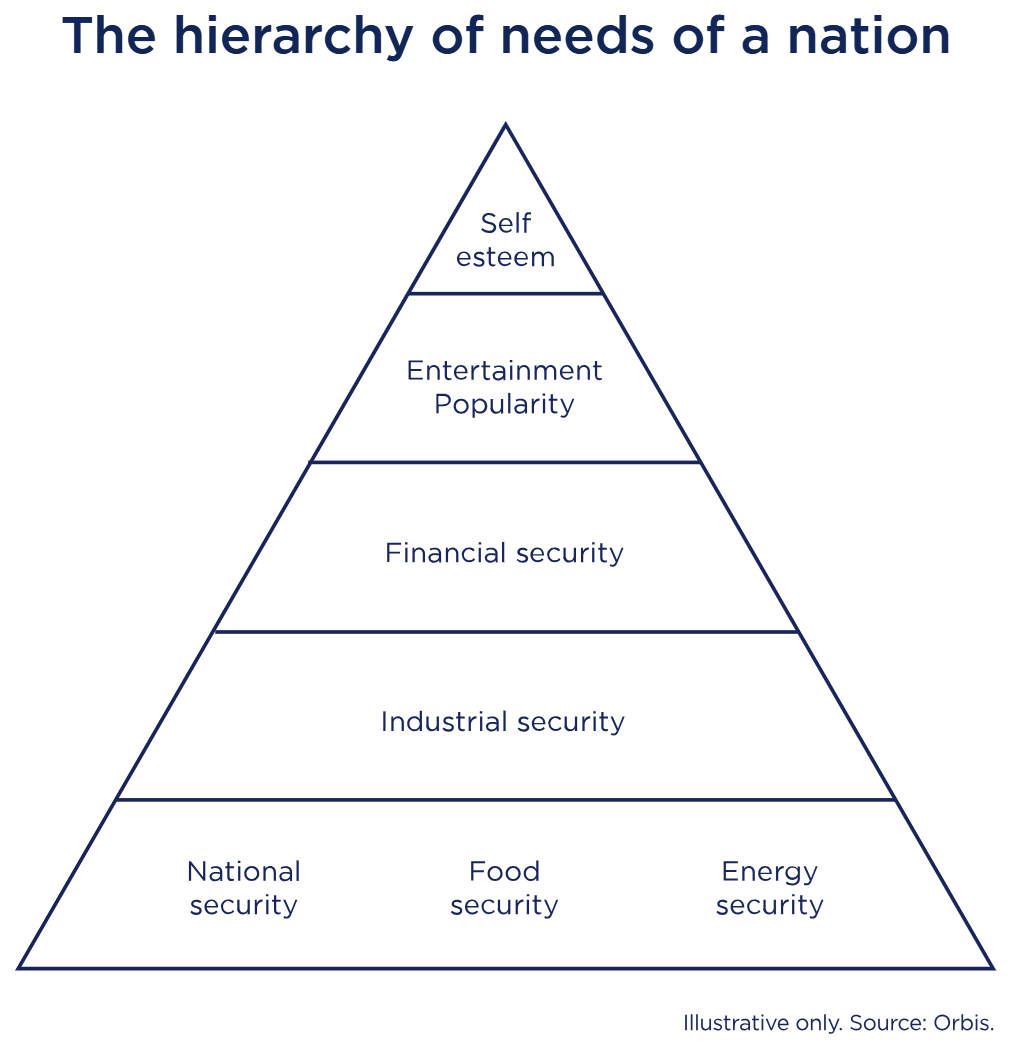
The pyramid of needs

To understand these changes, we borrow a concept from psychology. Many will be familiar with Maslow’s hierarchy of needs: the idea that humans must secure basic needs like food and shelter before pursuing aspirational wants such as entertainment and self-esteem. We believe the same framework applies to nations. Without military, energy, and industrial security, societies have little hope of pursuing a happier future.
How we got here

In recent decades, this pyramid has been upended, initially by a very benign force: abundance.

After the fall of the Berlin Wall, the West reaped the “Peace Dividend” on defense spending. A decade later, China joined the World Trade Organisation, accelerating globalisation and letting consumers get goods cheaply from anywhere in the world. A decade after that, the shale revolution in the US brought down energy prices globally. Throughout this period, rich nations welcomed millions of economic migrants. With an abundant supply of goods, energy, and workers—and less fretting about defense—society felt its basic needs were met. Inflation was low, allowing interest rates to decline. Money became abundant.

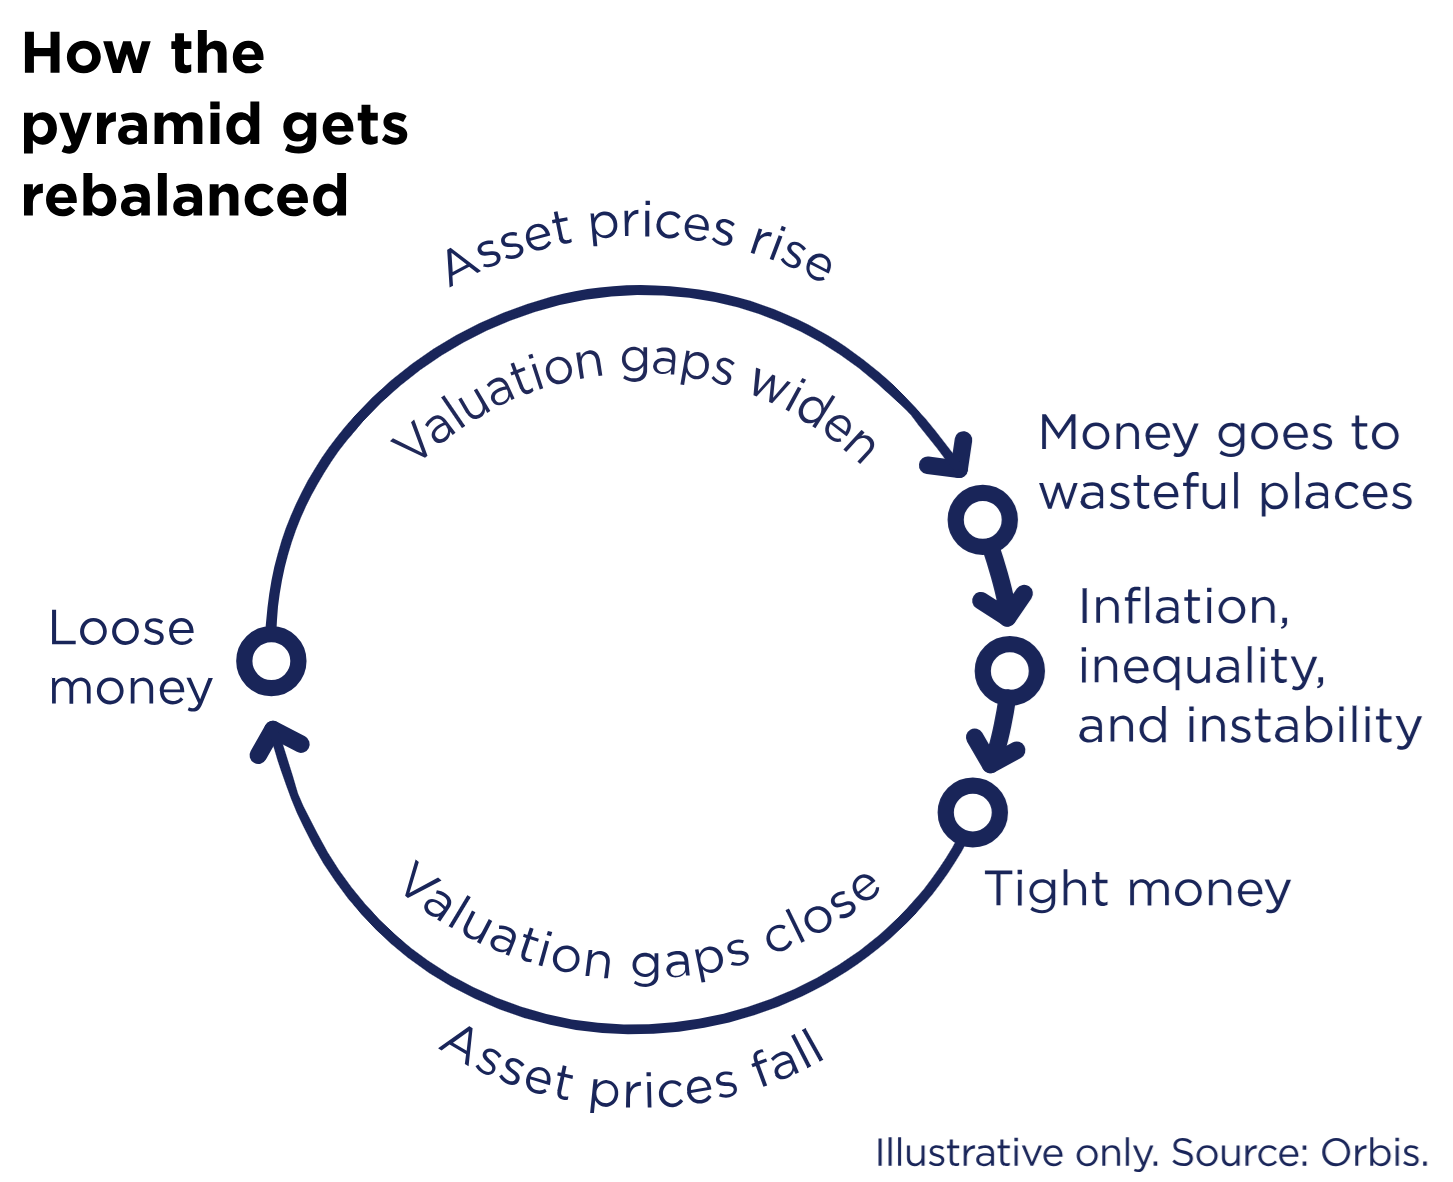
This sets off a cycle. When money is loose and society feels its basic needs are met, people start spending on luxuries and fun. Investors notice that and start throwing money at whoever has the grandest dreams for the future. Rising valuations signal to companies at the top of the pyramid to invest more, drawing in yet more resources.

This cycle plays out at the broad level of markets and the narrow level of companies. Mark Zuckerberg burns $46 billion building the metaverse—a digital playground that no one else wanted to play in. Bernard Looney announces that BP, an oil and gas company, will cut production of its key products by 40%. Office sub-lessor Adam Neumann gets rich promising to elevate the world’s consciousness (and crashing WeWork). In times of abundance, money goes to wasteful places.
The dangers of imbalance: inflation, inequality, and instability

With resources rushing to the top of the pyramid, the base gets starved of capital. The result is shortages of things society actually needs. Those shortages cause inflation for normal people. Meanwhile, the Neumanns, Zuckerbergs, and Musks of the world are getting rich, increasing inequality. Put inflation and inequality together, and you get instability—society’s alarm bell that something needs to change. Conditions were ripe for Trump’s wrecking ball before he ever descended that escalator.

Rebalancing the pyramid: AI case study

Each step in the cycle sows the seeds of the next. Higher inflation attracts higher interest rates, and with money tighter, people think more carefully about where to invest it. But the cycle does not depend on central banks or governments. If the pyramid can get unbalanced organically, it can get rebalanced the same way. Here, AI is a great example.

OpenAI chief Sam Altman has described AI as a bigger deal than the industrial revolution. It may be, and some of its applications are in crucial areas seen by companies or governments as existential needs. But his latest idea, Sora 2, is essentially a TikTok clone where all the videos are AI slop—prime top-of-pyramid stuff.

If you want AI, you need a whole bunch of things from the base of the pyramid. For a start, you need chips. Taiwan Semiconductor Manufacturing Company makes all of the world’s leading-edge AI chips, whether they are designed by Nvidia, Broadcom, or AMD, yet it trades at a discount to those companies. Although AI is more memory-hungry than conventional computing, the memory makers Samsung Electronics, SK Square, and Micron Technology also trade at discounts.

Chips are of little use without related infrastructure, much of which might be built by Balfour Beatty, a construction firm with a roster of anonymous data-centre clients on its website. Those buildings sit on top of foundations laid by Keller, the world’s leader in geoengineering.

Data centres can’t connect to electricity grids without transformers from Siemens Energy and its competitors, who are less able to increase capacity because Silicon Valley has hoovered up the most talented engineers. Grid power has to come from somewhere and has to be reliable. That bodes well for gas producer Shell and gas transporters Kinder Morgan and Enbridge. And amid all this, nuclear power is having a renaissance. As nuclear reactor providers to navies, BWXT and Rolls Royce are highly competitive for small reactor projects.

The rebalancing is happening already. Corporate customers are sending money towards the base of the pyramid, but in many cases, capital is still too scarce. For us, that’s appealing, as it suggests a higher return on that capital. For the businesses, it leads them to respond not by increasing supply but by increasing prices. That inflation, in turn, promises to keep the cycle moving.

It took decades for the pyramid of needs to get this unbalanced. Trump may have accelerated the reckoning, but the great rebalancing is just getting started.


Alec Cutler is a Director of Orbis Investment Management, a sponsor of Firstlinks. Based in Bermuda, he leads the multi-asset team and has overall responsibility for the Orbis Global Balanced and Global Cautious Strategies.


  •   17 December 2025
  • 9
  •      
  •   
9 Comments
michael
December 20, 2025

Trump is increasing inequality, inflation & instability. His wrecking ball is not doing the things you say.

11
Dudley
December 18, 2025


"debt is no more than the US debt":
'Only good thing about debt is that the lender is paid interest.' Quote Dudley The Debtless.

"China bad US good":

China sign WTO. Ignore rules. Subsidise production. Steal jobs. Build debt. Antagonise customer. Fall in screaming heap.

USA company want cheap production. Don't care Yankee job. Sell big profit to consumer. Consumer borrow big. Antagonise producer. Fall in screaming heap.

Match made heaven.

5
Dudley
December 21, 2025


'China’s Leaders Panic as Economic Crash ‘Threatens Entire System’ | EU-China | Currency Manipulation'
https://www.youtube.com/watch?v=BTlu9J8ViYg

Dudley
December 18, 2025


China has benefited from access to global markets and has massively subsidised exports while rapidly building Himalayan scale debt pile and ignoring WTO rules. Nations not subsidising exports lose their industries. Choice is either compete with state subsidies or impose tariffs.

https://www.google.com/search?&q=WTO+state+subsidies
'The WTO regulates state subsidies through the Agreement on Subsidies and Countervailing Measures (SCM Agreement), defining them as government financial contributions that confer benefits, categorising them as prohibited (e.g., export subsidies) or actionable (can be challenged if they cause harm). Members must notify subsidies, and other members can use WTO dispute settlement or impose countervailing duties (extra tariffs) if harmed, aiming to ensure fair trade by preventing subsidies from distorting markets or harming domestic industries, with specific rules for developing nations.'

3
Steven Jackson
December 18, 2025

Please elaborate on the Himalayan debt pile please Dudley, they are a fiat economy and have an imbalance In produced goods and huge inflows of currency. Their gold reserves have grown but obviously total not declared. Most commentators suggest that China is amassing a world linked logistic chain and mineral portfolio and it is being funded with USD and Renminbi loans to countries. Fortescue borrowed 4bilion dollars equivalent for solar investment.
I obviously am missing something in this equation that you could portray in your logical way.

Dudley
December 18, 2025


https://www.google.com/search?&q=china+debt
'China's debt is a significant concern, driven by massive local government borrowing (often off-balance sheet via LGFVs), corporate debt, and household loans, totaling over 300% of GDP when combined, putting strain on the economy despite central government efforts to manage it through bond swaps and tighter rules, with continued challenges in property markets and fiscal stability.'

China's internal demand has 'collapsed' / reduced resulting in static imports and increased exports, resulting in increased trade surplus, the increased exports resulting in reduced profit.

"huge inflows of currency":
with capital controls fighting 'capital flight'.

3
David O'Neill
December 19, 2025

Can I give you a list of Trump quotes to put beside the ones you've elected to write about?

3
Steven Jackson
December 18, 2025

AI offers No debt crisis but growth is structurally slower
Why collapsed narratives are exaggerated,
No foreign currency debt crisis
No sudden capital flight
Strong balance sheet
Ability to socialise losses
This it seems is just another inevitable story of China is failing by the Wall st journal or the Economist etc and geopolitical, not purely economic.
The debt is no more than the US debt but who has the balance of payments to service the debt, my words.
Dudley I am surprised coming from you to play along with the narrative China bad US good without truth getting in the way.

1
 

Leave a Comment:

RELATED ARTICLES

The oil market is running out of easy answers

Bleeding air out of the bubble

What keeps the world’s most patient investors returning to gold

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.