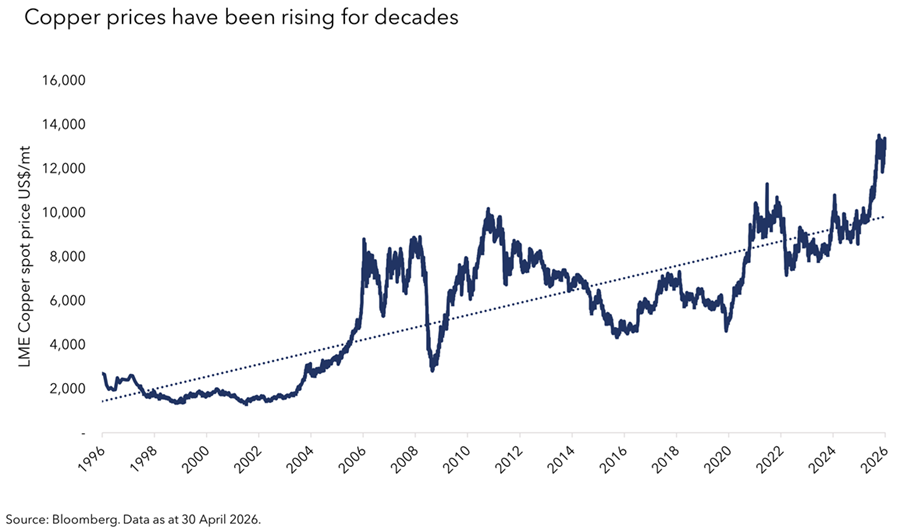
Copper has had a rough few weeks. The benchmark LME three-month price has slipped back below US$12,000 per tonne, rattled by data out of China showing warehouse inventories remain stubbornly high. Sluggish demand, the bears say. Time to move on.
Don't.
Because if you zoom out even slightly, you realise that what's happening right now in copper warehouses is almost beside the point. Copper prices have been rising for decades, and the forces shaping copper's future operate on a timescale that makes quarterly inventory data look like noise. And those forces are, almost uniformly, pointing in one direction: up.
A metal at the centre of everything
Copper is, in a very real sense, the material substrate of modern civilisation. It’s in everything around you: your phone or device, the lights in your building, the poles and wires outside.
Demand is booming as both rich and poor countries want it ever more. China and India desperately need it to industrialise. Meanwhile rich countries like Australia need it for the energy transition and for AI data centres.
The International Energy Agency projects copper demand growing from around 27 million tonnes today to 37 million tonnes by 2050: a roughly 37% increase that, compounded over decades, represents an enormous call on global supply.
The problem: global supply is struggling to answer.
The long depletion
The story of copper mining is in many respects the story of humanity itself.
For most of human history, copper was easy to find. The Bronze Age began because copper could be scooped from riverbeds and dug from shallow hillside pits and used to forge weapons. In 19th-century Michigan, prospectors stumbled upon boulders of near-pure copper – including the famous Ontonagon Boulder – that required almost no processing at all. This then helped pave the way for the electricity revolution in the US.
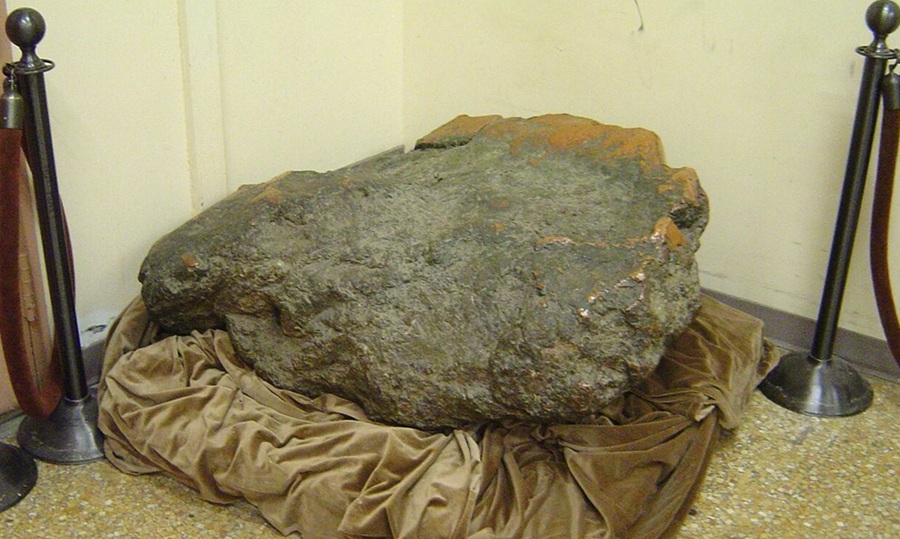
Source: Wikipedia
That era is finished.
Over the past 150 to 200 years, industrial mining has stripped away all the easy-to-reach copper. What remains is deeper underground, in harder rock, more remote, and more expensive to extract.
Today's major copper discoveries – to the extent there are any at all – tend to fall into one of two categories: very deep underground, like Resolution Copper in Arizona; or dense jungle and mountainous terrain, like Ivanhoe Mines' finds in Central Africa, the most significant new copper discoveries in two decades. Either way, the costs are higher and timelines longer.
Existing mines are not helping.
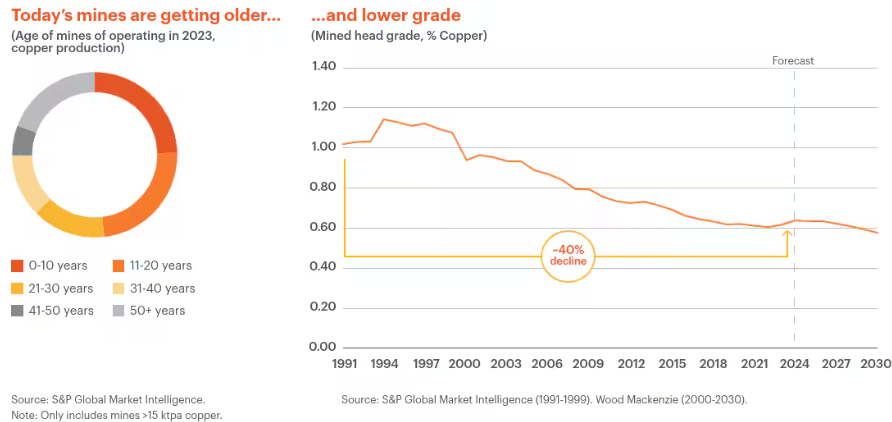
Chile and Peru, which account for most global copper output, are home to ageing mines with declining head grades. BHP's Escondida – the world's largest copper mine – exemplifies this. As grades fall, miners must move more rock, and grind it into finer powder, to extract the same amount of metal. This requires more energy, more water, more chemicals, more money, and creates more emissions. Average copper ore grades have fallen roughly 40% since 1991, according to industry data.
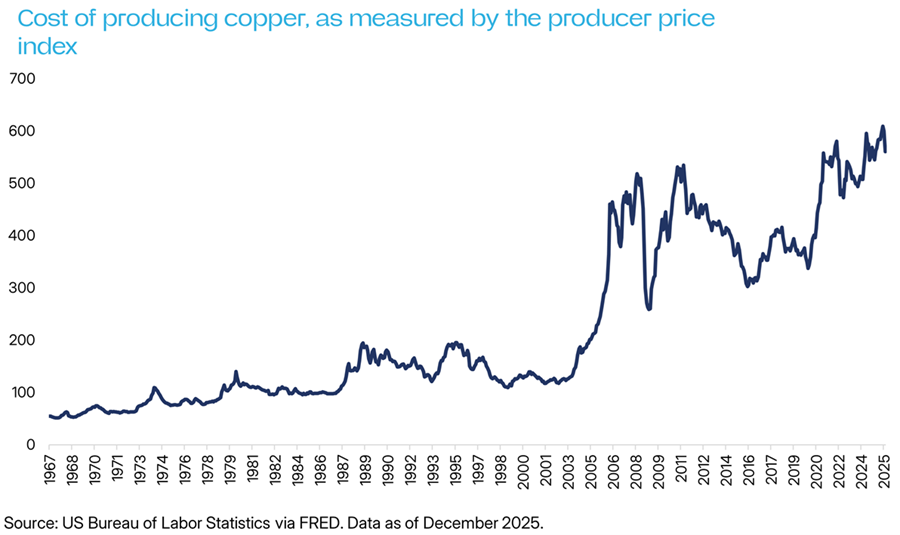
The numbers on the supply gap are stark. S&P Global’s most recent major study projects that, without significant new investment, global copper supply will fall 10 million metric tonnes short of demand by 2040: a deficit equivalent to 25% of projected demand at that point. BloombergNEF puts the shortfall even higher: potentially 19 million tonnes by 2050 if new mines and scrap recovery don't scale fast enough.
To put those numbers in context: the world's largest copper mine, Escondida, produces around 1.2 million tonnes a year. Closing a 10-million-tonne gap would require eight new Escondidas: projects that take an average of 17 years from discovery to first production.
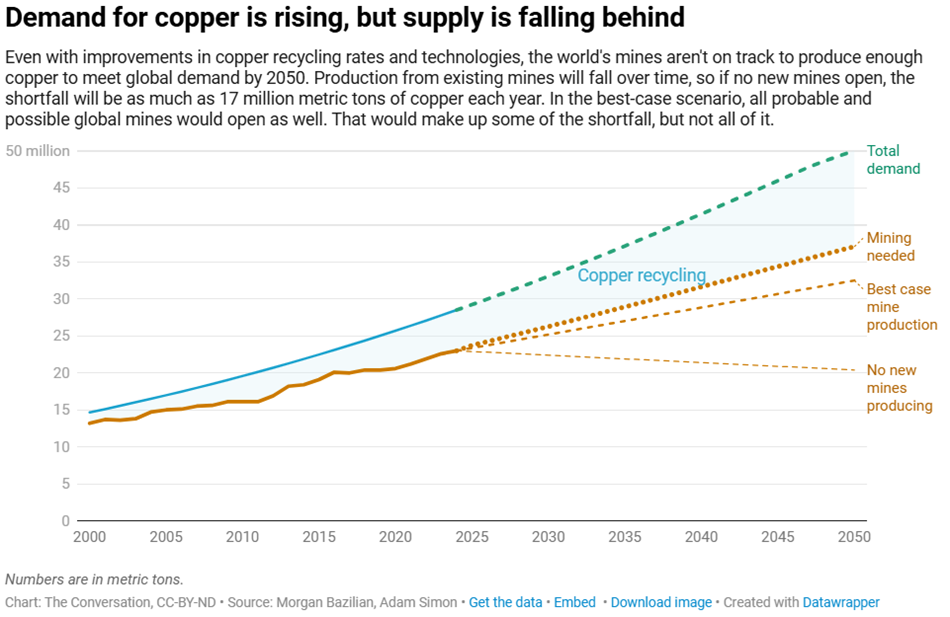
The prospect of tight copper supply has been discussed for over a decade. Yet investment in greenfield exploration has persistently lagged what is needed to meet demand growth. Even in countries like Australia that offer some of the most generous exploration tax incentives.
The talent problem nobody is talking about
The supply crunch has a human dimension that rarely makes headlines. Mining is struggling to attract the next generation of talent.
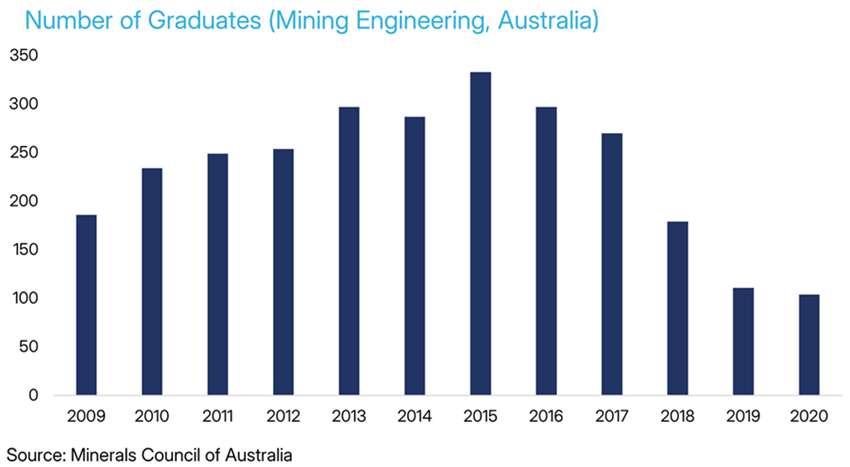
In Australia – one of the world's great mining nations – mining engineering graduate numbers have fallen by 75% since 2015, according to data from the Australian Institute of Mining and Metallurgy and the Australian Geoscience Council. Some insiders blame the cyclicality of commodity prices. But the deeper issue is cultural. For many young Australians, mining carries associations with coal, environmental destruction, and fly-in fly-out work in the desert. Meanwhile, engineering graduates are increasingly drawn to software and computing careers that offer better pay, better hours, and – frankly – better optics.
This is not a problem that resolves itself quickly. Training a mining engineer takes years. Building a pipeline of geologists, metallurgists, and project developers takes longer still. The talent shortage will act as a quiet but persistent drag on the industry's ability to respond to rising demand.
What this means for investors
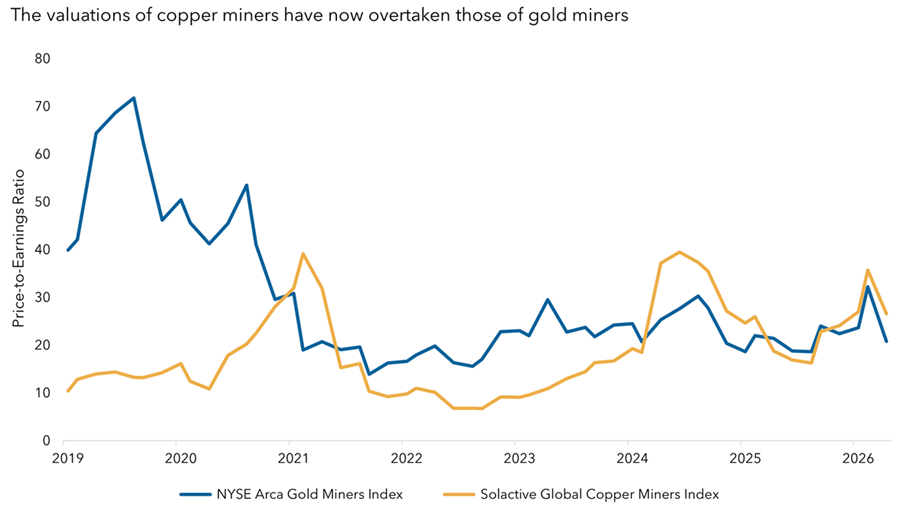
The major brokers have not missed this story. UBS, JP Morgan, and Goldman Sachs are all forecasting higher copper prices through 2026 and 2027. Copper miners, once the ugly ducklings of the resources sector, have seen their valuations surge. Their price-to-earnings ratios have overtaken both gold miners and diversified majors, making them the envy of the industry. Junior explorers are seeing similar re-ratings.
The two majors, BHP and Rio Tinto, have both made conspicuous pivots toward copper as their legacy iron ore franchises mature. This is not a subtle signal.
For investors interested in local exposure, the ASX offers a range of options, from small explorers like Hot Chili, Cyprium, Sandstone, and Aeris through to the majors themselves.
But a word of caution is warranted. Punting on individual mining stocks is genuinely treacherous territory, and the history of mining investment is littered with cautionary tales. Individual mines flood, shafts collapse, costs overrun, and management teams make expensive mistakes. Projects that look great in an Excel spreadsheet or on a resource estimate can take decades to reach production. The potential rewards are high, but so is the variance.
The more measured approach, we believe, is diversification. By owning a broad basket of copper miners rather than betting on any single stock. You may be less likely to score a ten-bagger. You are also considerably less likely to lose everything.
Conclusion
Copper's short-term price weakness is real. So is China's inventory overhang. But what matters in investing is the long game.
The world needs more copper: there’s no skirting this simple fact. And, if anything, the situation is getting worse.
The red metal's wobble is a distraction. And as Warren Buffett reminded us: “The stock market is a device for transferring money from the impatient to the patient.”
ETF Shares provides the ETFS Global Pure Play Copper Miners ETF (ASX: CPPR) which began trading on the ASX in April 2026. For more information click here.
David Tuckwell is the Chief Investment Officer at ETF Shares, a sponsor of Firstlinks. He is also a journalist and researcher specialising in finance and international politics. The information provided in this article is general in nature. Before acting on any information in this article, you should consider the appropriateness of the of the information having regards to your objectives, financial situation or needs and consider seeking independent financial, legal, tax and other relevant advice. Past performance is no guarantee of future performance.
Disclaimer: This article is issued by ETF Shares Management Limited (“ETF Shares”) (ABN 77 680 639 963, AFSL: 562766) and ETF Shares is solely responsible for its issue. Under no circumstances is this article to be used or considered as an offer to sell, or a solicitation of an offer to buy, any securities, investments or other financial instruments. Offers of interests in any retail product will only be made in, or accompanied by, a Product Disclosure Statement (PDS) and target market determination (TMD) available at www.etfshares.com.au.