Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 532

How to generate inflation-adjusted income in retirement

Inflation is a fact of life. It’s also not so great for retirees. In fact, it’s one of the biggest risks that retirees face. By constantly eating away at the value of our savings and income, inflation will slowly reduce our purchasing power in retirement – if we don’t do anything about it.

This means that we need to figure out how to deal with the effects of inflation over time. It’s not always easy, but there are a number of different ways to tackle inflation that you can use depending on your approach to retirement income. The first step is your social security benefits.

Beyond social security is your security blanket

There are a lot of reasons to like social security, but from a financial planning perspective, one of the big ones is that your social security benefits are adjusted for inflation. However big of a piece of your social security benefits make up of your retirement income, you’ll always be able to (roughly) buy the same amount of stuff with those benefits.

So, it’s essential to ensure you get the most out of your social security benefits as you can.

As great as social security is, it’s unlikely that it will cover all of the spending that you want to do in retirement. So how do you want to deal with the rest of your spending?

Well, that’s going to depend on how you want to approach your retirement income. There are two basic approaches to retirement income: Safety First and Probability-based planning. Their overall philosophy is pretty clear from the names. But in short, the Safety First approach is based around having enough reliable Income to cover at least your most essential expenses. Reliable income is income from sources that you know, to some very high degree, and usually contractually obligated, will pay you a specific amount of money on a specific date. Probability-based approaches are more willing to deal with uncertainty in how they are funding retirement income in return for higher levels of expected return.

As you would expect, these approaches will go about keeping up with inflation in very different ways.

Safety First planning and inflation

Annuities are the other big source of reliable Income. So, what can we do here?

The inflation adjusted options here for reliable income are a little thin, but we can get creative.

Even though we are focusing on reliable Income, it is worth mentioning variable annuities. There are variable annuity products that offer varying levels of reliability and inflation protection. The specifics will depend on the individual annuity that you are looking at, but the inflation protection will likely be tied to some form of investment in some way (I think I’ve put enough qualifiers here.) These can be great tools, but how you feel about the investment risk involved will play a big role in whether you think variable annuities are a viable solution.

So that leaves us with income annuities. Which means we need to get creative.

One approach that you can use is what you might call ‘sequential’ deferred income annuities to top up your reliable income over the course of your retirement when you start feeling the pinch of inflation. By using multiple annuities over time (or partially annuitizing one annuity over time) you have a good amount of control over how your income level evolves over time. You likely will not track inflation exactly, but that’s okay because your desired spending won’t track inflation exactly either.

Using this approach means that you will need to estimate how much inflation we are likely to see over the course of our retirement (and how our spending will evolve, but we need to do that anyway) so that you can create a large enough pool of deferred annuities to (roughly) maintain your desired spending levels.

Probability-based planning and inflation

If you are comfortable using risky sources of income, like your investment portfolio, to generate your retirement income (or at least part of that income – retirement planning is very rarely all or nothing), dealing with inflation is a little more straightforward. Instead of trying to tie your income to inflation, the probability-based approach is just to try and outgrow inflation and increase your distributions to keep up with inflation.

Just like anything with your investment portfolio, this approach comes with risk. Your portfolio isn’t always going to beat inflation, but it’s worked well historically. To see this, let’s start by looking at the returns of the S&P 500 over time compared to inflation, ass the US has a long history of data that we can analyse.
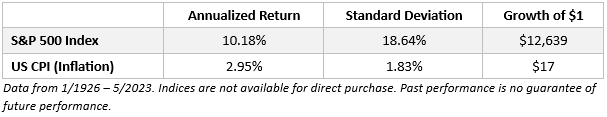
It’s not a particularly big shock that stocks beat inflation over the long term. Though, it is still impressive by how much. With how much stocks bounce around, we should be thinking about what the short term looks like - how often would stocks lose to inflation when we actually want to spend our money?

To get at this, we can use rolling returns of different lengths of time and see how often stocks beat inflation.
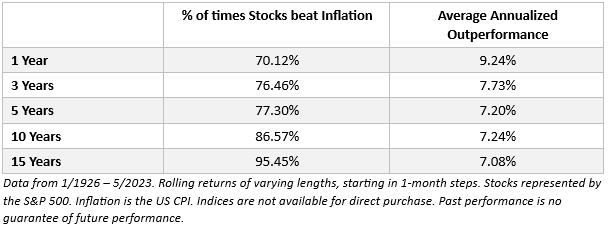
As you can see, stocks do well against inflation even over shorter time periods. Even for periods as short as one year, the S&P 500 Index outperformed inflation (just) over 70% of the time – and by a lot. In the average one-year period stocks outperformed inflation by 9.24%. Though it’s always important to turn these sorts of statistics around – that means that stocks lost to inflation a little less than every third year. However, outperformance here makes up for a lot, as we can see in the longer time periods.

As we would expect, the longer the time frame we are looking at the more likely stocks are to outperform inflation (though the average outperformance does come down a bit). Once you get out to 15-year periods you have a better than 95% chance of outperforming inflation. As always, with a probability-based approach, we’re talking about probabilities, but stocks definitely seem to outgrow inflation, even over reasonably short periods of time.

But very few retirees are using a 100% stock portfolio. So, let’s bring bonds into the picture. How do they do against inflation? To keep things simple, we’ll use 5 Year Treasury Notes as our stand in for bonds.
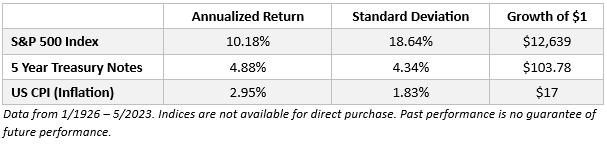
Bonds obviously don’t have (nearly) as high returns as stocks, but they also don’t have (nearly) as much volatility as stocks. There’s less randomness around those returns. So how often do bonds beat inflation?
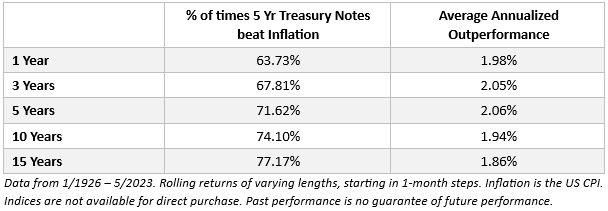
Still often. Not quite as often as stocks. And certainly not by nearly as much as stocks do, but it’s likely that even a 100% bond portfolio would stay ahead of inflation, even over short time periods.

But, again, most retirees don’t have a 100% bond portfolio. You build your portfolio to fit your risk tolerance and goals. You intentionally find the mix of stocks and bonds that fits you. So, let’s take the stereotypical ‘retirement portfolio’ of 60% stocks and 40% bonds and see how it does over time.
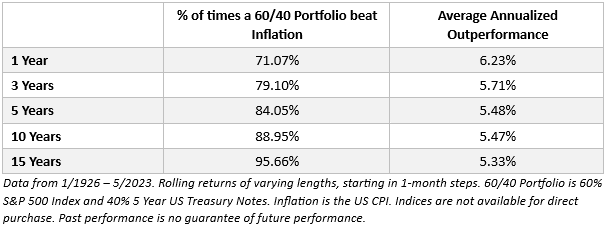
It does well. In fact, this is a good example of the magic of diversification. If you go back and compare the numbers, over every length of time we looked at, the 60/40 portfolio is more likely to beat inflation than the 100% stock portfolio (though not by quite as much).

But even over a 15-year period, there’s still a nearly 5% chance that our 60/40 portfolio won’t outpace inflation. That’s not a big chance, but it’s something – and longshots do land once in a while.

There is no perfect solution to inflation. It’s like most things in retirement planning – there are a whole bunch of different solutions, all with their own set of tradeoffs. The trick is finding the set of solutions that has the right mix of tradeoffs.


Bob French is an investments specialist at Retirement Researcher and the Director of Investment Analysis at McLean Asset Management. This article was first published by Retirement Researcher and is reproduced with permission. This article provides general information only and as such, does not consider your personal financial situation or goals.


  •   25 October 2023
  • 8
  •      
  •   
8 Comments
Mark Hayden
October 26, 2023

Wow, that was a confusing article. Long-term investing is not as complicated as indicated above. But I agree that inflation is a great challenge for investors in the drawdown phase.

John De Ravin
October 26, 2023

You say you’re not aware of any inflation protected annuities being offered in Australia. But Challenger appears to offer lifetime annuities that are linked either to the cash rate, or to inflation, according to information I found on their website. So I’m a bit puzzled.

Brian
October 26, 2023

Very interesting and helpful.
.. "As you can see, stocks do well against inflation even over shorter time periods. Even for periods as short as one year, the S&P 500 Index outperformed inflation (just) over 70% of the time – and by a lot. ..."
Actually, 'As you can see, stocks have done well etc...'
Timing IN, and out, remains very important.
Whenever I read such articles I'm always reminded of the oft quoted disclaimer:-
Past performance is ......

Kevin
October 26, 2023

Nobody mentions good quality REITS . Prime commercial property with long leases and no headaches to manage

Stella
October 27, 2023

Direct property is a good one which has served us well - long term capital growth and (mostly) income growth as well.

Ted
October 27, 2023

Why are we sourcing an American article which has no idea about franking credits and the fact that dividend payments are much higher in Australia than the US market..Bonds are not ready accessible to retail investors and in the USA REITs are considered 'alternatives' whereas Australia treats them as a normal asset class.

ashley owen
October 27, 2023

"Lost me at ‘sequential deferred income annuities'!

Peter Vann
October 27, 2023

Ever since I entered the investment industry in 1987, I’ve been intrigued at the regular reference to the benefits of the 60/40 portfolio for “long” term investing. Bob French’s analysis again provides support for 60/40.

If the 40 part has a significant portion of an annuity with inflation linked payments (eg the Challenger product referenced below by John De Ravin) rather than traditional cash and fixed interest, then the small likelihood of not outperforming inflation may be even smaller; sorry, I haven’t done calcs to support that but it is intuitive.

Also in Australia, many retirees with low asset bases are eligible for part or full access to the Government provided “inflation”linked payment stream where the inflationary factor is based on various inflation measures.

Thus stocks, inflation linked annuities and the fallback Government inflation linked pension go a long way to support inflating expenditure.


Leave a Comment:

RELATED ARTICLES

Why spending more in early retirement can improve lifetime income

Australia has saved $4.5 trillion for retirement. Here's what matters more

Inflation BIG picture: Boomers got lucky, next Gen not so much

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.