Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 679

Making a case for the 40 year mortgage

Australia’s housing-affordability debate usually centres on prices, deposits and interest rates. Less attention is paid to mortgage terms.

Thirty years has become the conventional Australian home-loan term, but there is nothing sacrosanct about that number. If the price of housing has structurally increased relative to household income, it is reasonable to ask whether the repayment structure should also change.

Australia already has a real-world example. Great Southern Bank offers eligible first-home buyers terms of up to 40 years. The structure is limited to owner-occupiers, requires at least one first-home buyer, and is available only to applicants aged 40 or under. Investment property is excluded.

The appeal is evident in the numbers. Consider a $600,000 principal-and-interest loan at a constant 6% interest rate. Over 30 years the monthly repayment is about $3,597. Over 40 years it falls to about $3,301, a reduction of $296 a month, or 8.2%.

A borrower able to service $3,597 each month could theoretically support a loan of around $654,000 over 40 years instead of $600,000 over 30 years.
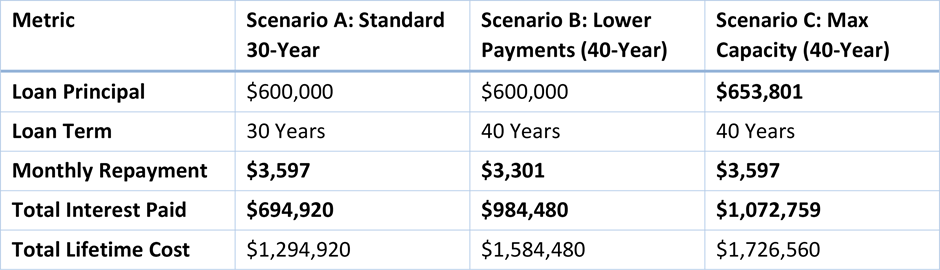
That does not mean a bank would automatically approve 9% more debt. APRA-regulated banks still assess borrowers using a mortgage serviceability buffer of 3 percentage points, along with living expenses, liabilities and other credit criteria. High debt-to-income lending is also subject to macroprudential limits.

The key point is simpler: loan maturity changes the minimum required repayment and therefore forms part of affordability.

Mortgage maturity is widely recognised as part of the affordability question. IMF economists Nina Biljanovska, Chen Fu and Deniz Igan developed a cross-country affordability measure that includes house prices, income, mortgage rates, loan-to-value ratios and mortgage maturity. Their framework recognises that the same house price can have very different repayment consequences depending on how the mortgage is structured.

The trade-off is that lower monthly payments come at a high lifetime cost.

If the $600,000 loan remained at 6% until maturity, total interest would be about $695,000 over 30 years and $985,000 over 40 years. A 50-year mortgage would reduce the monthly payment further to about $3,158, but total interest would rise to about $1.295 million.

The extra decade from 40 to 50 years saves only around $143 a month while adding more than $310,000 in lifetime interest under the constant-rate assumption.

On these assumptions, a 40-year mortgage appears a more defensible compromise than a 50-year term.

The case for a longer term is strongest when viewed through the life cycle of a first-home buyer. RBA research has found first-home buyers tend to be younger, have higher loan-to-value ratios and smaller liquidity buffers when they enter the market. Yet they have historically experienced relatively strong income growth around the years of home purchase and have not been more likely than other owner-occupiers to experience mortgage arrears.

A younger borrower may therefore have the weakest income at precisely the stage when housing needs are greatest. A longer contractual term can reduce the compulsory repayment early in the borrower’s career while preserving the option to pay faster later through additional repayments, offset savings or refinancing.

Importantly, a 40-year mortgage need not be a 40-year repayment plan. Instead it can operate as a lower repayment floor rather than a target repayment horizon, allowing borrowers to accelerate repayments as incomes rise.

Sweden provides an instructive international comparison.

It is sometimes described as having 100-year or even “generational” mortgages, but that is an oversimplification. In 2013, Swedish regulator Finansinspektionen reported that among first mortgages that were being amortised, the average actual repayment period implied by the repayment rate exceeded 140 years. The issue was not a standard 140-year loan contract. Principal was simply being reduced extraordinarily slowly.

Sweden later strengthened amortisation requirements. Under rules effective from April 2026, mortgages with an LVR above 70% generally require annual principal reduction of at least 2%, while mortgages above 50% and up to 70% require at least 1%. At the same time, Sweden raised the maximum LVR for a home purchase to 90% and removed an extra amortisation requirement previously applied to borrowers with very high housing debt relative to income.

The Swedish lesson is therefore balanced. Lower entry barriers can support ownership, but principal repayment still matters.

For similar reasons, I would be cautious about long interest-only periods for first-home buyers. Interest-only repayments on $600,000 at 6% are $3,000 a month, but after 10 years the borrower still owes the original $600,000 principal. Eventually converting to principal-and-interest repayments can create a significant repayment shock.

A 40-year P&I loan lowers the minimum payment but still reduces principal from day one.

There is also a broader policy risk. Making it easier for everyone to borrow more does not necessarily make housing more affordable. In a supply-constrained market, increased purchasing power can be capitalised into higher prices. In that case, some of the benefit accrues to existing homeowners rather than first-home buyers.

The IMF’s latest assessment of Australia has warned that demand-side home-buyer assistance can add to near-term price pressure when housing supply is constrained.

For that reason, any extension of 40-year mortgages should be confined to owner-occupiers rather than investors.

A targeted approach would be more defensible: younger first-home buyers, owner-occupied property, normal serviceability rules, principal-and-interest repayments, and the ability to repay faster without material penalty.

The purpose should not be to maximise debt. It should be to recognise a life-cycle mismatch between when younger households need housing and when their earning capacity is strongest.

Longer mortgages will not solve Australia’s housing shortage. They cannot substitute for planning reform, infrastructure and new construction.

Yet mortgage structure remains one component of affordability. A carefully targeted 40-year P&I loan could modestly improve early cash flow for younger first-home buyers while retaining prudent repayment discipline.

The main long-term risk is that borrowers carry mortgage debt further into middle age and potentially into retirement. For that reason, longer loan terms should be accompanied by flexibility to accelerate repayments as incomes rise, rather than becoming a mechanism for permanently higher household leverage.

As with most housing policies, the key is targeting. If longer terms are used to help first-home owner-occupiers rather than to expand investment leverage, and if housing supply rises alongside them, they may deserve a larger place in Australia’s affordability toolkit.


Jade Xie is an MFAA accredited Mortgage Broker and Managing Director of Easyhome Mortgage. She has approximately 25 years of experience in finance, banking and credit in Australia and New Zealand. Her interests include housing finance, mortgage credit, household financial capacity and property-market policy. The views are personal and are general information only.


  •   9 September 2026
  • 19
  •      
  •   
19 Comments
Dudley
September 10, 2026


"We should not be encouraging more debt for longer at an early stage in life.":
Abolish mort-gages then price of homes would decrease to meet the ability of the median worker to save.

6
John
September 10, 2026

Back in the days when housing was affordable, you would be lucky to get a LVR of 70%. Now its up to 95%. More money chasing the same housing stock. Yet governments do nothing to address this issue.

6
Noel Whittaker
September 10, 2026

I've been fighting against 40 mortgages for 30 years. Because of the way compounding works, the interest in the last 10 years is astronomical -

10
Ben Snooks
September 13, 2026

My problem with longer mortgage terms is that the argument that incomes rise and therefore so does the ability to repay more principle doesn’t seem to work any more.

The cost of living has taken a huge chunk out of disposable incomes over the last 10 years, while at the same time interest rates are higher now than they also were 10 years ago.

Someone on $100k income could afford to borrow $480k 10 years ago. Now that same person would struggle to pay the standard repayments on that $480k mortgage over 30 years, and living expenses, on an income that may have only risen to $130k over 10 years. Insurance, utilities and food costs have risen more than incomes over the last 10 years therefore the argument that people will have more money in the future doesn’t stack up.

Furthermore, first home buyers may saddle themselves up with a large mortgage only to have increased costs of having children and paying for childcare, healthcare and expense for children. Their disposable income naturally drops then and the big mortgage is also a drag on living standards.

Therefore we probably want shorter mortgage where people build up equity faster, almost as a form of forced savings inflate as of allowing them to borrow more or delay repayment.

1
Damien Morris
September 15, 2026

The interest on housing loans is not compounded when repayments are based on P&I. Have you considered the impact of the time value of money, which is especially relevant during the later stages of the loan?

peter care
September 10, 2026

A 40 year mortgage is a sure sign you cannot afford the property. All this will do is make sure you pay significantly more interest in your lifetime, and thus will make you poorer.

I would go the other way, back to the 1960’s and 1970’s when mortgages were limited to 25 years. If you cannot pay off a home in 25 years then it is likely too expensive for you. Reducing the length of mortgages will mean you can borrow a lower amount, which in turn will mean you pay less to purchase thst home and you will pay less in interest over your lifetime.

The side benefit is that if banks are lending less for housing, there is more money available to lend to businesses, which is good for the economy. Reducing the maximum length of the mortgage is a much better alternative for the purchaser and the economy.

6
Damien Morris
September 10, 2026

One very important variable that is not mentioned in this article is the time value of money, or putting it in a more simple form, inflation. The RBA's target inflation rate is 2.5% If you compound that over a 25 year period the purchasing power of your monthly repayment significantly decreases. In other words it becomes increasingly less significant in relation to your income. That's why discussing total repayments over the term of the loan is mostly irrelevant.

5
Dudley
September 11, 2026


"purchasing power of your monthly [principal] repayment significantly decreases":

Interest rate exceeds inflation.

Mort-gage net real interest rate considering tax 30%, nominal interest rate 6%, and inflation 3%:

Lender, after tax, real interest rate;
= (1 + (1 - 30%) * 6%) / (1 + 3%) - 1
= 1.17%

Borrower, before tax, real interest rate:
= (1 + 6% / (1 - 30%)) / (1 + 3%) - 1
= 5.41%

1
Jack
September 10, 2026

We like to say that rent is dead money, but we forget that the mortgage interest we pay to the bank, is the rent we pay on the outstanding principal. That’s dead money too.

The longer the loan, the more interest is payable. For any given loan, the interest rate is the key variable. The Sydney harbour bridge was finally paid off in 2012 - an 80 year loan. That long loan made sense because the interest rate was low. In the 1980’s, when interest rates fluctuated between 8.5% and 13.5%, it made sense to repay a mortgage as quickly as possible. It is the same logic for young people to attack their highest interest rate debt (the credit card) first.

If you don’t like paying rent to the bank, you should extinguish the mortgage as quickly as possible because that then releases resources for other projects such as adding to super or home renovations.

3
Dudley
September 09, 2026

Bunk of Dad and Mum™
FastSaver Home Buying Calculator - Australia V14

https://djm-gm.github.io/index.html

Save 80% of after tax income, buy home without mort-gage in under 4 years, cash on knocker.
Or accumulate 20% 'deposit' in 8 months; 9 months if renting.

Suit those with less predictable income.

2
Andy R
September 09, 2026

The 40 year mortgage concept is already common practice in Australia.

AKA 'refinancing' Its not an accident that Aussies refinance back to a fresh 30 year term every 4 to 5 years dropping their repayments.

Would it make a difference? unlikely..

2
Gary
September 10, 2026

Great piece. It looks like the author really knows what is happening in the industry. Traditional 30-year structures simply aren't working for everyone anymore. While a loan term of up to 40 years does mean paying more interest over time, the lower monthly payments significantly improve loan serviceability and could make homeownership a reality for a lot of people.Granting a longer term is not about encouraging more debt; it is mainly about helping young first-home buyers get into the market earlier. A longer term reduces monthly payments, easing living cost pressures just as their careers and incomes are starting to build up.I believe this is a very good idea that should expand from a few niche lenders to the major banks in Australia. The majors should seriously consider longer loan terms to help this specific group of young buyers. To mitigate risks, specific terms and conditions—or even a temporary interest rate discount—could be introduced. Policies could also be structured to encourage borrowers to gradually increase their repayments as their income grows over time, helping them pay off the loan much sooner than the full 40 years. Extending a mortgage term up to 40 years does not have to equal making young people pay a mortgage for 40 years."

2
CC
September 10, 2026

There's a bigger case for doing more to lower the absurd cost of housing in this country

1
John
September 10, 2026

No way. Existing owners rarely want prices to drop or stop growing. If housing becomes affordable, more people will want to live here. No thanks. Sydney is full.

Steve
September 10, 2026

It's not the length but the variable rate that's the problem. The US with 30 year fixed rates has none of our hand bringing when rates rise. Fixed rates, payments known with confidence. And you can refinance if rates .

Dudley
September 12, 2026


"standard loans backed by Fannie Mae, Freddie Mac, or government agencies cannot be ported":
Tied to nominated property. Change home, start a new mort-gage at prevailing interest rate.

Barry
September 13, 2026

Good to see someone who knows how to spell the word principal. You would be surprised how many mortgage brokers who work in the lending industry every day can't even spell the word principal.

Kim
September 15, 2026

As a Bank Manager 30 years ago, I'd never do 30 year mortgages. The end result is terrible with amount of interest paid. However, loans at that time were in the region of $200k to $350k -not the $650/$750k now. Times change but still unfair to the borrowers.


Leave a Comment:

RELATED ARTICLES

The housing market is heading into choppy waters

Michael Witts: changes over the final 12 years of my career

Will the house price boom be a boon for Australian banks?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.