Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 265

Strangers to themselves in retirement

Behavioural economics has revealed the vast gulf between what people say they want and how they behave. It makes life challenging for financial planners, superannuation funds and financial institutions attempting to deliver the right products and services.

However, new approaches built on data, analysis and algorithms can help solve the paradox of advising people who are effectively strangers to themselves.

The difference between stated and revealed preferences

Financial planning questionnaires typically ask clients for stated preferences such as how they believe they will react in different circumstances, but decision theory and behavioural economics explain why people’s actions regularly deviate from their intentions.

For example, the second-highest financial priority cited by seniors in a recent ASIC survey was "having enough money to enjoy life and do what they want to do" (69%). Yet a significant proportion of retirees spend less than the age pension according to the Milliman Retirement Expectations and Spending Profiles (Retirement ESP).

Meanwhile, the industry has long known that the stated preference for reliable retirement income doesn’t translate into sales of products such as annuities.

These inconsistencies suggest retirees are prone to stronger opposing forces that change their behaviour in ways they don’t realise. It makes setting personal goals a complex task because people don’t know themselves, let alone how to balance competing desires.

Comprehensive data helps. The Retirement ESP has revealed several surprises about the behaviour of retirees which differs from industry assumptions.

Shachar Kariv, Professor of Economics at UCBerkeley, recently pointed to gamification, or the process of melding game-like actions with everyday tasks, as a more accurate methodology than questionnaires. It can show how clients will actually behave (their revealed preferences) rather than how they think they will behave (their stated preferences).

“People will enjoy it because it will be a game,” Kariv said at a recent Milliman breakfast event. “It’s going to be fun and fast. You can do it from your phone or tablet and in different periods of time.”

For example, a coin flipping gambling game can reveal players’ risk-return trade-offs and preferences in a mathematically-sound approach. Various studies are now showing, with statistical certainty, just how certain segments of the population behave by using these techniques.

The problem with risk

Understanding the risk that hides behind investment returns is complex.

Individuals may think of risk in terms of the possibility of investment losses or in terms of not achieving their financial goals. The asset management industry on the other hand typically defines risk in terms of the distribution of returns (volatility). This disconnect between everyday Australians and investment professionals can lead to poor outcomes.

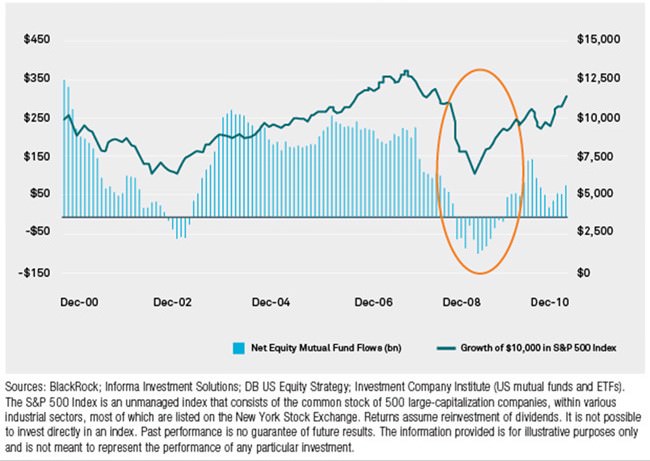
The problem is exacerbated by the fact that individuals make poor predictions (stated preferences) about their level of risk tolerance. Many investors withdraw or switch their portfolios to cash when equity markets decline. The following chart is now dated but fund managers confirm similar patterns of flows recently where performance varies against a benchmark.

S&P 500 Index performance vs. 12-month equity mutual fund flows
A secondary issue is the way the industry gauges investors’ risk tolerance with standard risk and return questionnaires. As Kariv, who is also Chief Risk Scientist at risk profiling firm Capital Preferences, said:

“I would claim there is no scientific basis whatsoever for this method. A survey is like designing a bridge without writing any mathematical equations. You will not drive on a bridge that the engineer has designed without writing any mathematical equations.”

Accurately measuring risk capacity, not just risk tolerance, is essential if investors want to achieve their goals. Risk capacity is the level of risk an investor can withstand while still meeting their objectives with a reasonable level of certainty.

For example, many older investors have higher levels of loss aversion, which leads to lower risk tolerance levels. However, wealthier investors with high levels of cash to fund their day-to-day lifestyle can have higher levels of risk capacity.

Risk capacity is also relevant for younger investors. The ASX Australian Investor Study 2017, which surveyed 4,000 Australian residents, suggests that young investors may be more risk averse than previously thought. It found that 81% of investors aged under 35 were seeking guaranteed or stable investment returns.

However, young investors have a higher risk capacity when it comes to their retirement savings, given that they will have decades in the workforce and can withstand market gyrations.

Analysis can discern the difference between risk preferences and risk capacity and help advisers balance the tension to find a solution that works for their clients.

Most people do not know their spending or lifestyle habits

People are bad at estimating how much they spend, which makes it difficult to choose the optimal investment strategy to lift retirees’ standards of living.

The evidence is the Household Income and Labour Dynamics in Australia (HILDA) data, which surveys more than 9,500 households. It provides information and insight into everyday Australians. However, spending surveys of this nature have shortcomings when applied to the context of financial planning.

For example, an industry analysis estimated that the median expenditure for households aged 65-69 was $24,640 a year while the average was $33,944. The Retirement ESP, which uses bank transaction data from more than 300,000 retirees, shows that the median couple aged 65-69 spends $34,858 while the average expenditure was $43,675. This is a significant difference even when accounting for the different time periods of the underlying data (2015 versus 2017).

Other differences are also revealed when people qualitatively assess their own lifestyle compared to a quantitative assessment of data. For example, 2,527 people surveyed in the 2015 HILDA survey said they smoke at least one cigarette a week. However, 38% of these respondents reported spending no money each week on cigarettes.

These discrepancies in spending survey data are not material when taken in the appropriate context. However, they do highlight the potential risks of relying on spending survey data to form views about the spending needs of future retirees.

Financial advisers, and increasingly, super funds, develop an understanding of clients’ and members’ qualitative information and life experiences because they spend time with them. However, a mix of tools powered by data, analysis, and algorithms can help them bridge the gap between the things people say they want and how they actually behave.

This type of quantitative information is a key component of this approach and can provide a clearer view of retirement expectations and what people need to do to achieve their goals.


Jeff Gebler is a Senior Consultant at actuarial firm, Milliman. Read more about the Milliman Retirement ESP here.


  •   2 August 2018
  • 2
  •      
  •   
2 Comments
Peter Thornhill
August 02, 2018

Thank you for reaffirming that volatility is a poor measure of risk.

Steve
August 04, 2018

A very thought provoking read Jeff. From someone who does not have industry experience, I wonder whether one's risk capacity is the primarily driver of the behavioural aspects of risk tolerance. Our risk tolerance generally diminishes as we age (especially after having children). On the other hand, I would have thought that our risk capacity (in a financial sense) should be positively correlated with age. The ability to "take a hit" should be greater with age. Hence, the need for people to start early on their financial journey to build up that risk capacity.

However, I suspect that if we don't embrace risk (within reason) from a young age then our risk capacity will be diminished as we close in on retirement. If a retiree or soon-to-be retiree has limited risk capacity, you could be excused for thinking that their risk tolerance level is even further diminished. However, is it possible that the reverse is true given the environment we live in today (low interest rate environment are pushing people who are generally risk averse into equities, real estate and futures).

Some years ago, I attended a traders group and the most striking thing that stood out was the overwhelming number of older male members that made up that group with no apparent experience in equity or futures markets. My instance thought was that they had left it too late (failed to build up sufficient risk capacity in their earning years) and were now trying to play catch up.

If the ASX Australian Investor Study 2017 is the roadmap for the future, then the 81% of investors aged under 35 who are currently seeking stable investment returns may need to re-evaluate otherwise their financial plan for independence may be based on trading futures contracts in their 70s.


Leave a Comment:

RELATED ARTICLES

How much super should you have?

Our investment thinking changes as we get older

Retirement planning is not just about income

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.