Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 415

Super performance test will destroy viability of some funds

The Your Future, Your Super (YFYS) annual performance test will apply to MySuper products from 1 July 2021 and ‘trustee directed’ products from 1 July 2022. Some of its key features are:

  • Product performance is tested against a benchmark comprising prescribed indices weighted in line with a fund’s strategic asset allocation (SAA). This means that the test measures the effectiveness of a fund’s implementation of its strategy relative to its YFYS benchmark, not the suitability or performance of the strategy itself.
  • The performance measurement period is generally eight years (seven years for the first test). While a year of ‘good’ performance helps, each year is the start of a new performance period and so consistency of performance will be rewarded.
  • A product passes the test provided the product return (including allowance for administration and advice fees) does not underperform the benchmark by more than 0.5% pa.

A test with teeth and major consequences

The result of failing the performance test is highly visible. Funds must send their members a notice (by paper mail, adding another expense) commencing with the words:

'Your superannuation product has performed poorly. You should consider moving your money into a different fund'

It's an unpalatable action for any fund. Two successive years of failure will see a product barred from accepting new members, which would damage cash flow and destroy the viability of most funds in a reputational sense.

So, this is most definitely a test with ’teeth’. All funds will weigh up the priority that should be given to meeting the performance test relative to other objectives. Some, perhaps most in the longer term, will change how their investment portfolios are designed and managed.

The risk of underperformance

As an indication of what might be in store, using APRA’s December 2020 MySuper Product Heatmap, 11 single strategies, and a similar number of lifecycle strategies, were more than 0.5% p.a. behind the Listed SAA Benchmark over the six years to 31 December 2020. It’s important to note however that the YFYS performance benchmark differs slightly from the Heatmap benchmark.

Looking forward, a year-by-year approach which blends past performance with forward-looking modelling will be required for products that have experienced underperformance in the past eight years.

Longer term, our analysis of a subset of MySuper options suggests a typical forward-looking probability of failing the performance test over a single eight-year period falls in the range of 10-15%. There is obviously some variability between products, with estimated tracking errors relative to the YFYS benchmark ranging from 2-4% per annum and probabilities of failing the performance test over a single eight-year period ranging from 6-16%.

While the likelihood of failing the test over a single eight-year period is a useful starting point, it doesn’t accurately represent the prospect of the fund failing the performance test over a longer time period that incorporates a number of rolling eight-year time periods.

The chart below demonstrates the cumulative probability of failure over longer periods, assuming a 10% likelihood of failure over a single eight-year period.

Cumulative probability of failing the performance test
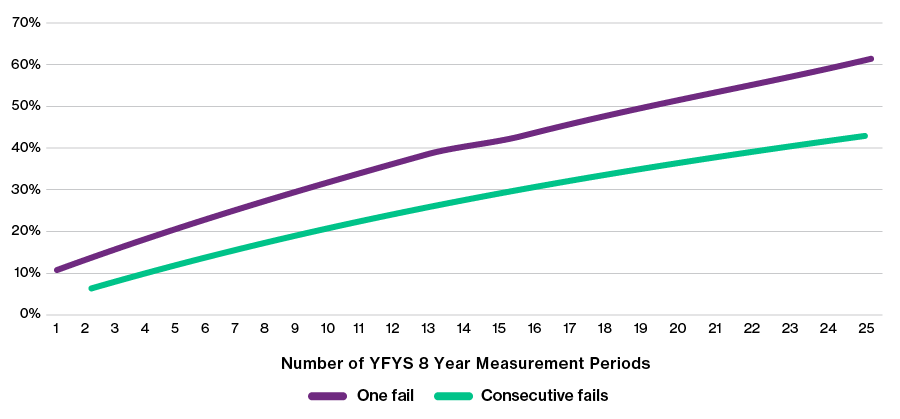
If we look at 10 consecutive performance measurement periods, covering a total of 17 years of fund performance (i.e. the first test covers years one to eight, while the 10th test covers years 10-17), the cumulative probability of underperformance reaches 35%. If we extend this to 20 measurement periods, then the cumulative probability of underperformance increases to over 50%.

Over the same period, the likelihood of failing the test in two consecutive years is also around 35%. The longer-term risks of falling foul of the test are clearly material.

Implications for super funds

We have already seen funds make portfolio and product changes, in anticipation of the test becoming law. Conceivably, we could see a bifurcation of strategies adopted.

Those with a strong brand name and market presence, or a well-defined and ‘sticky’ membership base, may consider a failure of the test (at least for one year) to be manageable and hence may be comfortable sticking with their existing investment approach and strategy.

Those with a weaker franchise might make passing the test their highest priority, dialling down the underperformance risk to an acceptably low level.

The broader implications of the YFYS package will play out over several years. It seems clear though that prioritising investment objectives, including determining how much emphasis to place on the YFYS performance test, will become a top tier issue for all funds.


Nick Callil is the Head of Retirement Solutions and Tim Unger is Senior Investment Consultant at Willis Towers Watson Australia. This article is general information and based on a current understanding of the YFYS legislation.


  •   7 July 2021
  • 13
  •      
  •   
13 Comments
JohnPascoe
July 07, 2021

Does this apply to personally self managed super funds with the maximum of 4 members [soon to be 6] ?

Graham Hand
July 07, 2021

Hi John, no, the test does not apply to SMSFs. You're on your own with that one.

George
July 09, 2021

Nothing to do with SMSFs. SMSFs and SMSF trustees are not regulated by APRA.

Chris
July 07, 2021

It seems this new legislation has a major "unintended outcome", or perhaps it was fully intended by the ideologues within the LNP ??

Greig Meyer
July 08, 2021

It is unbelievable that such a dumb idea has ever made it this far. It is the superannuation equivalent of 80% of drivers believing they are above average. By definition 50% of all funds must fall below benchmark, whatever the benchmark is. The impact of this policy on funds management in Australia is going to be far reaching. It is going to impact on companies and cost of capital, and mean that rational thinking about investing is going to be pointless for the majority of money invested in the Australian share market. For companies the only thing they will need to do to survive will be to make sure that they are big and then all the super funds will have to buy their shares regardless of the quality of management or the merits of the business.

Martin
July 10, 2021

If the benchmark is an independent target - say ASX 200, then it is wrong to say that by definition 50% will fall below that. That statement is correct only if the benchmark is the average of all the funds, which it is not. The portfolio benchmark will be a blending of individual external benchmarks for various asset classes weighted by the asset allocation. The sadder part is that funds will tend to adopt portfolio allocations to mimic the test comparator allocations which will mean that innovation will be stifled. It is however a well overdue improvement to highlight fund managers who take fees yet deliver outcomes worse than the index they seek to beat. As James Bond put it, “three times is enemy action”.

Neil Cox
July 08, 2021

Chris has nailed it. This is nothing to do improving superannuation performance. It's all smoke and mirrors to hide the real alternate agenda.

Steve
July 10, 2021

This is really about reducing the number of super funds for the regulator to monitor, and like Hayne2 is about about culling out the number of advisers to supervise. It has absolutely nothing to do with increasing competition & everything to do with increasing fees to the regulator, while reducing their work load. Not unlike State Govts preferring large residential developments over backyard subdivisions. 

Steve
July 10, 2021

It’s about time those super funds that rip off members with high fees to pay for there overinflated salaries were brought to account.

Jerome Lander
July 10, 2021

Great article. If super funds weren't already overly "benchmark" focussed instead of being client focussed, they will be now. Any good fund needs to have the opportunity for genuine and meaningful active management, and that is being removed for these institutions as they are effectively forced to comply with government edict. Wealthy investors will continue to invest through SMSFs and allocate their capital elsewhere, where it can be managed in alignment with their interests.

Philip Carman
July 10, 2021

In my 40 years in the Money Business, dealing with a range of people from highly paid/sophisticated managers of billions to Mums and Dads, I've found very few who deeply understand risk and reward and fewer still who genuinely dovorce themselves from fear and greed as well as the group-think that pervades markets. Fewer still truly know themselves and their insecurities...
Adding a layer of regulation around managed fund performance based on fear of being caught out on a limb that has not (yet) been recognised as sensible (like being short the capital markets in 2006/07) only serves to ensure that few will ever make calls against the crowd...which ultimately must be done to protect capital - sometimes for two consecutive years.
I well remember BT being "wrong" in late 1985/early 1986 when they were aghast at excessive valuations, only to be proven correct in late 1987, but only after they, too, had been dragged (a little) away from their preferred position (of an even lower exposure) by advisers, other managers and the commercial necessity of not being too "out of kilter" with the mob.
The likes of Kerr Neilsen, who had been an important cog at BT in the 1980s, were deeper thinkers and better than the rest (someone has to!) and went on to lead some genuinely independent thinkers (although still at the mercy of the dumb mob, to whom they had to market theior wares) in setting up some leading investment houses. Thinking differently from the mob gets punished by blunt instruments that measure performance in the short term, but ultimately can deliver better and safer outcomes - sometimes.
Here's the thing: if government (and commentators) believe they know best they should set up their own funds and test themselves. For example: the Future Fund should be available to all Australians who wish to use it and then it should be allowed to compete in the open market. Those two ideas are, of course, intrinsically linked and provide perhaps the only possible solution to the problems of ignorance, envy and fear that pervade human's attempts to both understand and beat markets - of which they comprise the core.

Steve
July 10, 2021

No Philip - Here’s the thing - start performing for clients instead of feeding the funds overinflated fees and salaries. True Client focus would be good rather than just rhetoric. Then the investment industry may just climb itself off the bottom rung of trust they are now on and clients may start believing that they are truely working for the clients and not just for themselves.

Guy Metcalfe
July 11, 2021

The cumulative probability of failing the performance test graph is somewhat misleading. There is at least one way to guarantee a fund passes the test every year. Implement the policy portfolio with low-cost index funds and keep total fees and costs well below 0.5%.


Leave a Comment:

RELATED ARTICLES

Testamentary trusts survived the trust tax. The drafting battle has just begun.

Testamentary trusts have secured the CGT exemption

Why systemic risks from ‘Big Super’ may be overplayed

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.